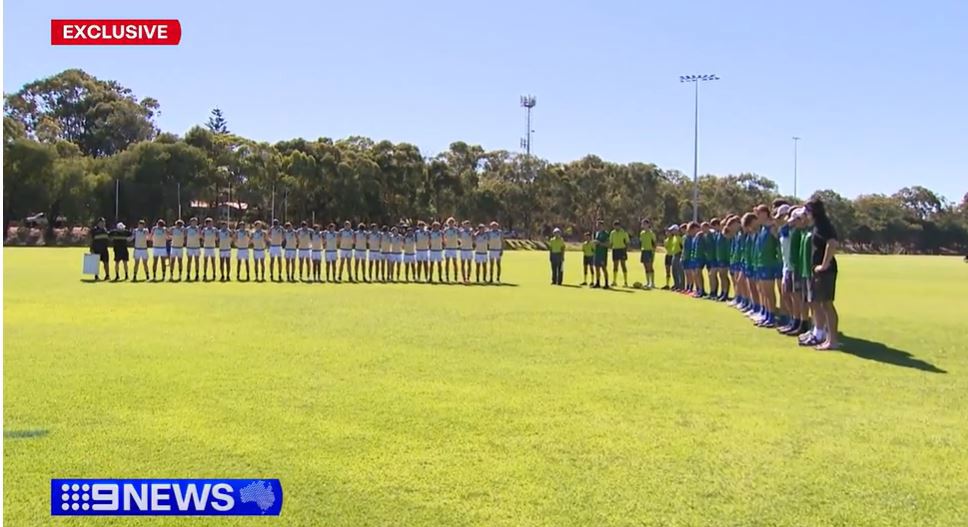
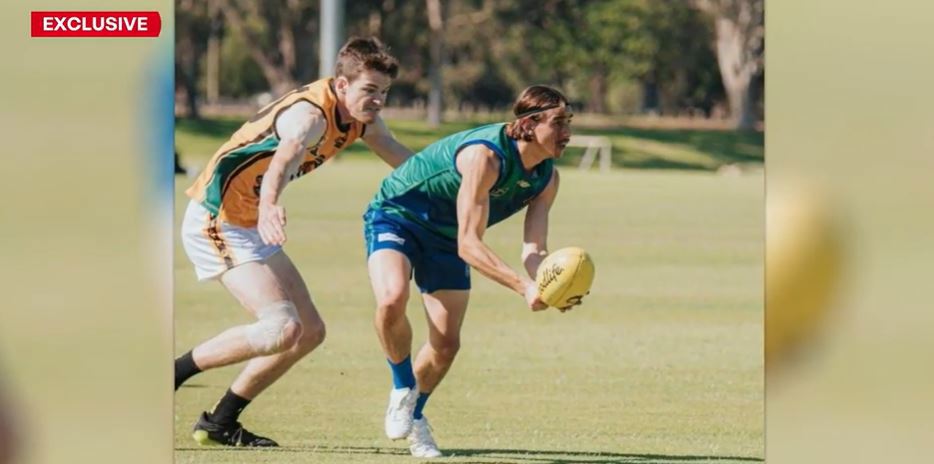
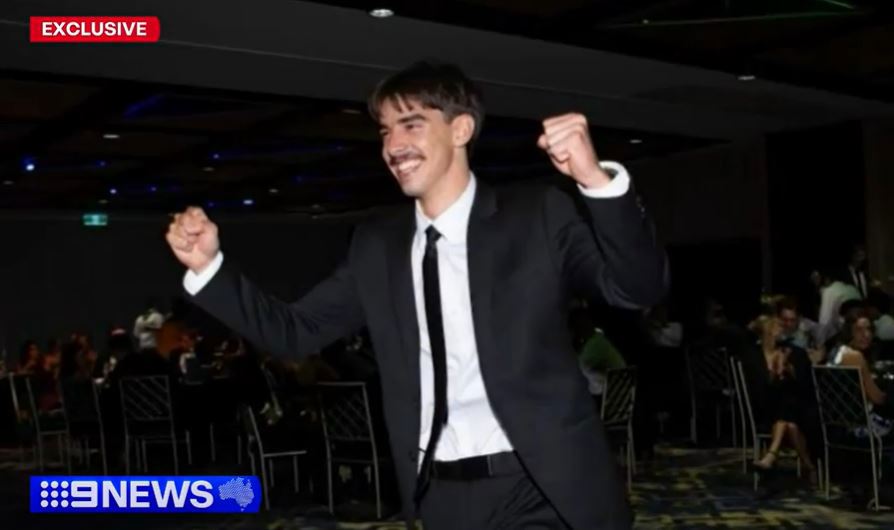
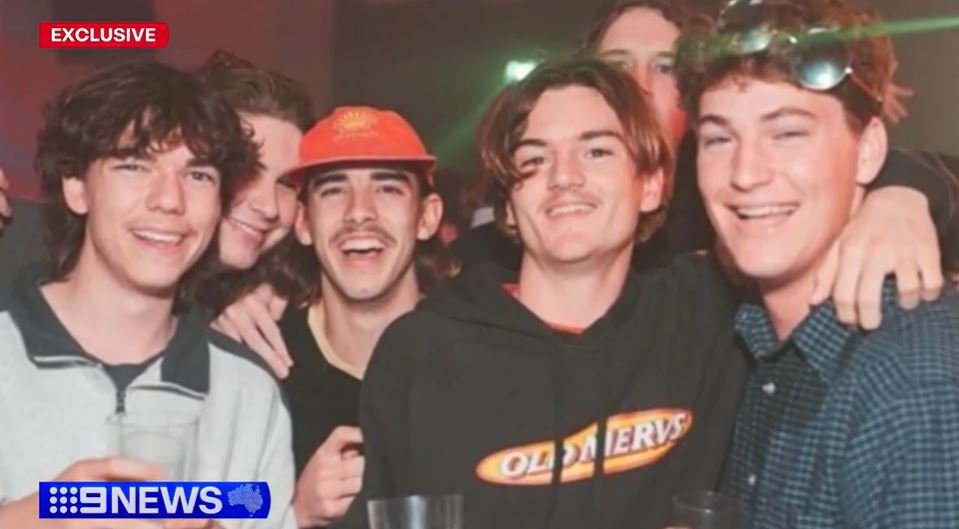
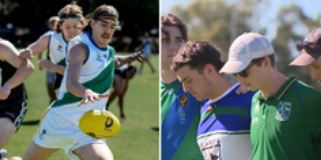
This would have been the 20-year-old's fourth year playing with the UWA footy club but instead, they a round held in his memory.
Stead's best friend Charlie Carrington-Jones said the round in his mate's honour was a no-brainer.
"[For] someone like Harry, it had to be done because he was just such a big person in this community and so many people loved him so much, including myself," Carrington-Jones told 9News.
Harry died a hero on Boxing Day last year, while volunteering to fight a fire on a neighbour's property near Esperance in the Great Southern region.
"To have a kid that's around 19, 20 years of age just put his hand up to help without even asking that holds a lot of weight with me," Jake Colvin, UWA Football Club President told 9News.
His mates today remembering him as someone committed to community and generous to a fault.
"Selfless, very generous. He was the perfect best friend in every way possible," Carrington-Jones said.
His absence on the field was felt by his teammates.
"[Harry was] not the tallest, not the biggest but he was lightning quick and never gave in at any point in any game," Carrington-Jones said.
"Always happy to be there, played with a smile on his face the whole time."
Sam West agreed, saying Stead brought "so much energy and so much passion" to the game.
"Whatever grade he played, he would've been very popular, made friends and the team would've been better off for having him for sure," Colvin said.
The club is rallying to give back for a man who gave so much to them.
"We're always here for the Stead family whatever they need and we just hope that they know that they have all the support of everyone at the UWA football club," Charlie said.
<p>Zamfara's Governor Lawal says his state needs more military formations from the federal government to stop insecurity consuming Northern Nigeria. </p>
<p>The post <a rel="nofollow" href="https://www.arise.tv/zamfara-under-siege-from-bandits-kidnappers-governor-lawal-cries-out/">Zamfara Under Siege From Bandits Kidnappers, Governor Lawal Cries Out </a> appeared first on <a rel="nofollow" href="https://www.arise.tv">Arise News</a>.</p>
<img src="https://www.mtlblog.com/media-library/canadian-money-and-a-calculator.jpg?id=56281537&width=2000&height=1500&coordinates=26%2C0%2C27%2C0"/><br/><br/><p><a href="https://www.mtlblog.com/tag/quebec-tax" target="_blank">Tax season</a> is creeping up fast, and if you're looking to maximize your <a href="https://www.mtlblog.com/cra-tax-return-2024-whats-new" target="_blank">2024 tax return</a>, there's one more move you might want to consider before it's too late — making an RRSP contribution. </p><p>The RRSP contribution deadline for the 2024 tax year is March 3, 2025, and any contributions you make by then could help lower your taxable income and boost your refund when you <a href="https://www.mtlblog.com/simplefile-cra-automatic-tax-filing-quebec" target="_blank">file your taxes this year</a>. </p><p>With the <a href="https://www.mtlblog.com/cra-netfile-free-tax-filing-online-quebec" target="_blank">Canada Revenue Agency</a> allowing tax deductions for eligible RRSP contributions, this could be a smart way to reduce what you owe on your income tax — or even score a bigger refund.</p><p>But how does an RRSP actually work, and how much should you contribute? If you're not entirely sure, <a href="https://www.mtlblog.com/cra-tax-tips-first-time-filing-students-newcomers" target="_blank">you're not alone</a>. Many Canadians are still figuring out the ins and outs of RRSPs — from contribution limits to tax benefits to the best times to contribute. </p><p>So, let's break it down in simple terms and answer some of the most common questions before the 2024 RRSP contribution deadline sneaks up on you.</p><h3>How do RRSPs work?</h3><br/><p>A Registered Retirement Savings Plan (RRSP) is a tax-deferred savings account that helps you save for your retirement while reducing your taxable income today. Any money you contribute to your RRSP is deducted from your taxable income for that year, which means you could pay less in taxes now. Plus, the money inside your RRSP grows tax-free until you withdraw it.</p><p>However, when you eventually withdraw from your RRSP, the amount you take out is taxed as income. The idea is that you'll be in a lower <a href="https://www.mtlblog.com/revenu-quebec-cra-income-tax-brackets-2025" target="_blank">tax bracket</a> by the time you go to withdraw from your RRSP because you won't be earning your working income anymore, so the tax you'll pay on it will be lower than it is now.</p><p><a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/registered-retirement-savings-plan-rrsp.html" target="_blank">More about RRSPs</a></p><h3>Are RRSP contributions tax deductible?</h3><br/><p>Yes! Any contributions you make to your RRSP before the RRSP contribution deadline can be deducted from your taxable income for that year when filing your tax return. This means you'll be taxed on a lower income, which can either reduce the amount you owe or increase your refund.</p><p>For example, if you earned $80,000 and contributed $10,000 to your RRSP, your taxable income would be reduced to $70,000 — meaning you'd pay taxes on that lower amount instead.</p><p>Keep in mind, though, that RRSP contributions aren't tax-<em>free</em>. You'll still have to pay tax on that money later when you withdraw it — you're just deferring the taxable income to later in life when (ideally) you'll be in a lower tax bracket.</p><p><a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/contributing-a-rrsp-prpp/claim-your-rrsp-prpp-contributions-on-your-tax-return.html" target="_blank">More about claiming RRSP contributions</a></p><h3>How much should I contribute to my RRSP?</h3><br/><p> Your RRSP contribution limit depends on your income. For 2024, the maximum amount you can contribute is 18% of your earned income from the previous year, up to a limit of $31,560.
</p><p> If you haven't used up your RRSP contribution room in past years, unused contribution room carries forward, meaning you could contribute more than this year's limit if you haven't maxed out in previous years. </p><p><a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/contributing-a-rrsp-prpp.html" target="_blank">More about RRSP contributions</a></p><h3>Where to find RRSP contribution limit</h3><br/><p>Your RRSP contribution limit — otherwise known as your "RRSP deduction limit," because it's the maximum amount you can deduct from your taxable income — can be found in your CRA My Account or on your latest Notice of Assessment.</p><p>If you don't have either of those, you can also call the CRA's automated <a href="https://www.canada.ca/en/revenue-agency/services/e-services/tax-information-phone-service-tips.html" target="_blank">Tax Information Phone Service (TIPS)</a> at 1-800-267-6999 or their Individual Tax Enquiries Line at 1-800-959-8281.</p><p><a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/contributing-a-rrsp-prpp.html" rel="noopener noreferrer" target="_blank">More about RRSP contribution limits</a></p><h3>When is the last day to contribute to an RRSP?</h3><br/><p>The RRSP contribution deadline for the 2024 tax season is<strong> <strong>March</strong></strong><strong> 3, 2025</strong>. Any contributions made between March 1, 2024, and March 3, 2025, can be claimed as a deduction on your 2024 tax return.</p><p>If you miss this deadline, don't panic! Your contribution will still go into your RRSP account, but you'll just have to wait until next year's tax return to claim the deduction.</p><h3>Does RRSP contribution room carry forward?</h3><br/><p>Yes! If you don't contribute the full amount you're allowed in a given year, your unused RRSP contribution room carries forward indefinitely. This means you can catch up on contributions in future years, which can be helpful if you expect to be in a higher tax bracket later on.</p><p>Keep in mind that if you make a withdrawal (other than under the Home Buyers' Plan or Lifelong Learning Plan), you won't get that contribution room back.</p><p><a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/contributing-a-rrsp-prpp/contributions-affect-your-rrsp-prpp-deduction-limit.html" target="_blank">More about RRSP contribution limits</a></p><h3>When can you withdraw from an RRSP?</h3><br/><p>You can withdraw from your RRSP at any time as long as your plan isn't locked in, but there's a catch — withdrawals are taxable as income in the year you take them out, and your financial institution will apply a withholding tax (basically a prepayment on the estimated income tax you'll owe) when you make a withdrawal.</p><p>The RRSP withholding tax rate depends on how much you withdraw. Here are the combined (federal and provincial) rates for Quebec:</p><ul><li>Up to $5,000: <strong>19%</strong></li><li>Over $5,000 and up to $15,000: <strong>24%</strong></li><li>Over $15,000: <strong>29%</strong></li></ul><p>However, there are exceptions! Under the <a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/what-home-buyers-plan.html" target="_blank">Home Buyers' Plan</a> (HBP) and <a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/lifelong-learning-plan.html" target="_blank">Lifelong Learning Plan</a> (LLP), you can withdraw funds without immediate tax penalties (including withholding tax), as long as you repay them over time.</p><p>By the end of the year you turn 71, if you still have money in your RRSP, you'll need to <a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/rrsp-options-when-you-turn-71.html" target="_blank">withdraw or transfer it</a>.</p><p><a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/making-withdrawals.html" target="_blank">More about RRSP withdrawals</a></p><h3>What is a spousal RRSP?</h3><br/><p>A spousal RRSP allows a higher-earning spouse to contribute to an RRSP in their partner's name. This allows the contributor to get a tax deduction now, while the withdrawals in retirement are taxed in the lower-income spouse's name, potentially reducing the couple's overall tax burden.</p><p><a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/rrsps-related-plans/setting-rrsp.html" target="_blank">More about spousal RRSPs</a></p><h3>RRSP vs TFSA: What's the difference?</h3><br/><p>An RRSP is tax-deferred — it's great for reducing your taxable income now, but withdrawals in retirement are taxed, including any interest your contributions earn over the years. </p><p>A Tax-Free Savings Account (TFSA), on the other hand, doesn't give you a tax deduction when you contribute, but withdrawals are completely tax-free. This means if you invest your TFSA and it grows, you won't need to pay income tax on the interest.</p><p>Both accounts are great options for long-term savings, but RRSPs are generally best if you're in a <a href="https://www.mtlblog.com/revenu-quebec-cra-income-tax-brackets-2025" target="_blank">high tax bracket</a> now and expect to be in a lower one when you withdraw the funds, while TFSAs are better if you want tax-free access to your savings anytime.</p><p><a href="https://www.canada.ca/en/revenue-agency/services/tax/individuals/topics/tax-free-savings-account.html" target="_blank">More about TFSAs</a></p><p class="">With the RRSP deadline right around the corner, now's the time to check your contribution limit, crunch the numbers and decide if making a last-minute contribution is right for you. </p><p>Whether you're looking to maximize your tax refund or just get ahead on retirement savings, an RRSP could be a valuable tool in helping you achieve your financial goals — just don't wait too long to decide!</p><em>Love this? Check out our <a href="https://www.mtlblog.com/notices/" target="_blank">MTL Blog noticeboard</a> for details on jobs, benefits, travel info and more!</em>
<em>AI tools may have been used to support the creation or distribution of this content; however, it has been carefully edited and fact-checked by a member of MTL Blog's Editorial team. For more information on our use of AI, please visit our <a href="https://www.mtlblog.com/editorial-standards" target="_blank">Editorial Standards page</a>.</em>
Firefighters battling the Jasper-area wildfire have finally reached the Maligne Lake region, finding a mixture of destroyed and spared structures. Read More Own a fractional…