In our opinion, transferable points programs like Chase Ultimate Rewards, Citi ThankYou Rewards, and Amex Membership Rewards are the most valuable points (or “miles”) to accumulate. These points can often be used to book discounted travel and, even better, transferred strategically to airline and hotel programs when valuable awards are available.
In some cases, you can supercharge your points-earning by combining the benefits of multiple cards. For example, you can use one card to earn more points at gas stations, another to earn more at grocery stores, and another to get the most value when redeeming those points.
In this post, we’re looking at the best card combos from American Express, Bilt, Capital One, Chase, Citi, and Wells Fargo. We chose these banks because each offers multiple cards with different earning rates andpoints that transfer to airline and hotel programs. That matters because transferring points to book high-value awards is the best way to get outsized value from your rewards.
Listed below are our favorite transferable points combos: credit cards that, like peanut butter and jelly, are better together. With these cards, you can maximize point earnings and get the best value from your points. It has been completely updated for 2026 and now includes Bilt.
Amex Membership Rewards
American Express Gold Card + Blue Business Plus
Total annual fee: $325
4X at US supermarkets (Gold – max $25K/year)
4X at restaurants (Gold – max $50K/year)
3X airfare booked directly with an airline or through amextravel.com (Gold)
2X everywhere else (Blue Business Plus – max 50K/year)
FM Mini Review: This card offers an awesome return on US supermarket and worldwide dining spend, putting it at or near the top-of-class in both categories. Dining credits and Uber / Uber Eats credits go a long way towards reducing the sting of this card’s annual fee.
$325 Annual Fee
Earning rate: 5X points on prepaid hotel stays booked on amextravel.com ✦ 4x points at US Supermarkets (up to $25K in purchases, then 1x) ✦ 4x at restaurants worldwide (up to $50k in purchases, then 1x) ✦ 3X points for flights booked with airlines or on amextravel.com ✦ 1X points on other purchases. Terms apply.
In our opinion, transferable points programs like Chase Ultimate Rewards, Citi ThankYou Rewards, and Amex Membership Rewards are the most valuable points (or “miles”) to accumulate. These points can often be used to book discounted travel and, even better, transferred strategically to airline and hotel programs when valuable awards are available.
In some cases, you can supercharge your points-earning by combining the benefits of multiple cards. For example, you can use one card to earn more points at gas stations, another to earn more at grocery stores, and another to get the most value when redeeming those points.
In this post, we’re looking at the best card combos from American Express, Bilt, Capital One, Chase, Citi, and Wells Fargo. We chose these banks because each offers multiple cards with different earning rates andpoints that transfer to airline and hotel programs. That matters because transferring points to book high-value awards is the best way to get outsized value from your rewards.
Listed below are our favorite transferable points combos: credit cards that, like peanut butter and jelly, are better together. With these cards, you can maximize point earnings and get the best value from your points. It has been completely updated for 2026 and now includes Bilt.
Amex Membership Rewards
American Express Gold Card + Blue Business Plus
Total annual fee: $325
4X at US supermarkets (Gold – max $25K/year)
4X at restaurants (Gold – max $50K/year)
3X airfare booked directly with an airline or through amextravel.com (Gold)
2X everywhere else (Blue Business Plus – max 50K/year)
FM Mini Review: This card offers an awesome return on US supermarket and worldwide dining spend, putting it at or near the top-of-class in both categories. Dining credits and Uber / Uber Eats credits go a long way towards reducing the sting of this card’s annual fee.
$325 Annual Fee
Earning rate: 5X points on prepaid hotel stays booked on amextravel.com ✦ 4x points at US Supermarkets (up to $25K in purchases, then 1x) ✦ 4x at restaurants worldwide (up to $50k in purchases, then 1x) ✦ 3X points for flights booked with airlines or on amextravel.com ✦ 1X points on other purchases. Terms apply.
In our opinion, transferable points programs like Chase Ultimate Rewards, Citi ThankYou Rewards, and Amex Membership Rewards are the most valuable points (or “miles”) to accumulate. These points can often be used to book discounted travel and, even better, transferred strategically to airline and hotel programs when valuable awards are available.
In some cases, you can supercharge your points-earning by combining the benefits of multiple cards. For example, you can use one card to earn more points at gas stations, another to earn more at grocery stores, and another to get the most value when redeeming those points.
In this post, we’re looking at the best card combos from American Express, Bilt, Capital One, Chase, Citi, and Wells Fargo. We chose these banks because each offers multiple cards with different earning rates andpoints that transfer to airline and hotel programs. That matters because transferring points to book high-value awards is the best way to get outsized value from your rewards.
Listed below are our favorite transferable points combos: credit cards that, like peanut butter and jelly, are better together. With these cards, you can maximize point earnings and get the best value from your points. It has been completely updated for 2026 and now includes Bilt.
Amex Membership Rewards
American Express Gold Card + Blue Business Plus
Total annual fee: $325
4X at US supermarkets (Gold – max $25K/year)
4X at restaurants (Gold – max $50K/year)
3X airfare booked directly with an airline or through amextravel.com (Gold)
2X everywhere else (Blue Business Plus – max 50K/year)
FM Mini Review: This card offers an awesome return on US supermarket and worldwide dining spend, putting it at or near the top-of-class in both categories. Dining credits and Uber / Uber Eats credits go a long way towards reducing the sting of this card’s annual fee.
$325 Annual Fee
Earning rate: 5X points on prepaid hotel stays booked on amextravel.com ✦ 4x points at US Supermarkets (up to $25K in purchases, then 1x) ✦ 4x at restaurants worldwide (up to $50k in purchases, then 1x) ✦ 3X points for flights booked with airlines or on amextravel.com ✦ 1X points on other purchases. Terms apply.
In our opinion, transferable points programs like Chase Ultimate Rewards, Citi ThankYou Rewards, and Amex Membership Rewards are the most valuable points (or “miles”) to accumulate. These points can often be used to book discounted travel and, even better, transferred strategically to airline and hotel programs when valuable awards are available.
In some cases, you can supercharge your points-earning by combining the benefits of multiple cards. For example, you can use one card to earn more points at gas stations, another to earn more at grocery stores, and another to get the most value when redeeming those points.
In this post, we’re looking at the best card combos from American Express, Bilt, Capital One, Chase, Citi, and Wells Fargo. We chose these banks because each offers multiple cards with different earning rates andpoints that transfer to airline and hotel programs. That matters because transferring points to book high-value awards is the best way to get outsized value from your rewards.
Listed below are our favorite transferable points combos: credit cards that, like peanut butter and jelly, are better together. With these cards, you can maximize point earnings and get the best value from your points. It has been completely updated for 2026 and now includes Bilt.
Amex Membership Rewards
American Express Gold Card + Blue Business Plus
Total annual fee: $325
4X at US supermarkets (Gold – max $25K/year)
4X at restaurants (Gold – max $50K/year)
3X airfare booked directly with an airline or through amextravel.com (Gold)
2X everywhere else (Blue Business Plus – max 50K/year)
FM Mini Review: This card offers an awesome return on US supermarket and worldwide dining spend, putting it at or near the top-of-class in both categories. Dining credits and Uber / Uber Eats credits go a long way towards reducing the sting of this card’s annual fee.
$325 Annual Fee
Earning rate: 5X points on prepaid hotel stays booked on amextravel.com ✦ 4x points at US Supermarkets (up to $25K in purchases, then 1x) ✦ 4x at restaurants worldwide (up to $50k in purchases, then 1x) ✦ 3X points for flights booked with airlines or on amextravel.com ✦ 1X points on other purchases. Terms apply.
Card Info: Amex Pay Over Time Card issued by Amex. This card has no foreign currency conversion fees.
Noteworthy perks: Up to $10 in statement credits monthly with participating dining partners (Grubhub (including Seamless), Buffalo Wild Wings, Five Guys, The Cheesecake Factory, and Wonder) ✦ $10 monthly Uber or Uber Eats credit (use it or lose it each month – must select Amex card as payment method to redeem) ✦ Up to $7 monthly Dunkin’ credit – enrollment required ✦ Up to $50 twice-annual Resy credit ✦ $100 hotel credit on qualifying charges on stays of 2 nights or longer, plus a room upgrade upon arrival, if available with The Hotel Collection at americanexpress.com/hc ✦ Complimentary Hertz Five Star® Status ✦ Enrollment required for select benefits.
FM Mini Review: 2X rewards for all eligible purchases (up to $50K per year) with no annual fee makes this card a winner. Click here for our complete card review
No Annual Fee
Earning rate: 2X Membership Rewards points on all eligible purchases, up to $50K spend per calendar year (then 1X thereafter). Terms apply. (Rates & Fees)
Card Info: Amex Credit Card issued by Amex. This card imposes foreign transaction fees.
Combo details: Amex automatically pools all your Membership Rewards points, even if you earned them with different cards. While you can’t move points from one person to another, you can transfer points to a friend’s airline or hotel program account if they are an authorized user (or employee) on one of your accounts.
Why it’s great: This combination delivers terrific earning potential (2X to 4X everywhere in the US!) and lets you transfer points to Amex’s valuable transfer Partners. Traditionally, Amex has offered more transfer bonuses than other issuers, though that has changed over the last year or so. For those who can use the Gold card’s $10/month dining, 2x$50 Resy credits, and $10/month Uber/Uber Eats credits, the $325 annual fee becomes easier to justify.
Shortcomings: Yearly limits and foreign travel. The Gold card’s 4X grocery bonus is capped at $25K in annual spend and is limited to stores in the US, while the 4X at restaurants is worldwide but capped at $50K/year. The Blue Business Plus card charges foreign transaction fees and limits the 2X bonus to $50K per year, making this a less desirable combo for those who spend big or for those looking for great rewards on spending outside of the United States…and since Amex often isn’t accepted outside of the United States, you’ll want a backup Visa or Mastercard when traveling anyway. This combo also requires a business card to earn 2x everywhere.
Add-on: There are several worthwhile cards to consider adding to this combo:
The Platinum Card® offers a compelling lineup of perks and boosts flight earnings to 5X. Unfortunately, it also adds an $895 annual fee.
Also worth looking at is the Schwab Platinum Card, which has many similar perks to the Business Platinum and lets you cash out points at 1.1 cents each (1 million points/year max).
+1X on up to $50K in purchases using accelerators ($25K on each card)
Double rewards on the first of the month (1,000 bonus points max)
Perks include: earn rewards on housing payments, earn 4% Bilt Cash per dollar, which you can redeem toward housing payments or credits, 2 x $200 hotel credit per year *this will change for cards approved 1/1/27 or later – read more here*
Earning rate: 4% Bilt Cash on everyday purchases if you choose Bilt Cash rather than housing-only rewards + 3X points on dining or grocery (Limit $25K per year for grocery) ✦ 2X points on travel ✦ 1X points on everyday purchases ✦ 0.5X-1.25X points on rent & mortgage payments (if Housing-Only Earnings selected) ✦ 1X points on rent & mortgage payments when redeeming Bilt Cash (if Bilt Cash earning option selected)
Card Info: Mastercard World Elite issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ Up to $100 in Bilt Travel hotel credits ($50 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments
Card Info: Mastercard World Legend issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $200 Bilt Cash annually ✦ Up to $400 in Bilt Travel hotel credits ($200 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments ✦ Priority Pass (excludes restaurants)
Combo details: First off, Bilt only lets you have one Bilt card, so this combo is only possible if you have a 2nd player in the household that can add you as an authorized user (AU) to the second card. Bilt is unique in that it lets AU cards earn points and Bilt Cash to the AU’s account, so you can capture the earning categories (and accelerators) on both, but it also adds an additional fee of $50 for the Obsidian or $95 for the Palladium.
Why it’s great: This is another combo that offers excellent earning potential (2X to 4X everywhere), and Bilt has what most folks consider the best portfolio of transfer partners. It offers several 50%-100% Rent Day transfer bonuses per year that can deliver incredible value when transferring points. Using accelerators turns the Palladium card into a 3X everywhere earner, or even more if you’re also earning points on housing payments.
Shortcomings: First, you need two people to do it. Bilt doesn’t allow one person to be the primary cardholder on two cards. In addition, unlike many premium cards, there aren’t many included coupons, outside of 2 X $200 hotel credits on the Palladium and a $50 credit on the Obsidian, all of which require a two-night minimum and booking through Bilt’s travel portal. The earnings are great, but don’t forget that you’re still paying $600+ per year for them without the clear offsets of other cards. Starting 1/1/27, Bilt will lose 1:1 access to Hyatt, even with the Palladium card, which will be a big blow to the partner portfolio. Lastly, a third version of Bilt will take effect on January 1st, which represents a significant hit to earning power for folks who don’t earn points on housing payments.
Variation: Instead of incorporating the Obsidian card, you could use one Palladium card with an authorized user card that earns to the primary account. That setup would cost $590/year, but give you a total of $50K worth of 3X everywhere via accelerators. A downside is that AU card spend wouldn’t count toward elite status for the primary cardholder.
FM Mini Review: This card offers annual rebates that easily mitigate the fee for those who travel often. The card earns 2 miles per dollar on most purchases just like the Capital One Venture Rewards card, which are worth exactly 1 cent each toward travel. This makes the return on most spend similar to a 2% cash back card (though in this case you must redeem your miles to offset travel in order to get 1 cent per mile). One huge advantage over cash back: Capital One allows transfering their miles to airline miles & hotel points. Click here for our complete card review
$395 Annual Fee
Earning rate: 10X miles on hotels and rental cars booked via Capital One Travel ✦ 5X miles on flights and vacation rentals booked via Capital One travel ✦ 5X miles on Capital One Entertainment ✦ 2X miles everywhere else
Card Info: Visa Infinite issued by CapOne. This card has no foreign currency conversion fees.
Noteworthy perks: $300 annual credit for bookings made through Capital One Travel ✦ 10,000 bonus miles each year starting at first anniversary ✦ Up to $120 application fee credit for Global Entry or TSA PreCheck® ✦ Access to Capital One Lounge and Landing locations ✦ Priority Pass membership (participating lounges only) after enrollment ✦ Cell phone insurance ✦ Trip insurance ✦ Primary CDW coverage ✦ Redeem miles for travel at value of 1 cent per mile ✦ Transfer Miles to airline miles & hotel points
Earning rate: 8% cash back on Capital One Entertainment purchases ✦ 5% on hotels, vacation rentals, and rental cars booked via Capital One Travel (terms apply) ✦ 3% on dining, entertainment, select streaming services, and purchases at grocery stores (excluding superstores like Walmart® and Target®) ✦ 1% everywhere else
Base: 1%
Portal Hotels: 5%
Grocery: 3%
Dine: 3%
Card Info: Mastercard issued by CapOne. This card has no foreign currency conversion fees.
Combo details: Even though the Venture X has a $395 annual fee, you could consider this combo “almost free” after rebates, since it offers $300 in yearly Capital One Travel rebates plus 10K points each card anniversary, which together more than offset the annual fee. The fee-free Savor Cash Rewards adds 3x grocery, dining, and entertainment to the already strong 2x everywhere earnings offered by Venture X. Capital One lets you move cash back rewards to a “miles” card so that they then become transferable to partners. This allows you to earn 3% cash back with the Savor card and then convert that to “miles” by moving it to the Venture X card, unlocking better value by transferring to partners for high-value awards. You can also freely move points to anyone, so you don’t need more than one Venture X card in the family to make this combo work.
Why it’s great: Outstanding earnings with a “free after rebate” annual fee; this is the only combo that offers the same great earnings internationally with no foreign transaction fees. The Venture X provides excellent features such as cell phone protection, airport lounge access, and more. Capital One also offers arguably the best collection of card-linked offers. Additionally, Capital One is the only bank that has largely eschewed the stratospheric annual-fee coupon book for an ultra-premium card. It offers solid value without the mental load.
Shortcomings: The only way to get better than 1 cent per “Mile” value is by transferring to airline and hotel partners. Fewer opportunities for multiple, blingy welcome offers than Chase or Amex. Transfer partner portfolio lags behind Amex, Bilt, Citi, and Chase.
Variations:
Swap Venture X for Venture Rewards: Lower the annual fee to $95 per year with the Venture Rewards card instead of Venture X. Both offer 2x everywhere earnings, no foreign transaction fees, and the ability to transfer to airline and hotel partners. However, the Venture Rewards card doesn’t offer annual rebates that offset the annual fee and doesn’t offer lounge access.
Make it fee-free: You can cobble together a decent combo with no annual fees (and still have no foreign transaction fees). Start with the Savor for 3x grocery, dining, and entertainment, and then add the fee-free Quicksilver card to get 1.5x everywhere else, and then move all that cash back to the fee-free VentureOne Rewards card in order to transfer “Miles” to airline and hotel partners.
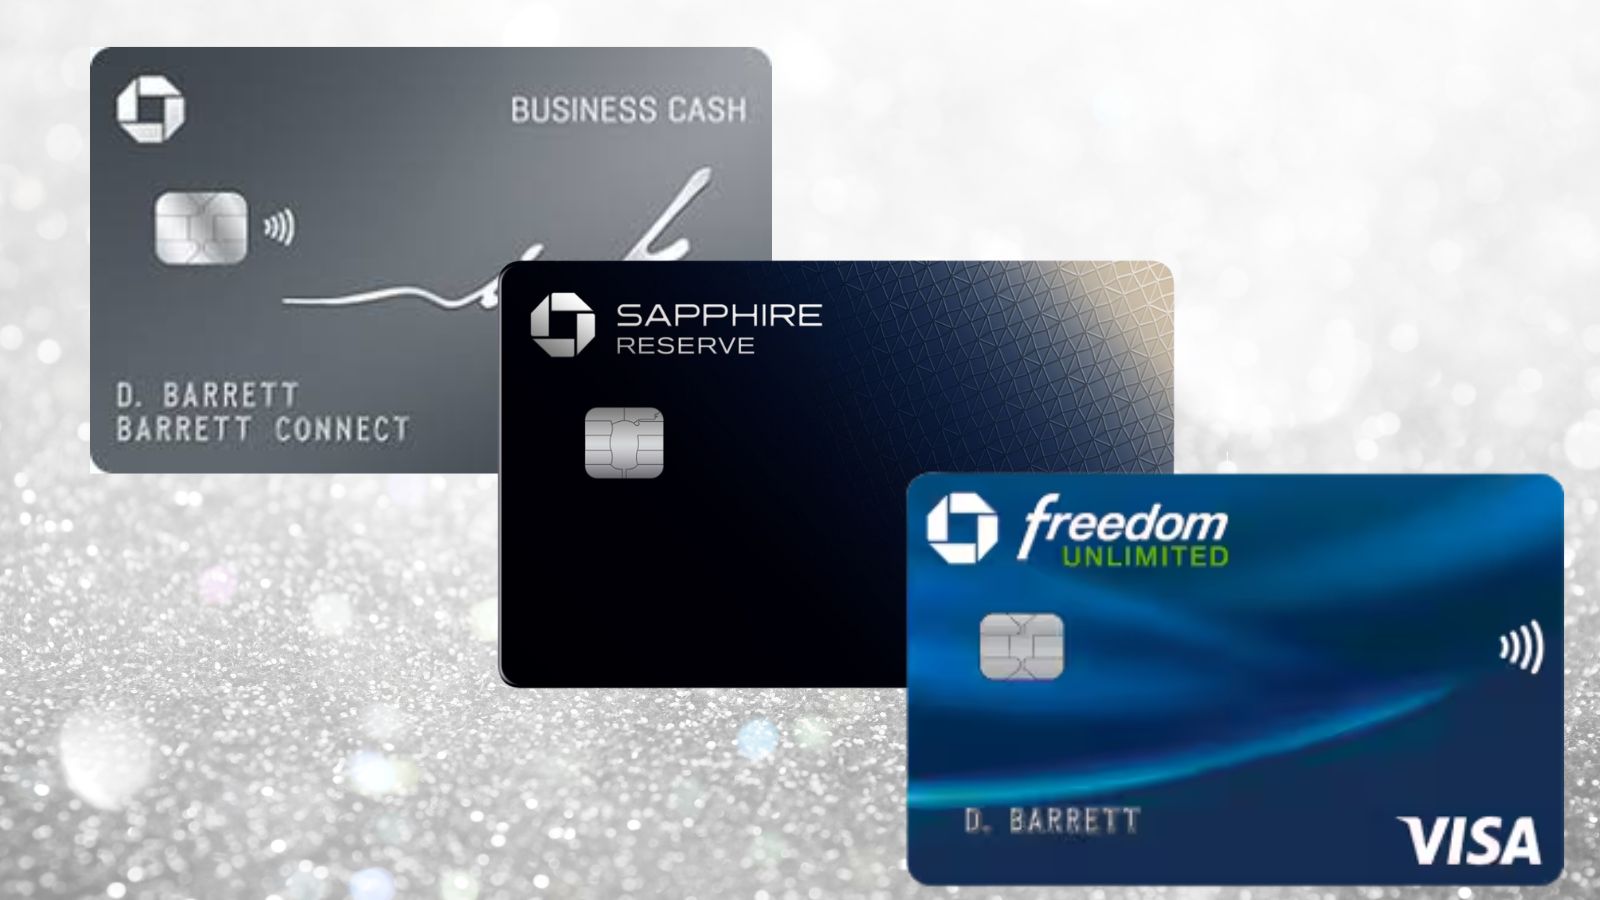
4X flights and hotels booked directly (Sapphire Reserve)
3X dining (Sapphire Reserve)
3X drug store (Freedom Unlimited)
2X gas stations (Ink Cash)
1.5X everywhere else (Freedom Unlimited)
Perks include 1:1 transfers to Hyatt, lounge access, up to $300 in annual travel rebates, up to $300 in annual dining credits, up to $300 in annual StubHub credits, up to $500 in annual The Edit credits, no foreign transaction fees, and excellent travel protections.
FM Mini Review: Good all-around card for frequent traveler. Best when paired with no annual fee Chase Freedom Flex, Freedom Unlimited & Chase Ink Cash cards. Click here for our complete card review
$795 Annual Fee
Earning rate: 8X Chase Travel℠ ✦ 4X flights and hotels booked direct ✦ 3X Dining ✦ 5X Lyft (through September 2027)
Card Info: Visa Infinite issued by Chase. This card has no foreign currency conversion fees.
Big spend bonus: After spending $75,000 each calendar year, get the following benefits: IHG One Rewards Diamond Elite Status ✦ World of Hyatt Explorist Status ✦ Southwest Airlines A-List Status ✦ $500 Southwest Airlines credit when booked through Chase Travel ✦ $250 credit to The Shops at Chase
Noteworthy perks: $300 Annual Travel Credit ✦ Transfer points to airline & hotel partners ✦ Up to $500 The Edit credit annually ($250 twice per calendar year) ✦ Up to $300 Dining credit through Sapphire Reserve Exclusive Tables ($150 January to June and again July to December) ✦ Complimentary Apple TV and Apple Music for a minimum of one year when activated by 6/22/27 ✦ Up to $300 in StubHub credits ($150 January to June and again July to December) ✦ Points worth up to 2 cents each towards qualified bookings through Chase Travel ✦ Primary auto rental coverage ✦ Priority Pass Select lounge access ✦ Access Sapphire Lounges for yourself and 2 guests for free ✦ Access select Air Canada Maple Leaf lounges when flying Star Alliance ✦ Up to $120 Global Entry or TSA PreCheck® or NEXUS Application Fee Statement Credit ✦ IHG One Rewards Platinum status through 12/31/27 ✦ Free DoorDash DashPass through 2027 ✦ Two promos of $10 off each month on non-restaurant orders from DoorDash ✦ $15 off restaurant order each month from DoorDash ✦ $10 monthly Lyft credit
FM Mini Review: Great for 3X categories and 1.5X everywhere else. Excellent companion card to Sapphire Reserve®, Sapphire Preferred®, or Ink Business Preferred®. Click here for our complete card review
No Annual Fee
Earning rate: 5X travel booked through Chase Travel℠ ✦ 3X dining ✦ 3X drugstores ✦ 2% cash back total on qualifying Lyft products and services purchased through the Lyft mobile application through 09/30/2027 ✦ 1.5X everywhere else
FM Mini Review: This one should be in everyone’s wallet. Incredible welcome offer for a no-annual-fee card. Great card for 5X categories. Excellent companion card to Sapphire Reserve, Sapphire Preferred, or Ink Business Preferred. Click here for our complete card review
No Annual Fee
Earning rate: 5X office supplies and cellular/landline/cable (on up to $25,000 in total purchases in 5X categories annually) ✦ 2X on the first $25K in combined purchases at gas stations and restaurants each cardmember year ✦ 5x Lyft through September 2027
Card Info: Visa Signature Business issued by Chase. This card imposes foreign transaction fees.
Noteworthy perks: Complimentary Instacart+ for 3 months (must activate by 12/31/27) ✦ $20 monthly Instacart credit ✦ $10 off each month on one non-restaurant order from DoorDash
Combo details: Many of Chase’s no-annual-fee cards are advertised as cashback cards, but they actually earn Ultimate Rewards points. Once you have points in one of these accounts, you can move them to your Sapphire Reserve account to make them transferable. Chase lets you move points to another person in the same household, so it makes sense for a couple to earn points across a variety of Ultimate Rewards cards and then move them all to a single Sapphire Reserve account. The Sapphire Reserve card provides three ways to get good value from your points: 1) transfer to airline and hotel partners for high-value awards; 2) book through Chase Travel℠ using points boosts at a value of up to 2 cents per point; and 3) erase statement charges at 1.25 cents per point value against current Pay Yourself Back categories (see this post for details).
Why it’s great: This is the only combo listed here that offers 1:1 transfers to Hyatt, which can translate into incredible value. Points are also worth up to 2 cents each toward select bookings via Chase Travel℠, but only on bookings with points boosts, which is a limited subset. You can sometimes get even better value by transferring points to Chase’s high-value travel partners. The Sapphire Reserve offers excellent automatic travel protections…provided that you don’t live in New York.
Shortcomings: Requires three cards instead of two. The Sapphire Reserve card costs $795 per year, and the value you get from the array of rebates will vary from person to person. The Freedom Unlimited and Ink Business Cash cards charge foreign exchange fees, so you’ll want to use your Sapphire Reserve card when traveling outside of the US, at which point you’re only earning 1X everywhere. This is also the only combo in this roundup that doesn’t offer a standard grocery bonus and doesn’t have a 2X everywhere option.
Add-on: Consider adding the no-fee Chase Freedom Flex card, which offers rotating 5X categories.
Variation: You can lower annual fees to $95 per year by replacing the Sapphire Reserve with either the Sapphire Preferred® or the Ink Business Preferred®. Both let you transfer points to travel hotel and airline partners and still offer the expansive “travel” category bonus the Sapphire Reserve lost in the 2025 refresh. However, both also have a reduced 4:3 transfer ratio to World of Hyatt
FM Mini Review: Very strong earnings for spend. Excellent bonus categories. Points transferable to select airlines. Recommend pairing this card with Citi Double Cash Click here for our complete card review
$95 Annual Fee
Earning rate: 10X hotels, car rentals, and attractions booked through Citi Travel℠ ✦ 3X grocery ✦ 3X dining ✦ 3X gas stations & EV charging ✦ 3X flights, hotels, travel agencies ✦ 1x everywhere else
Card Info: Mastercard World Elite issued by Citi. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $100 Annual Hotel Savings Benefit ($100 off a $500+ hotel stay, excluding taxes and fees, when booked through Citi Travel) ✦ Travel protections
FM Mini Review: 2X rewards for all spend with no annual fee makes this card a winner. Earn 2X everywhere and redeem for the equivalent of 2% cash back or 2X ThankYou points. Pair with the Premier or Prestige card to make points transferrable to airlines. Click here for our complete card review
No Annual Fee
Earning rate: 2% cash back everywhere ✦ Earn 3% total cash back on hotel, car rentals, and attractions booked on Citi Travel℠ Portal
Combo details: Citi lets you pool ThankYou points across your cards to get the best possible redemption value. You can also transfer points to anyone, but once you do, you must use them within 90 days, or they’ll expire.
Why it’s great: Excellent point earnings, especially for a combo with a total $95 annual fee (the Strata Premier card costs $95 per year, while the other cards are free). Both provide free authorized user cards. Travel partners are an intriguing mix of airlines and hotels, with unique 1:1 options like American AAdvantage, EVA Air, and Japan Airlines.
Shortcomings: Citi no longer allows you to share points with other cardholders. It has also effectively discontinued options for earning more than 1 cent per point, outside of transferring points to partners, and has tanked the transfer ratios of its most valuable lodging partners. Earlier this year, Citi stopped accepting applications for the Custom Cash, removing the only option for 5X earning. Lastly, Citi offers somewhat lackluster travel protections compared with some of the other card combinations listed here.
FM Mini Review: This card offers a competitive flat 2% back on purchases and includes good cell phone insurance for a no annual fee card (up to $600 in protection with just a $25 deductible). Pair with a Wells Fargo Autograph or Autograph Journey card to make the rewards transferable to airline and hotel partners.
Card Info: Visa issued by Wells. This card imposes foreign transaction fees.
Combo details: Like Capital One, Wells Fargo lets you transfer cash rewards to the Autograph Journey card at a 1:1 ratio. This lets you transfer rewards earned on both cards to travel partners. Wells Fargo also lets you transfer as little as one point to a partner program, making it easy to avoid leaving orphaned rewards in a partner account.
Why it’s great: These cards offer excellent points earnings for a total $95 annual fee, not including the $50 yearly airfare credit that comes with the Autograph Journey. 5x at hotels is another unique feature of this combo. The cards offer decent travel and purchase protections, plus very good cell phone insurance.
Shortcomings: A big downside is that this combo has no grocery bonus, so the best that you can do is 2x with the Active Cash. While the Autograph Journey doesn’t have foreign transaction fees, the other two cards do, making it a one-card system when traveling (with a 1X floor). Wells Fargo’s collection of transfer partners is undoubtedly the weakest of all the programs we’re comparing. Currently, there are only eight, including the different Avios programs that effectively function as one. The only domestic airline is JetBlue, and the only hotel partners are Choice Privileges and Wyndham Rewards (both with an excellent 1:2 transfer ratio). If Wells Fargo can beef up its partner list to rival the other issuers listed here, this will become a much more delectable combo. Like Amex and Citibank, Wells Fargo no longer allows you to transfer points to other users.
Which is the best credit card combo?
So, which combo is best? It’s difficult to answer that question without understanding the needs of the person who’s asking. Any of these combos may be best for you, depending on your tolerance for annual fees, your spending patterns, and how you’re likely to use your rewards. Picking one “best” is harder than it’s ever been.
Bilt offers excellent value and earning potential, but you need a second participant to use multiple cards, and the high annual fees will be increasingly intrusive for those who sign up after 1/1/27 and don’t have a housing payment. Because one person can’t have more than one card, it’s hard to call this the best combo, and you can get plenty of value from the Palladium or Obsidian card on their own, especially if you have a monthly housing payment.
Getting 1:1 transfers to Hyatt is getting increasingly difficult…and expensive. With Bilt moving to a 4:3 ratio to Hyatt, the Chase combo becomes the only way to retain 1:1 Hyatt transfers, something that can be extended to additional household players because of Chase’s transfer policy. However, the $795 annual fee is the highest on this list, and it requires you to get significant value from the various coupons. That said, it’s less than $200 more than the Bilt “combo,” which is pretty amazing given how many more credits the Chase version offers.
I love the Citi combo because it offers probably the best all-around card listed here for category bonuses: the Strata Premier, which earns 3x at gas stations, grocery stores, restaurants, AND travel – all on one card. I can give player 2 (my wife) a Double Cash and the Strata Premier and know that she’s earning 2x everywhere and 3x at most of the places that she spends money. Citi has a great mix of airline partners, including American Airlines, EVA Air, and Japan Airlines. However, lodging has taken a big hit: Preferred Hotels is now 1:2, Choice is 1:1.5, and Leading Hotels of the World offers 25% more value through Amex (4:1 vs 5:1). Additionally, closing the Custom Cash to new applicants removes the ability to earn 5X in the category of your choice on $500/month in purchases.
For many folks, the Capital One Venture X + Savor combo will be best, because it only requires holding two cards and offers substantial rewards in popular categories (3x grocery, dining, and entertainment); strong rewards on all other spend (2x); no foreign transaction fees; and ultra-premium card features (airport lounge access and travel protections) all for “free after rebate” (spend $395, but get back $300 in travel credits and 10K points each year).
Final Thoughts
I have and use almost all of the cards listed above, but if I had to pick one “combo,” it would probably be Chase, surprisingly enough. Capital One would come in second by a hair. I’ve had great luck combining points boosts with my Edit credits to get excellent value; add in 1:1 transfers to Hyatt, and there are reasonable paths to get good value for both lodging and flights. I also like the earning potential, travel protections, and lounge access.
That’s a huge change from last year, when I had Citi number one, but after downgrading its lodging transfers, removing the Custom Cash card, and nixing the ability to move points to other cardholders, it’s lost enough appeal to no longer reign supreme. I also love my Bilt Palladium card and plan to keep it as long as I can keep the current earning regime, but as a combo, the need to have a second player, pay over $600 in annual fees, and accept sub-1:1 Hyatt transfers makes it tough to pick.
All of the combos listed here could be best, depending on the individual, and I could make an argument for any of them. In reality, I use a “multi-combo combo,” that combines several of them; that may be the best choice for others as well. If you do expand into multiple currencies, be careful to keep an eye on those annual fees to make sure you’re getting enough value out of your wallet to justify the expense.
Card Info: Amex Pay Over Time Card issued by Amex. This card has no foreign currency conversion fees.
Noteworthy perks: Up to $10 in statement credits monthly with participating dining partners (Grubhub (including Seamless), Buffalo Wild Wings, Five Guys, The Cheesecake Factory, and Wonder) ✦ $10 monthly Uber or Uber Eats credit (use it or lose it each month – must select Amex card as payment method to redeem) ✦ Up to $7 monthly Dunkin’ credit – enrollment required ✦ Up to $50 twice-annual Resy credit ✦ $100 hotel credit on qualifying charges on stays of 2 nights or longer, plus a room upgrade upon arrival, if available with The Hotel Collection at americanexpress.com/hc ✦ Complimentary Hertz Five Star® Status ✦ Enrollment required for select benefits.
FM Mini Review: 2X rewards for all eligible purchases (up to $50K per year) with no annual fee makes this card a winner. Click here for our complete card review
No Annual Fee
Earning rate: 2X Membership Rewards points on all eligible purchases, up to $50K spend per calendar year (then 1X thereafter). Terms apply. (Rates & Fees)
Card Info: Amex Credit Card issued by Amex. This card imposes foreign transaction fees.
Combo details: Amex automatically pools all your Membership Rewards points, even if you earned them with different cards. While you can’t move points from one person to another, you can transfer points to a friend’s airline or hotel program account if they are an authorized user (or employee) on one of your accounts.
Why it’s great: This combination delivers terrific earning potential (2X to 4X everywhere in the US!) and lets you transfer points to Amex’s valuable transfer Partners. Traditionally, Amex has offered more transfer bonuses than other issuers, though that has changed over the last year or so. For those who can use the Gold card’s $10/month dining, 2x$50 Resy credits, and $10/month Uber/Uber Eats credits, the $325 annual fee becomes easier to justify.
Shortcomings: Yearly limits and foreign travel. The Gold card’s 4X grocery bonus is capped at $25K in annual spend and is limited to stores in the US, while the 4X at restaurants is worldwide but capped at $50K/year. The Blue Business Plus card charges foreign transaction fees and limits the 2X bonus to $50K per year, making this a less desirable combo for those who spend big or for those looking for great rewards on spending outside of the United States…and since Amex often isn’t accepted outside of the United States, you’ll want a backup Visa or Mastercard when traveling anyway. This combo also requires a business card to earn 2x everywhere.
Add-on: There are several worthwhile cards to consider adding to this combo:
The Platinum Card® offers a compelling lineup of perks and boosts flight earnings to 5X. Unfortunately, it also adds an $895 annual fee.
Also worth looking at is the Schwab Platinum Card, which has many similar perks to the Business Platinum and lets you cash out points at 1.1 cents each (1 million points/year max).
+1X on up to $50K in purchases using accelerators ($25K on each card)
Double rewards on the first of the month (1,000 bonus points max)
Perks include: earn rewards on housing payments, earn 4% Bilt Cash per dollar, which you can redeem toward housing payments or credits, 2 x $200 hotel credit per year *this will change for cards approved 1/1/27 or later – read more here*
Earning rate: 4% Bilt Cash on everyday purchases if you choose Bilt Cash rather than housing-only rewards + 3X points on dining or grocery (Limit $25K per year for grocery) ✦ 2X points on travel ✦ 1X points on everyday purchases ✦ 0.5X-1.25X points on rent & mortgage payments (if Housing-Only Earnings selected) ✦ 1X points on rent & mortgage payments when redeeming Bilt Cash (if Bilt Cash earning option selected)
Card Info: Mastercard World Elite issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ Up to $100 in Bilt Travel hotel credits ($50 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments
Card Info: Mastercard World Legend issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $200 Bilt Cash annually ✦ Up to $400 in Bilt Travel hotel credits ($200 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments ✦ Priority Pass (excludes restaurants)
Combo details: First off, Bilt only lets you have one Bilt card, so this combo is only possible if you have a 2nd player in the household that can add you as an authorized user (AU) to the second card. Bilt is unique in that it lets AU cards earn points and Bilt Cash to the AU’s account, so you can capture the earning categories (and accelerators) on both, but it also adds an additional fee of $50 for the Obsidian or $95 for the Palladium.
Why it’s great: This is another combo that offers excellent earning potential (2X to 4X everywhere), and Bilt has what most folks consider the best portfolio of transfer partners. It offers several 50%-100% Rent Day transfer bonuses per year that can deliver incredible value when transferring points. Using accelerators turns the Palladium card into a 3X everywhere earner, or even more if you’re also earning points on housing payments.
Shortcomings: First, you need two people to do it. Bilt doesn’t allow one person to be the primary cardholder on two cards. In addition, unlike many premium cards, there aren’t many included coupons, outside of 2 X $200 hotel credits on the Palladium and a $50 credit on the Obsidian, all of which require a two-night minimum and booking through Bilt’s travel portal. The earnings are great, but don’t forget that you’re still paying $600+ per year for them without the clear offsets of other cards. Starting 1/1/27, Bilt will lose 1:1 access to Hyatt, even with the Palladium card, which will be a big blow to the partner portfolio. Lastly, a third version of Bilt will take effect on January 1st, which represents a significant hit to earning power for folks who don’t earn points on housing payments.
Variation: Instead of incorporating the Obsidian card, you could use one Palladium card with an authorized user card that earns to the primary account. That setup would cost $590/year, but give you a total of $50K worth of 3X everywhere via accelerators. A downside is that AU card spend wouldn’t count toward elite status for the primary cardholder.
FM Mini Review: This card offers annual rebates that easily mitigate the fee for those who travel often. The card earns 2 miles per dollar on most purchases just like the Capital One Venture Rewards card, which are worth exactly 1 cent each toward travel. This makes the return on most spend similar to a 2% cash back card (though in this case you must redeem your miles to offset travel in order to get 1 cent per mile). One huge advantage over cash back: Capital One allows transfering their miles to airline miles & hotel points. Click here for our complete card review
$395 Annual Fee
Earning rate: 10X miles on hotels and rental cars booked via Capital One Travel ✦ 5X miles on flights and vacation rentals booked via Capital One travel ✦ 5X miles on Capital One Entertainment ✦ 2X miles everywhere else
Card Info: Visa Infinite issued by CapOne. This card has no foreign currency conversion fees.
Noteworthy perks: $300 annual credit for bookings made through Capital One Travel ✦ 10,000 bonus miles each year starting at first anniversary ✦ Up to $120 application fee credit for Global Entry or TSA PreCheck® ✦ Access to Capital One Lounge and Landing locations ✦ Priority Pass membership (participating lounges only) after enrollment ✦ Cell phone insurance ✦ Trip insurance ✦ Primary CDW coverage ✦ Redeem miles for travel at value of 1 cent per mile ✦ Transfer Miles to airline miles & hotel points
Earning rate: 8% cash back on Capital One Entertainment purchases ✦ 5% on hotels, vacation rentals, and rental cars booked via Capital One Travel (terms apply) ✦ 3% on dining, entertainment, select streaming services, and purchases at grocery stores (excluding superstores like Walmart® and Target®) ✦ 1% everywhere else
Base: 1%
Portal Hotels: 5%
Grocery: 3%
Dine: 3%
Card Info: Mastercard issued by CapOne. This card has no foreign currency conversion fees.
Combo details: Even though the Venture X has a $395 annual fee, you could consider this combo “almost free” after rebates, since it offers $300 in yearly Capital One Travel rebates plus 10K points each card anniversary, which together more than offset the annual fee. The fee-free Savor Cash Rewards adds 3x grocery, dining, and entertainment to the already strong 2x everywhere earnings offered by Venture X. Capital One lets you move cash back rewards to a “miles” card so that they then become transferable to partners. This allows you to earn 3% cash back with the Savor card and then convert that to “miles” by moving it to the Venture X card, unlocking better value by transferring to partners for high-value awards. You can also freely move points to anyone, so you don’t need more than one Venture X card in the family to make this combo work.
Why it’s great: Outstanding earnings with a “free after rebate” annual fee; this is the only combo that offers the same great earnings internationally with no foreign transaction fees. The Venture X provides excellent features such as cell phone protection, airport lounge access, and more. Capital One also offers arguably the best collection of card-linked offers. Additionally, Capital One is the only bank that has largely eschewed the stratospheric annual-fee coupon book for an ultra-premium card. It offers solid value without the mental load.
Shortcomings: The only way to get better than 1 cent per “Mile” value is by transferring to airline and hotel partners. Fewer opportunities for multiple, blingy welcome offers than Chase or Amex. Transfer partner portfolio lags behind Amex, Bilt, Citi, and Chase.
Variations:
Swap Venture X for Venture Rewards: Lower the annual fee to $95 per year with the Venture Rewards card instead of Venture X. Both offer 2x everywhere earnings, no foreign transaction fees, and the ability to transfer to airline and hotel partners. However, the Venture Rewards card doesn’t offer annual rebates that offset the annual fee and doesn’t offer lounge access.
Make it fee-free: You can cobble together a decent combo with no annual fees (and still have no foreign transaction fees). Start with the Savor for 3x grocery, dining, and entertainment, and then add the fee-free Quicksilver card to get 1.5x everywhere else, and then move all that cash back to the fee-free VentureOne Rewards card in order to transfer “Miles” to airline and hotel partners.
4X flights and hotels booked directly (Sapphire Reserve)
3X dining (Sapphire Reserve)
3X drug store (Freedom Unlimited)
2X gas stations (Ink Cash)
1.5X everywhere else (Freedom Unlimited)
Perks include 1:1 transfers to Hyatt, lounge access, up to $300 in annual travel rebates, up to $300 in annual dining credits, up to $300 in annual StubHub credits, up to $500 in annual The Edit credits, no foreign transaction fees, and excellent travel protections.
FM Mini Review: Good all-around card for frequent traveler. Best when paired with no annual fee Chase Freedom Flex, Freedom Unlimited & Chase Ink Cash cards. Click here for our complete card review
$795 Annual Fee
Earning rate: 8X Chase Travel℠ ✦ 4X flights and hotels booked direct ✦ 3X Dining ✦ 5X Lyft (through September 2027)
Card Info: Visa Infinite issued by Chase. This card has no foreign currency conversion fees.
Big spend bonus: After spending $75,000 each calendar year, get the following benefits: IHG One Rewards Diamond Elite Status ✦ World of Hyatt Explorist Status ✦ Southwest Airlines A-List Status ✦ $500 Southwest Airlines credit when booked through Chase Travel ✦ $250 credit to The Shops at Chase
Noteworthy perks: $300 Annual Travel Credit ✦ Transfer points to airline & hotel partners ✦ Up to $500 The Edit credit annually ($250 twice per calendar year) ✦ Up to $300 Dining credit through Sapphire Reserve Exclusive Tables ($150 January to June and again July to December) ✦ Complimentary Apple TV and Apple Music for a minimum of one year when activated by 6/22/27 ✦ Up to $300 in StubHub credits ($150 January to June and again July to December) ✦ Points worth up to 2 cents each towards qualified bookings through Chase Travel ✦ Primary auto rental coverage ✦ Priority Pass Select lounge access ✦ Access Sapphire Lounges for yourself and 2 guests for free ✦ Access select Air Canada Maple Leaf lounges when flying Star Alliance ✦ Up to $120 Global Entry or TSA PreCheck® or NEXUS Application Fee Statement Credit ✦ IHG One Rewards Platinum status through 12/31/27 ✦ Free DoorDash DashPass through 2027 ✦ Two promos of $10 off each month on non-restaurant orders from DoorDash ✦ $15 off restaurant order each month from DoorDash ✦ $10 monthly Lyft credit
FM Mini Review: Great for 3X categories and 1.5X everywhere else. Excellent companion card to Sapphire Reserve®, Sapphire Preferred®, or Ink Business Preferred®. Click here for our complete card review
No Annual Fee
Earning rate: 5X travel booked through Chase Travel℠ ✦ 3X dining ✦ 3X drugstores ✦ 2% cash back total on qualifying Lyft products and services purchased through the Lyft mobile application through 09/30/2027 ✦ 1.5X everywhere else
FM Mini Review: This one should be in everyone’s wallet. Incredible welcome offer for a no-annual-fee card. Great card for 5X categories. Excellent companion card to Sapphire Reserve, Sapphire Preferred, or Ink Business Preferred. Click here for our complete card review
No Annual Fee
Earning rate: 5X office supplies and cellular/landline/cable (on up to $25,000 in total purchases in 5X categories annually) ✦ 2X on the first $25K in combined purchases at gas stations and restaurants each cardmember year ✦ 5x Lyft through September 2027
Card Info: Visa Signature Business issued by Chase. This card imposes foreign transaction fees.
Noteworthy perks: Complimentary Instacart+ for 3 months (must activate by 12/31/27) ✦ $20 monthly Instacart credit ✦ $10 off each month on one non-restaurant order from DoorDash
Combo details: Many of Chase’s no-annual-fee cards are advertised as cashback cards, but they actually earn Ultimate Rewards points. Once you have points in one of these accounts, you can move them to your Sapphire Reserve account to make them transferable. Chase lets you move points to another person in the same household, so it makes sense for a couple to earn points across a variety of Ultimate Rewards cards and then move them all to a single Sapphire Reserve account. The Sapphire Reserve card provides three ways to get good value from your points: 1) transfer to airline and hotel partners for high-value awards; 2) book through Chase Travel℠ using points boosts at a value of up to 2 cents per point; and 3) erase statement charges at 1.25 cents per point value against current Pay Yourself Back categories (see this post for details).
Why it’s great: This is the only combo listed here that offers 1:1 transfers to Hyatt, which can translate into incredible value. Points are also worth up to 2 cents each toward select bookings via Chase Travel℠, but only on bookings with points boosts, which is a limited subset. You can sometimes get even better value by transferring points to Chase’s high-value travel partners. The Sapphire Reserve offers excellent automatic travel protections…provided that you don’t live in New York.
Shortcomings: Requires three cards instead of two. The Sapphire Reserve card costs $795 per year, and the value you get from the array of rebates will vary from person to person. The Freedom Unlimited and Ink Business Cash cards charge foreign exchange fees, so you’ll want to use your Sapphire Reserve card when traveling outside of the US, at which point you’re only earning 1X everywhere. This is also the only combo in this roundup that doesn’t offer a standard grocery bonus and doesn’t have a 2X everywhere option.
Add-on: Consider adding the no-fee Chase Freedom Flex card, which offers rotating 5X categories.
Variation: You can lower annual fees to $95 per year by replacing the Sapphire Reserve with either the Sapphire Preferred® or the Ink Business Preferred®. Both let you transfer points to travel hotel and airline partners and still offer the expansive “travel” category bonus the Sapphire Reserve lost in the 2025 refresh. However, both also have a reduced 4:3 transfer ratio to World of Hyatt
FM Mini Review: Very strong earnings for spend. Excellent bonus categories. Points transferable to select airlines. Recommend pairing this card with Citi Double Cash Click here for our complete card review
$95 Annual Fee
Earning rate: 10X hotels, car rentals, and attractions booked through Citi Travel℠ ✦ 3X grocery ✦ 3X dining ✦ 3X gas stations & EV charging ✦ 3X flights, hotels, travel agencies ✦ 1x everywhere else
Card Info: Mastercard World Elite issued by Citi. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $100 Annual Hotel Savings Benefit ($100 off a $500+ hotel stay, excluding taxes and fees, when booked through Citi Travel) ✦ Travel protections
FM Mini Review: 2X rewards for all spend with no annual fee makes this card a winner. Earn 2X everywhere and redeem for the equivalent of 2% cash back or 2X ThankYou points. Pair with the Premier or Prestige card to make points transferrable to airlines. Click here for our complete card review
No Annual Fee
Earning rate: 2% cash back everywhere ✦ Earn 3% total cash back on hotel, car rentals, and attractions booked on Citi Travel℠ Portal
Combo details: Citi lets you pool ThankYou points across your cards to get the best possible redemption value. You can also transfer points to anyone, but once you do, you must use them within 90 days, or they’ll expire.
Why it’s great: Excellent point earnings, especially for a combo with a total $95 annual fee (the Strata Premier card costs $95 per year, while the other cards are free). Both provide free authorized user cards. Travel partners are an intriguing mix of airlines and hotels, with unique 1:1 options like American AAdvantage, EVA Air, and Japan Airlines.
Shortcomings: Citi no longer allows you to share points with other cardholders. It has also effectively discontinued options for earning more than 1 cent per point, outside of transferring points to partners, and has tanked the transfer ratios of its most valuable lodging partners. Earlier this year, Citi stopped accepting applications for the Custom Cash, removing the only option for 5X earning. Lastly, Citi offers somewhat lackluster travel protections compared with some of the other card combinations listed here.
FM Mini Review: This card offers a competitive flat 2% back on purchases and includes good cell phone insurance for a no annual fee card (up to $600 in protection with just a $25 deductible). Pair with a Wells Fargo Autograph or Autograph Journey card to make the rewards transferable to airline and hotel partners.
Card Info: Visa issued by Wells. This card imposes foreign transaction fees.
Combo details: Like Capital One, Wells Fargo lets you transfer cash rewards to the Autograph Journey card at a 1:1 ratio. This lets you transfer rewards earned on both cards to travel partners. Wells Fargo also lets you transfer as little as one point to a partner program, making it easy to avoid leaving orphaned rewards in a partner account.
Why it’s great: These cards offer excellent points earnings for a total $95 annual fee, not including the $50 yearly airfare credit that comes with the Autograph Journey. 5x at hotels is another unique feature of this combo. The cards offer decent travel and purchase protections, plus very good cell phone insurance.
Shortcomings: A big downside is that this combo has no grocery bonus, so the best that you can do is 2x with the Active Cash. While the Autograph Journey doesn’t have foreign transaction fees, the other two cards do, making it a one-card system when traveling (with a 1X floor). Wells Fargo’s collection of transfer partners is undoubtedly the weakest of all the programs we’re comparing. Currently, there are only eight, including the different Avios programs that effectively function as one. The only domestic airline is JetBlue, and the only hotel partners are Choice Privileges and Wyndham Rewards (both with an excellent 1:2 transfer ratio). If Wells Fargo can beef up its partner list to rival the other issuers listed here, this will become a much more delectable combo. Like Amex and Citibank, Wells Fargo no longer allows you to transfer points to other users.
Which is the best credit card combo?
So, which combo is best? It’s difficult to answer that question without understanding the needs of the person who’s asking. Any of these combos may be best for you, depending on your tolerance for annual fees, your spending patterns, and how you’re likely to use your rewards. Picking one “best” is harder than it’s ever been.
Bilt offers excellent value and earning potential, but you need a second participant to use multiple cards, and the high annual fees will be increasingly intrusive for those who sign up after 1/1/27 and don’t have a housing payment. Because one person can’t have more than one card, it’s hard to call this the best combo, and you can get plenty of value from the Palladium or Obsidian card on their own, especially if you have a monthly housing payment.
Getting 1:1 transfers to Hyatt is getting increasingly difficult…and expensive. With Bilt moving to a 4:3 ratio to Hyatt, the Chase combo becomes the only way to retain 1:1 Hyatt transfers, something that can be extended to additional household players because of Chase’s transfer policy. However, the $795 annual fee is the highest on this list, and it requires you to get significant value from the various coupons. That said, it’s less than $200 more than the Bilt “combo,” which is pretty amazing given how many more credits the Chase version offers.
I love the Citi combo because it offers probably the best all-around card listed here for category bonuses: the Strata Premier, which earns 3x at gas stations, grocery stores, restaurants, AND travel – all on one card. I can give player 2 (my wife) a Double Cash and the Strata Premier and know that she’s earning 2x everywhere and 3x at most of the places that she spends money. Citi has a great mix of airline partners, including American Airlines, EVA Air, and Japan Airlines. However, lodging has taken a big hit: Preferred Hotels is now 1:2, Choice is 1:1.5, and Leading Hotels of the World offers 25% more value through Amex (4:1 vs 5:1). Additionally, closing the Custom Cash to new applicants removes the ability to earn 5X in the category of your choice on $500/month in purchases.
For many folks, the Capital One Venture X + Savor combo will be best, because it only requires holding two cards and offers substantial rewards in popular categories (3x grocery, dining, and entertainment); strong rewards on all other spend (2x); no foreign transaction fees; and ultra-premium card features (airport lounge access and travel protections) all for “free after rebate” (spend $395, but get back $300 in travel credits and 10K points each year).
Final Thoughts
I have and use almost all of the cards listed above, but if I had to pick one “combo,” it would probably be Chase, surprisingly enough. Capital One would come in second by a hair. I’ve had great luck combining points boosts with my Edit credits to get excellent value; add in 1:1 transfers to Hyatt, and there are reasonable paths to get good value for both lodging and flights. I also like the earning potential, travel protections, and lounge access.
That’s a huge change from last year, when I had Citi number one, but after downgrading its lodging transfers, removing the Custom Cash card, and nixing the ability to move points to other cardholders, it’s lost enough appeal to no longer reign supreme. I also love my Bilt Palladium card and plan to keep it as long as I can keep the current earning regime, but as a combo, the need to have a second player, pay over $600 in annual fees, and accept sub-1:1 Hyatt transfers makes it tough to pick.
All of the combos listed here could be best, depending on the individual, and I could make an argument for any of them. In reality, I use a “multi-combo combo,” that combines several of them; that may be the best choice for others as well. If you do expand into multiple currencies, be careful to keep an eye on those annual fees to make sure you’re getting enough value out of your wallet to justify the expense.
Card Info: Amex Pay Over Time Card issued by Amex. This card has no foreign currency conversion fees.
Noteworthy perks: Up to $10 in statement credits monthly with participating dining partners (Grubhub (including Seamless), Buffalo Wild Wings, Five Guys, The Cheesecake Factory, and Wonder) ✦ $10 monthly Uber or Uber Eats credit (use it or lose it each month – must select Amex card as payment method to redeem) ✦ Up to $7 monthly Dunkin’ credit – enrollment required ✦ Up to $50 twice-annual Resy credit ✦ $100 hotel credit on qualifying charges on stays of 2 nights or longer, plus a room upgrade upon arrival, if available with The Hotel Collection at americanexpress.com/hc ✦ Complimentary Hertz Five Star® Status ✦ Enrollment required for select benefits.
FM Mini Review: 2X rewards for all eligible purchases (up to $50K per year) with no annual fee makes this card a winner. Click here for our complete card review
No Annual Fee
Earning rate: 2X Membership Rewards points on all eligible purchases, up to $50K spend per calendar year (then 1X thereafter). Terms apply. (Rates & Fees)
Card Info: Amex Credit Card issued by Amex. This card imposes foreign transaction fees.
Combo details: Amex automatically pools all your Membership Rewards points, even if you earned them with different cards. While you can’t move points from one person to another, you can transfer points to a friend’s airline or hotel program account if they are an authorized user (or employee) on one of your accounts.
Why it’s great: This combination delivers terrific earning potential (2X to 4X everywhere in the US!) and lets you transfer points to Amex’s valuable transfer Partners. Traditionally, Amex has offered more transfer bonuses than other issuers, though that has changed over the last year or so. For those who can use the Gold card’s $10/month dining, 2x$50 Resy credits, and $10/month Uber/Uber Eats credits, the $325 annual fee becomes easier to justify.
Shortcomings: Yearly limits and foreign travel. The Gold card’s 4X grocery bonus is capped at $25K in annual spend and is limited to stores in the US, while the 4X at restaurants is worldwide but capped at $50K/year. The Blue Business Plus card charges foreign transaction fees and limits the 2X bonus to $50K per year, making this a less desirable combo for those who spend big or for those looking for great rewards on spending outside of the United States…and since Amex often isn’t accepted outside of the United States, you’ll want a backup Visa or Mastercard when traveling anyway. This combo also requires a business card to earn 2x everywhere.
Add-on: There are several worthwhile cards to consider adding to this combo:
The Platinum Card® offers a compelling lineup of perks and boosts flight earnings to 5X. Unfortunately, it also adds an $895 annual fee.
Also worth looking at is the Schwab Platinum Card, which has many similar perks to the Business Platinum and lets you cash out points at 1.1 cents each (1 million points/year max).
+1X on up to $50K in purchases using accelerators ($25K on each card)
Double rewards on the first of the month (1,000 bonus points max)
Perks include: earn rewards on housing payments, earn 4% Bilt Cash per dollar, which you can redeem toward housing payments or credits, 2 x $200 hotel credit per year *this will change for cards approved 1/1/27 or later – read more here*
Earning rate: 4% Bilt Cash on everyday purchases if you choose Bilt Cash rather than housing-only rewards + 3X points on dining or grocery (Limit $25K per year for grocery) ✦ 2X points on travel ✦ 1X points on everyday purchases ✦ 0.5X-1.25X points on rent & mortgage payments (if Housing-Only Earnings selected) ✦ 1X points on rent & mortgage payments when redeeming Bilt Cash (if Bilt Cash earning option selected)
Card Info: Mastercard World Elite issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ Up to $100 in Bilt Travel hotel credits ($50 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments
Card Info: Mastercard World Legend issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $200 Bilt Cash annually ✦ Up to $400 in Bilt Travel hotel credits ($200 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments ✦ Priority Pass (excludes restaurants)
Combo details: First off, Bilt only lets you have one Bilt card, so this combo is only possible if you have a 2nd player in the household that can add you as an authorized user (AU) to the second card. Bilt is unique in that it lets AU cards earn points and Bilt Cash to the AU’s account, so you can capture the earning categories (and accelerators) on both, but it also adds an additional fee of $50 for the Obsidian or $95 for the Palladium.
Why it’s great: This is another combo that offers excellent earning potential (2X to 4X everywhere), and Bilt has what most folks consider the best portfolio of transfer partners. It offers several 50%-100% Rent Day transfer bonuses per year that can deliver incredible value when transferring points. Using accelerators turns the Palladium card into a 3X everywhere earner, or even more if you’re also earning points on housing payments.
Shortcomings: First, you need two people to do it. Bilt doesn’t allow one person to be the primary cardholder on two cards. In addition, unlike many premium cards, there aren’t many included coupons, outside of 2 X $200 hotel credits on the Palladium and a $50 credit on the Obsidian, all of which require a two-night minimum and booking through Bilt’s travel portal. The earnings are great, but don’t forget that you’re still paying $600+ per year for them without the clear offsets of other cards. Starting 1/1/27, Bilt will lose 1:1 access to Hyatt, even with the Palladium card, which will be a big blow to the partner portfolio. Lastly, a third version of Bilt will take effect on January 1st, which represents a significant hit to earning power for folks who don’t earn points on housing payments.
Variation: Instead of incorporating the Obsidian card, you could use one Palladium card with an authorized user card that earns to the primary account. That setup would cost $590/year, but give you a total of $50K worth of 3X everywhere via accelerators. A downside is that AU card spend wouldn’t count toward elite status for the primary cardholder.
FM Mini Review: This card offers annual rebates that easily mitigate the fee for those who travel often. The card earns 2 miles per dollar on most purchases just like the Capital One Venture Rewards card, which are worth exactly 1 cent each toward travel. This makes the return on most spend similar to a 2% cash back card (though in this case you must redeem your miles to offset travel in order to get 1 cent per mile). One huge advantage over cash back: Capital One allows transfering their miles to airline miles & hotel points. Click here for our complete card review
$395 Annual Fee
Earning rate: 10X miles on hotels and rental cars booked via Capital One Travel ✦ 5X miles on flights and vacation rentals booked via Capital One travel ✦ 5X miles on Capital One Entertainment ✦ 2X miles everywhere else
Card Info: Visa Infinite issued by CapOne. This card has no foreign currency conversion fees.
Noteworthy perks: $300 annual credit for bookings made through Capital One Travel ✦ 10,000 bonus miles each year starting at first anniversary ✦ Up to $120 application fee credit for Global Entry or TSA PreCheck® ✦ Access to Capital One Lounge and Landing locations ✦ Priority Pass membership (participating lounges only) after enrollment ✦ Cell phone insurance ✦ Trip insurance ✦ Primary CDW coverage ✦ Redeem miles for travel at value of 1 cent per mile ✦ Transfer Miles to airline miles & hotel points
Earning rate: 8% cash back on Capital One Entertainment purchases ✦ 5% on hotels, vacation rentals, and rental cars booked via Capital One Travel (terms apply) ✦ 3% on dining, entertainment, select streaming services, and purchases at grocery stores (excluding superstores like Walmart® and Target®) ✦ 1% everywhere else
Base: 1%
Portal Hotels: 5%
Grocery: 3%
Dine: 3%
Card Info: Mastercard issued by CapOne. This card has no foreign currency conversion fees.
Combo details: Even though the Venture X has a $395 annual fee, you could consider this combo “almost free” after rebates, since it offers $300 in yearly Capital One Travel rebates plus 10K points each card anniversary, which together more than offset the annual fee. The fee-free Savor Cash Rewards adds 3x grocery, dining, and entertainment to the already strong 2x everywhere earnings offered by Venture X. Capital One lets you move cash back rewards to a “miles” card so that they then become transferable to partners. This allows you to earn 3% cash back with the Savor card and then convert that to “miles” by moving it to the Venture X card, unlocking better value by transferring to partners for high-value awards. You can also freely move points to anyone, so you don’t need more than one Venture X card in the family to make this combo work.
Why it’s great: Outstanding earnings with a “free after rebate” annual fee; this is the only combo that offers the same great earnings internationally with no foreign transaction fees. The Venture X provides excellent features such as cell phone protection, airport lounge access, and more. Capital One also offers arguably the best collection of card-linked offers. Additionally, Capital One is the only bank that has largely eschewed the stratospheric annual-fee coupon book for an ultra-premium card. It offers solid value without the mental load.
Shortcomings: The only way to get better than 1 cent per “Mile” value is by transferring to airline and hotel partners. Fewer opportunities for multiple, blingy welcome offers than Chase or Amex. Transfer partner portfolio lags behind Amex, Bilt, Citi, and Chase.
Variations:
Swap Venture X for Venture Rewards: Lower the annual fee to $95 per year with the Venture Rewards card instead of Venture X. Both offer 2x everywhere earnings, no foreign transaction fees, and the ability to transfer to airline and hotel partners. However, the Venture Rewards card doesn’t offer annual rebates that offset the annual fee and doesn’t offer lounge access.
Make it fee-free: You can cobble together a decent combo with no annual fees (and still have no foreign transaction fees). Start with the Savor for 3x grocery, dining, and entertainment, and then add the fee-free Quicksilver card to get 1.5x everywhere else, and then move all that cash back to the fee-free VentureOne Rewards card in order to transfer “Miles” to airline and hotel partners.
4X flights and hotels booked directly (Sapphire Reserve)
3X dining (Sapphire Reserve)
3X drug store (Freedom Unlimited)
2X gas stations (Ink Cash)
1.5X everywhere else (Freedom Unlimited)
Perks include 1:1 transfers to Hyatt, lounge access, up to $300 in annual travel rebates, up to $300 in annual dining credits, up to $300 in annual StubHub credits, up to $500 in annual The Edit credits, no foreign transaction fees, and excellent travel protections.
FM Mini Review: Good all-around card for frequent traveler. Best when paired with no annual fee Chase Freedom Flex, Freedom Unlimited & Chase Ink Cash cards. Click here for our complete card review
$795 Annual Fee
Earning rate: 8X Chase Travel℠ ✦ 4X flights and hotels booked direct ✦ 3X Dining ✦ 5X Lyft (through September 2027)
Card Info: Visa Infinite issued by Chase. This card has no foreign currency conversion fees.
Big spend bonus: After spending $75,000 each calendar year, get the following benefits: IHG One Rewards Diamond Elite Status ✦ World of Hyatt Explorist Status ✦ Southwest Airlines A-List Status ✦ $500 Southwest Airlines credit when booked through Chase Travel ✦ $250 credit to The Shops at Chase
Noteworthy perks: $300 Annual Travel Credit ✦ Transfer points to airline & hotel partners ✦ Up to $500 The Edit credit annually ($250 twice per calendar year) ✦ Up to $300 Dining credit through Sapphire Reserve Exclusive Tables ($150 January to June and again July to December) ✦ Complimentary Apple TV and Apple Music for a minimum of one year when activated by 6/22/27 ✦ Up to $300 in StubHub credits ($150 January to June and again July to December) ✦ Points worth up to 2 cents each towards qualified bookings through Chase Travel ✦ Primary auto rental coverage ✦ Priority Pass Select lounge access ✦ Access Sapphire Lounges for yourself and 2 guests for free ✦ Access select Air Canada Maple Leaf lounges when flying Star Alliance ✦ Up to $120 Global Entry or TSA PreCheck® or NEXUS Application Fee Statement Credit ✦ IHG One Rewards Platinum status through 12/31/27 ✦ Free DoorDash DashPass through 2027 ✦ Two promos of $10 off each month on non-restaurant orders from DoorDash ✦ $15 off restaurant order each month from DoorDash ✦ $10 monthly Lyft credit
FM Mini Review: Great for 3X categories and 1.5X everywhere else. Excellent companion card to Sapphire Reserve®, Sapphire Preferred®, or Ink Business Preferred®. Click here for our complete card review
No Annual Fee
Earning rate: 5X travel booked through Chase Travel℠ ✦ 3X dining ✦ 3X drugstores ✦ 2% cash back total on qualifying Lyft products and services purchased through the Lyft mobile application through 09/30/2027 ✦ 1.5X everywhere else
FM Mini Review: This one should be in everyone’s wallet. Incredible welcome offer for a no-annual-fee card. Great card for 5X categories. Excellent companion card to Sapphire Reserve, Sapphire Preferred, or Ink Business Preferred. Click here for our complete card review
No Annual Fee
Earning rate: 5X office supplies and cellular/landline/cable (on up to $25,000 in total purchases in 5X categories annually) ✦ 2X on the first $25K in combined purchases at gas stations and restaurants each cardmember year ✦ 5x Lyft through September 2027
Card Info: Visa Signature Business issued by Chase. This card imposes foreign transaction fees.
Noteworthy perks: Complimentary Instacart+ for 3 months (must activate by 12/31/27) ✦ $20 monthly Instacart credit ✦ $10 off each month on one non-restaurant order from DoorDash
Combo details: Many of Chase’s no-annual-fee cards are advertised as cashback cards, but they actually earn Ultimate Rewards points. Once you have points in one of these accounts, you can move them to your Sapphire Reserve account to make them transferable. Chase lets you move points to another person in the same household, so it makes sense for a couple to earn points across a variety of Ultimate Rewards cards and then move them all to a single Sapphire Reserve account. The Sapphire Reserve card provides three ways to get good value from your points: 1) transfer to airline and hotel partners for high-value awards; 2) book through Chase Travel℠ using points boosts at a value of up to 2 cents per point; and 3) erase statement charges at 1.25 cents per point value against current Pay Yourself Back categories (see this post for details).
Why it’s great: This is the only combo listed here that offers 1:1 transfers to Hyatt, which can translate into incredible value. Points are also worth up to 2 cents each toward select bookings via Chase Travel℠, but only on bookings with points boosts, which is a limited subset. You can sometimes get even better value by transferring points to Chase’s high-value travel partners. The Sapphire Reserve offers excellent automatic travel protections…provided that you don’t live in New York.
Shortcomings: Requires three cards instead of two. The Sapphire Reserve card costs $795 per year, and the value you get from the array of rebates will vary from person to person. The Freedom Unlimited and Ink Business Cash cards charge foreign exchange fees, so you’ll want to use your Sapphire Reserve card when traveling outside of the US, at which point you’re only earning 1X everywhere. This is also the only combo in this roundup that doesn’t offer a standard grocery bonus and doesn’t have a 2X everywhere option.
Add-on: Consider adding the no-fee Chase Freedom Flex card, which offers rotating 5X categories.
Variation: You can lower annual fees to $95 per year by replacing the Sapphire Reserve with either the Sapphire Preferred® or the Ink Business Preferred®. Both let you transfer points to travel hotel and airline partners and still offer the expansive “travel” category bonus the Sapphire Reserve lost in the 2025 refresh. However, both also have a reduced 4:3 transfer ratio to World of Hyatt
FM Mini Review: Very strong earnings for spend. Excellent bonus categories. Points transferable to select airlines. Recommend pairing this card with Citi Double Cash Click here for our complete card review
$95 Annual Fee
Earning rate: 10X hotels, car rentals, and attractions booked through Citi Travel℠ ✦ 3X grocery ✦ 3X dining ✦ 3X gas stations & EV charging ✦ 3X flights, hotels, travel agencies ✦ 1x everywhere else
Card Info: Mastercard World Elite issued by Citi. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $100 Annual Hotel Savings Benefit ($100 off a $500+ hotel stay, excluding taxes and fees, when booked through Citi Travel) ✦ Travel protections
FM Mini Review: 2X rewards for all spend with no annual fee makes this card a winner. Earn 2X everywhere and redeem for the equivalent of 2% cash back or 2X ThankYou points. Pair with the Premier or Prestige card to make points transferrable to airlines. Click here for our complete card review
No Annual Fee
Earning rate: 2% cash back everywhere ✦ Earn 3% total cash back on hotel, car rentals, and attractions booked on Citi Travel℠ Portal
Combo details: Citi lets you pool ThankYou points across your cards to get the best possible redemption value. You can also transfer points to anyone, but once you do, you must use them within 90 days, or they’ll expire.
Why it’s great: Excellent point earnings, especially for a combo with a total $95 annual fee (the Strata Premier card costs $95 per year, while the other cards are free). Both provide free authorized user cards. Travel partners are an intriguing mix of airlines and hotels, with unique 1:1 options like American AAdvantage, EVA Air, and Japan Airlines.
Shortcomings: Citi no longer allows you to share points with other cardholders. It has also effectively discontinued options for earning more than 1 cent per point, outside of transferring points to partners, and has tanked the transfer ratios of its most valuable lodging partners. Earlier this year, Citi stopped accepting applications for the Custom Cash, removing the only option for 5X earning. Lastly, Citi offers somewhat lackluster travel protections compared with some of the other card combinations listed here.
FM Mini Review: This card offers a competitive flat 2% back on purchases and includes good cell phone insurance for a no annual fee card (up to $600 in protection with just a $25 deductible). Pair with a Wells Fargo Autograph or Autograph Journey card to make the rewards transferable to airline and hotel partners.
Card Info: Visa issued by Wells. This card imposes foreign transaction fees.
Combo details: Like Capital One, Wells Fargo lets you transfer cash rewards to the Autograph Journey card at a 1:1 ratio. This lets you transfer rewards earned on both cards to travel partners. Wells Fargo also lets you transfer as little as one point to a partner program, making it easy to avoid leaving orphaned rewards in a partner account.
Why it’s great: These cards offer excellent points earnings for a total $95 annual fee, not including the $50 yearly airfare credit that comes with the Autograph Journey. 5x at hotels is another unique feature of this combo. The cards offer decent travel and purchase protections, plus very good cell phone insurance.
Shortcomings: A big downside is that this combo has no grocery bonus, so the best that you can do is 2x with the Active Cash. While the Autograph Journey doesn’t have foreign transaction fees, the other two cards do, making it a one-card system when traveling (with a 1X floor). Wells Fargo’s collection of transfer partners is undoubtedly the weakest of all the programs we’re comparing. Currently, there are only eight, including the different Avios programs that effectively function as one. The only domestic airline is JetBlue, and the only hotel partners are Choice Privileges and Wyndham Rewards (both with an excellent 1:2 transfer ratio). If Wells Fargo can beef up its partner list to rival the other issuers listed here, this will become a much more delectable combo. Like Amex and Citibank, Wells Fargo no longer allows you to transfer points to other users.
Which is the best credit card combo?
So, which combo is best? It’s difficult to answer that question without understanding the needs of the person who’s asking. Any of these combos may be best for you, depending on your tolerance for annual fees, your spending patterns, and how you’re likely to use your rewards. Picking one “best” is harder than it’s ever been.
Bilt offers excellent value and earning potential, but you need a second participant to use multiple cards, and the high annual fees will be increasingly intrusive for those who sign up after 1/1/27 and don’t have a housing payment. Because one person can’t have more than one card, it’s hard to call this the best combo, and you can get plenty of value from the Palladium or Obsidian card on their own, especially if you have a monthly housing payment.
Getting 1:1 transfers to Hyatt is getting increasingly difficult…and expensive. With Bilt moving to a 4:3 ratio to Hyatt, the Chase combo becomes the only way to retain 1:1 Hyatt transfers, something that can be extended to additional household players because of Chase’s transfer policy. However, the $795 annual fee is the highest on this list, and it requires you to get significant value from the various coupons. That said, it’s less than $200 more than the Bilt “combo,” which is pretty amazing given how many more credits the Chase version offers.
I love the Citi combo because it offers probably the best all-around card listed here for category bonuses: the Strata Premier, which earns 3x at gas stations, grocery stores, restaurants, AND travel – all on one card. I can give player 2 (my wife) a Double Cash and the Strata Premier and know that she’s earning 2x everywhere and 3x at most of the places that she spends money. Citi has a great mix of airline partners, including American Airlines, EVA Air, and Japan Airlines. However, lodging has taken a big hit: Preferred Hotels is now 1:2, Choice is 1:1.5, and Leading Hotels of the World offers 25% more value through Amex (4:1 vs 5:1). Additionally, closing the Custom Cash to new applicants removes the ability to earn 5X in the category of your choice on $500/month in purchases.
For many folks, the Capital One Venture X + Savor combo will be best, because it only requires holding two cards and offers substantial rewards in popular categories (3x grocery, dining, and entertainment); strong rewards on all other spend (2x); no foreign transaction fees; and ultra-premium card features (airport lounge access and travel protections) all for “free after rebate” (spend $395, but get back $300 in travel credits and 10K points each year).
Final Thoughts
I have and use almost all of the cards listed above, but if I had to pick one “combo,” it would probably be Chase, surprisingly enough. Capital One would come in second by a hair. I’ve had great luck combining points boosts with my Edit credits to get excellent value; add in 1:1 transfers to Hyatt, and there are reasonable paths to get good value for both lodging and flights. I also like the earning potential, travel protections, and lounge access.
That’s a huge change from last year, when I had Citi number one, but after downgrading its lodging transfers, removing the Custom Cash card, and nixing the ability to move points to other cardholders, it’s lost enough appeal to no longer reign supreme. I also love my Bilt Palladium card and plan to keep it as long as I can keep the current earning regime, but as a combo, the need to have a second player, pay over $600 in annual fees, and accept sub-1:1 Hyatt transfers makes it tough to pick.
All of the combos listed here could be best, depending on the individual, and I could make an argument for any of them. In reality, I use a “multi-combo combo,” that combines several of them; that may be the best choice for others as well. If you do expand into multiple currencies, be careful to keep an eye on those annual fees to make sure you’re getting enough value out of your wallet to justify the expense.
Card Info: Amex Pay Over Time Card issued by Amex. This card has no foreign currency conversion fees.
Noteworthy perks: Up to $10 in statement credits monthly with participating dining partners (Grubhub (including Seamless), Buffalo Wild Wings, Five Guys, The Cheesecake Factory, and Wonder) ✦ $10 monthly Uber or Uber Eats credit (use it or lose it each month – must select Amex card as payment method to redeem) ✦ Up to $7 monthly Dunkin’ credit – enrollment required ✦ Up to $50 twice-annual Resy credit ✦ $100 hotel credit on qualifying charges on stays of 2 nights or longer, plus a room upgrade upon arrival, if available with The Hotel Collection at americanexpress.com/hc ✦ Complimentary Hertz Five Star® Status ✦ Enrollment required for select benefits.
FM Mini Review: 2X rewards for all eligible purchases (up to $50K per year) with no annual fee makes this card a winner. Click here for our complete card review
No Annual Fee
Earning rate: 2X Membership Rewards points on all eligible purchases, up to $50K spend per calendar year (then 1X thereafter). Terms apply. (Rates & Fees)
Card Info: Amex Credit Card issued by Amex. This card imposes foreign transaction fees.
Combo details: Amex automatically pools all your Membership Rewards points, even if you earned them with different cards. While you can’t move points from one person to another, you can transfer points to a friend’s airline or hotel program account if they are an authorized user (or employee) on one of your accounts.
Why it’s great: This combination delivers terrific earning potential (2X to 4X everywhere in the US!) and lets you transfer points to Amex’s valuable transfer Partners. Traditionally, Amex has offered more transfer bonuses than other issuers, though that has changed over the last year or so. For those who can use the Gold card’s $10/month dining, 2x$50 Resy credits, and $10/month Uber/Uber Eats credits, the $325 annual fee becomes easier to justify.
Shortcomings: Yearly limits and foreign travel. The Gold card’s 4X grocery bonus is capped at $25K in annual spend and is limited to stores in the US, while the 4X at restaurants is worldwide but capped at $50K/year. The Blue Business Plus card charges foreign transaction fees and limits the 2X bonus to $50K per year, making this a less desirable combo for those who spend big or for those looking for great rewards on spending outside of the United States…and since Amex often isn’t accepted outside of the United States, you’ll want a backup Visa or Mastercard when traveling anyway. This combo also requires a business card to earn 2x everywhere.
Add-on: There are several worthwhile cards to consider adding to this combo:
The Platinum Card® offers a compelling lineup of perks and boosts flight earnings to 5X. Unfortunately, it also adds an $895 annual fee.
Also worth looking at is the Schwab Platinum Card, which has many similar perks to the Business Platinum and lets you cash out points at 1.1 cents each (1 million points/year max).
+1X on up to $50K in purchases using accelerators ($25K on each card)
Double rewards on the first of the month (1,000 bonus points max)
Perks include: earn rewards on housing payments, earn 4% Bilt Cash per dollar, which you can redeem toward housing payments or credits, 2 x $200 hotel credit per year *this will change for cards approved 1/1/27 or later – read more here*
Earning rate: 4% Bilt Cash on everyday purchases if you choose Bilt Cash rather than housing-only rewards + 3X points on dining or grocery (Limit $25K per year for grocery) ✦ 2X points on travel ✦ 1X points on everyday purchases ✦ 0.5X-1.25X points on rent & mortgage payments (if Housing-Only Earnings selected) ✦ 1X points on rent & mortgage payments when redeeming Bilt Cash (if Bilt Cash earning option selected)
Card Info: Mastercard World Elite issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ Up to $100 in Bilt Travel hotel credits ($50 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments
Card Info: Mastercard World Legend issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $200 Bilt Cash annually ✦ Up to $400 in Bilt Travel hotel credits ($200 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments ✦ Priority Pass (excludes restaurants)
Combo details: First off, Bilt only lets you have one Bilt card, so this combo is only possible if you have a 2nd player in the household that can add you as an authorized user (AU) to the second card. Bilt is unique in that it lets AU cards earn points and Bilt Cash to the AU’s account, so you can capture the earning categories (and accelerators) on both, but it also adds an additional fee of $50 for the Obsidian or $95 for the Palladium.
Why it’s great: This is another combo that offers excellent earning potential (2X to 4X everywhere), and Bilt has what most folks consider the best portfolio of transfer partners. It offers several 50%-100% Rent Day transfer bonuses per year that can deliver incredible value when transferring points. Using accelerators turns the Palladium card into a 3X everywhere earner, or even more if you’re also earning points on housing payments.
Shortcomings: First, you need two people to do it. Bilt doesn’t allow one person to be the primary cardholder on two cards. In addition, unlike many premium cards, there aren’t many included coupons, outside of 2 X $200 hotel credits on the Palladium and a $50 credit on the Obsidian, all of which require a two-night minimum and booking through Bilt’s travel portal. The earnings are great, but don’t forget that you’re still paying $600+ per year for them without the clear offsets of other cards. Starting 1/1/27, Bilt will lose 1:1 access to Hyatt, even with the Palladium card, which will be a big blow to the partner portfolio. Lastly, a third version of Bilt will take effect on January 1st, which represents a significant hit to earning power for folks who don’t earn points on housing payments.
Variation: Instead of incorporating the Obsidian card, you could use one Palladium card with an authorized user card that earns to the primary account. That setup would cost $590/year, but give you a total of $50K worth of 3X everywhere via accelerators. A downside is that AU card spend wouldn’t count toward elite status for the primary cardholder.
FM Mini Review: This card offers annual rebates that easily mitigate the fee for those who travel often. The card earns 2 miles per dollar on most purchases just like the Capital One Venture Rewards card, which are worth exactly 1 cent each toward travel. This makes the return on most spend similar to a 2% cash back card (though in this case you must redeem your miles to offset travel in order to get 1 cent per mile). One huge advantage over cash back: Capital One allows transfering their miles to airline miles & hotel points. Click here for our complete card review
$395 Annual Fee
Earning rate: 10X miles on hotels and rental cars booked via Capital One Travel ✦ 5X miles on flights and vacation rentals booked via Capital One travel ✦ 5X miles on Capital One Entertainment ✦ 2X miles everywhere else
Card Info: Visa Infinite issued by CapOne. This card has no foreign currency conversion fees.
Noteworthy perks: $300 annual credit for bookings made through Capital One Travel ✦ 10,000 bonus miles each year starting at first anniversary ✦ Up to $120 application fee credit for Global Entry or TSA PreCheck® ✦ Access to Capital One Lounge and Landing locations ✦ Priority Pass membership (participating lounges only) after enrollment ✦ Cell phone insurance ✦ Trip insurance ✦ Primary CDW coverage ✦ Redeem miles for travel at value of 1 cent per mile ✦ Transfer Miles to airline miles & hotel points
Earning rate: 8% cash back on Capital One Entertainment purchases ✦ 5% on hotels, vacation rentals, and rental cars booked via Capital One Travel (terms apply) ✦ 3% on dining, entertainment, select streaming services, and purchases at grocery stores (excluding superstores like Walmart® and Target®) ✦ 1% everywhere else
Base: 1%
Portal Hotels: 5%
Grocery: 3%
Dine: 3%
Card Info: Mastercard issued by CapOne. This card has no foreign currency conversion fees.
Combo details: Even though the Venture X has a $395 annual fee, you could consider this combo “almost free” after rebates, since it offers $300 in yearly Capital One Travel rebates plus 10K points each card anniversary, which together more than offset the annual fee. The fee-free Savor Cash Rewards adds 3x grocery, dining, and entertainment to the already strong 2x everywhere earnings offered by Venture X. Capital One lets you move cash back rewards to a “miles” card so that they then become transferable to partners. This allows you to earn 3% cash back with the Savor card and then convert that to “miles” by moving it to the Venture X card, unlocking better value by transferring to partners for high-value awards. You can also freely move points to anyone, so you don’t need more than one Venture X card in the family to make this combo work.
Why it’s great: Outstanding earnings with a “free after rebate” annual fee; this is the only combo that offers the same great earnings internationally with no foreign transaction fees. The Venture X provides excellent features such as cell phone protection, airport lounge access, and more. Capital One also offers arguably the best collection of card-linked offers. Additionally, Capital One is the only bank that has largely eschewed the stratospheric annual-fee coupon book for an ultra-premium card. It offers solid value without the mental load.
Shortcomings: The only way to get better than 1 cent per “Mile” value is by transferring to airline and hotel partners. Fewer opportunities for multiple, blingy welcome offers than Chase or Amex. Transfer partner portfolio lags behind Amex, Bilt, Citi, and Chase.
Variations:
Swap Venture X for Venture Rewards: Lower the annual fee to $95 per year with the Venture Rewards card instead of Venture X. Both offer 2x everywhere earnings, no foreign transaction fees, and the ability to transfer to airline and hotel partners. However, the Venture Rewards card doesn’t offer annual rebates that offset the annual fee and doesn’t offer lounge access.
Make it fee-free: You can cobble together a decent combo with no annual fees (and still have no foreign transaction fees). Start with the Savor for 3x grocery, dining, and entertainment, and then add the fee-free Quicksilver card to get 1.5x everywhere else, and then move all that cash back to the fee-free VentureOne Rewards card in order to transfer “Miles” to airline and hotel partners.
4X flights and hotels booked directly (Sapphire Reserve)
3X dining (Sapphire Reserve)
3X drug store (Freedom Unlimited)
2X gas stations (Ink Cash)
1.5X everywhere else (Freedom Unlimited)
Perks include 1:1 transfers to Hyatt, lounge access, up to $300 in annual travel rebates, up to $300 in annual dining credits, up to $300 in annual StubHub credits, up to $500 in annual The Edit credits, no foreign transaction fees, and excellent travel protections.
FM Mini Review: Good all-around card for frequent traveler. Best when paired with no annual fee Chase Freedom Flex, Freedom Unlimited & Chase Ink Cash cards. Click here for our complete card review
$795 Annual Fee
Earning rate: 8X Chase Travel℠ ✦ 4X flights and hotels booked direct ✦ 3X Dining ✦ 5X Lyft (through September 2027)
Card Info: Visa Infinite issued by Chase. This card has no foreign currency conversion fees.
Big spend bonus: After spending $75,000 each calendar year, get the following benefits: IHG One Rewards Diamond Elite Status ✦ World of Hyatt Explorist Status ✦ Southwest Airlines A-List Status ✦ $500 Southwest Airlines credit when booked through Chase Travel ✦ $250 credit to The Shops at Chase
Noteworthy perks: $300 Annual Travel Credit ✦ Transfer points to airline & hotel partners ✦ Up to $500 The Edit credit annually ($250 twice per calendar year) ✦ Up to $300 Dining credit through Sapphire Reserve Exclusive Tables ($150 January to June and again July to December) ✦ Complimentary Apple TV and Apple Music for a minimum of one year when activated by 6/22/27 ✦ Up to $300 in StubHub credits ($150 January to June and again July to December) ✦ Points worth up to 2 cents each towards qualified bookings through Chase Travel ✦ Primary auto rental coverage ✦ Priority Pass Select lounge access ✦ Access Sapphire Lounges for yourself and 2 guests for free ✦ Access select Air Canada Maple Leaf lounges when flying Star Alliance ✦ Up to $120 Global Entry or TSA PreCheck® or NEXUS Application Fee Statement Credit ✦ IHG One Rewards Platinum status through 12/31/27 ✦ Free DoorDash DashPass through 2027 ✦ Two promos of $10 off each month on non-restaurant orders from DoorDash ✦ $15 off restaurant order each month from DoorDash ✦ $10 monthly Lyft credit
FM Mini Review: Great for 3X categories and 1.5X everywhere else. Excellent companion card to Sapphire Reserve®, Sapphire Preferred®, or Ink Business Preferred®. Click here for our complete card review
No Annual Fee
Earning rate: 5X travel booked through Chase Travel℠ ✦ 3X dining ✦ 3X drugstores ✦ 2% cash back total on qualifying Lyft products and services purchased through the Lyft mobile application through 09/30/2027 ✦ 1.5X everywhere else
FM Mini Review: This one should be in everyone’s wallet. Incredible welcome offer for a no-annual-fee card. Great card for 5X categories. Excellent companion card to Sapphire Reserve, Sapphire Preferred, or Ink Business Preferred. Click here for our complete card review
No Annual Fee
Earning rate: 5X office supplies and cellular/landline/cable (on up to $25,000 in total purchases in 5X categories annually) ✦ 2X on the first $25K in combined purchases at gas stations and restaurants each cardmember year ✦ 5x Lyft through September 2027
Card Info: Visa Signature Business issued by Chase. This card imposes foreign transaction fees.
Noteworthy perks: Complimentary Instacart+ for 3 months (must activate by 12/31/27) ✦ $20 monthly Instacart credit ✦ $10 off each month on one non-restaurant order from DoorDash
Combo details: Many of Chase’s no-annual-fee cards are advertised as cashback cards, but they actually earn Ultimate Rewards points. Once you have points in one of these accounts, you can move them to your Sapphire Reserve account to make them transferable. Chase lets you move points to another person in the same household, so it makes sense for a couple to earn points across a variety of Ultimate Rewards cards and then move them all to a single Sapphire Reserve account. The Sapphire Reserve card provides three ways to get good value from your points: 1) transfer to airline and hotel partners for high-value awards; 2) book through Chase Travel℠ using points boosts at a value of up to 2 cents per point; and 3) erase statement charges at 1.25 cents per point value against current Pay Yourself Back categories (see this post for details).
Why it’s great: This is the only combo listed here that offers 1:1 transfers to Hyatt, which can translate into incredible value. Points are also worth up to 2 cents each toward select bookings via Chase Travel℠, but only on bookings with points boosts, which is a limited subset. You can sometimes get even better value by transferring points to Chase’s high-value travel partners. The Sapphire Reserve offers excellent automatic travel protections…provided that you don’t live in New York.
Shortcomings: Requires three cards instead of two. The Sapphire Reserve card costs $795 per year, and the value you get from the array of rebates will vary from person to person. The Freedom Unlimited and Ink Business Cash cards charge foreign exchange fees, so you’ll want to use your Sapphire Reserve card when traveling outside of the US, at which point you’re only earning 1X everywhere. This is also the only combo in this roundup that doesn’t offer a standard grocery bonus and doesn’t have a 2X everywhere option.
Add-on: Consider adding the no-fee Chase Freedom Flex card, which offers rotating 5X categories.
Variation: You can lower annual fees to $95 per year by replacing the Sapphire Reserve with either the Sapphire Preferred® or the Ink Business Preferred®. Both let you transfer points to travel hotel and airline partners and still offer the expansive “travel” category bonus the Sapphire Reserve lost in the 2025 refresh. However, both also have a reduced 4:3 transfer ratio to World of Hyatt
FM Mini Review: Very strong earnings for spend. Excellent bonus categories. Points transferable to select airlines. Recommend pairing this card with Citi Double Cash Click here for our complete card review
$95 Annual Fee
Earning rate: 10X hotels, car rentals, and attractions booked through Citi Travel℠ ✦ 3X grocery ✦ 3X dining ✦ 3X gas stations & EV charging ✦ 3X flights, hotels, travel agencies ✦ 1x everywhere else
Card Info: Mastercard World Elite issued by Citi. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $100 Annual Hotel Savings Benefit ($100 off a $500+ hotel stay, excluding taxes and fees, when booked through Citi Travel) ✦ Travel protections
FM Mini Review: 2X rewards for all spend with no annual fee makes this card a winner. Earn 2X everywhere and redeem for the equivalent of 2% cash back or 2X ThankYou points. Pair with the Premier or Prestige card to make points transferrable to airlines. Click here for our complete card review
No Annual Fee
Earning rate: 2% cash back everywhere ✦ Earn 3% total cash back on hotel, car rentals, and attractions booked on Citi Travel℠ Portal
Combo details: Citi lets you pool ThankYou points across your cards to get the best possible redemption value. You can also transfer points to anyone, but once you do, you must use them within 90 days, or they’ll expire.
Why it’s great: Excellent point earnings, especially for a combo with a total $95 annual fee (the Strata Premier card costs $95 per year, while the other cards are free). Both provide free authorized user cards. Travel partners are an intriguing mix of airlines and hotels, with unique 1:1 options like American AAdvantage, EVA Air, and Japan Airlines.
Shortcomings: Citi no longer allows you to share points with other cardholders. It has also effectively discontinued options for earning more than 1 cent per point, outside of transferring points to partners, and has tanked the transfer ratios of its most valuable lodging partners. Earlier this year, Citi stopped accepting applications for the Custom Cash, removing the only option for 5X earning. Lastly, Citi offers somewhat lackluster travel protections compared with some of the other card combinations listed here.
FM Mini Review: This card offers a competitive flat 2% back on purchases and includes good cell phone insurance for a no annual fee card (up to $600 in protection with just a $25 deductible). Pair with a Wells Fargo Autograph or Autograph Journey card to make the rewards transferable to airline and hotel partners.
Card Info: Visa issued by Wells. This card imposes foreign transaction fees.
Combo details: Like Capital One, Wells Fargo lets you transfer cash rewards to the Autograph Journey card at a 1:1 ratio. This lets you transfer rewards earned on both cards to travel partners. Wells Fargo also lets you transfer as little as one point to a partner program, making it easy to avoid leaving orphaned rewards in a partner account.
Why it’s great: These cards offer excellent points earnings for a total $95 annual fee, not including the $50 yearly airfare credit that comes with the Autograph Journey. 5x at hotels is another unique feature of this combo. The cards offer decent travel and purchase protections, plus very good cell phone insurance.
Shortcomings: A big downside is that this combo has no grocery bonus, so the best that you can do is 2x with the Active Cash. While the Autograph Journey doesn’t have foreign transaction fees, the other two cards do, making it a one-card system when traveling (with a 1X floor). Wells Fargo’s collection of transfer partners is undoubtedly the weakest of all the programs we’re comparing. Currently, there are only eight, including the different Avios programs that effectively function as one. The only domestic airline is JetBlue, and the only hotel partners are Choice Privileges and Wyndham Rewards (both with an excellent 1:2 transfer ratio). If Wells Fargo can beef up its partner list to rival the other issuers listed here, this will become a much more delectable combo. Like Amex and Citibank, Wells Fargo no longer allows you to transfer points to other users.
Which is the best credit card combo?
So, which combo is best? It’s difficult to answer that question without understanding the needs of the person who’s asking. Any of these combos may be best for you, depending on your tolerance for annual fees, your spending patterns, and how you’re likely to use your rewards. Picking one “best” is harder than it’s ever been.
Bilt offers excellent value and earning potential, but you need a second participant to use multiple cards, and the high annual fees will be increasingly intrusive for those who sign up after 1/1/27 and don’t have a housing payment. Because one person can’t have more than one card, it’s hard to call this the best combo, and you can get plenty of value from the Palladium or Obsidian card on their own, especially if you have a monthly housing payment.
Getting 1:1 transfers to Hyatt is getting increasingly difficult…and expensive. With Bilt moving to a 4:3 ratio to Hyatt, the Chase combo becomes the only way to retain 1:1 Hyatt transfers, something that can be extended to additional household players because of Chase’s transfer policy. However, the $795 annual fee is the highest on this list, and it requires you to get significant value from the various coupons. That said, it’s less than $200 more than the Bilt “combo,” which is pretty amazing given how many more credits the Chase version offers.
I love the Citi combo because it offers probably the best all-around card listed here for category bonuses: the Strata Premier, which earns 3x at gas stations, grocery stores, restaurants, AND travel – all on one card. I can give player 2 (my wife) a Double Cash and the Strata Premier and know that she’s earning 2x everywhere and 3x at most of the places that she spends money. Citi has a great mix of airline partners, including American Airlines, EVA Air, and Japan Airlines. However, lodging has taken a big hit: Preferred Hotels is now 1:2, Choice is 1:1.5, and Leading Hotels of the World offers 25% more value through Amex (4:1 vs 5:1). Additionally, closing the Custom Cash to new applicants removes the ability to earn 5X in the category of your choice on $500/month in purchases.
For many folks, the Capital One Venture X + Savor combo will be best, because it only requires holding two cards and offers substantial rewards in popular categories (3x grocery, dining, and entertainment); strong rewards on all other spend (2x); no foreign transaction fees; and ultra-premium card features (airport lounge access and travel protections) all for “free after rebate” (spend $395, but get back $300 in travel credits and 10K points each year).
Final Thoughts
I have and use almost all of the cards listed above, but if I had to pick one “combo,” it would probably be Chase, surprisingly enough. Capital One would come in second by a hair. I’ve had great luck combining points boosts with my Edit credits to get excellent value; add in 1:1 transfers to Hyatt, and there are reasonable paths to get good value for both lodging and flights. I also like the earning potential, travel protections, and lounge access.
That’s a huge change from last year, when I had Citi number one, but after downgrading its lodging transfers, removing the Custom Cash card, and nixing the ability to move points to other cardholders, it’s lost enough appeal to no longer reign supreme. I also love my Bilt Palladium card and plan to keep it as long as I can keep the current earning regime, but as a combo, the need to have a second player, pay over $600 in annual fees, and accept sub-1:1 Hyatt transfers makes it tough to pick.
All of the combos listed here could be best, depending on the individual, and I could make an argument for any of them. In reality, I use a “multi-combo combo,” that combines several of them; that may be the best choice for others as well. If you do expand into multiple currencies, be careful to keep an eye on those annual fees to make sure you’re getting enough value out of your wallet to justify the expense.
Card Info: Amex Pay Over Time Card issued by Amex. This card has no foreign currency conversion fees.
Noteworthy perks: Up to $10 in statement credits monthly with participating dining partners (Grubhub (including Seamless), Buffalo Wild Wings, Five Guys, The Cheesecake Factory, and Wonder) ✦ $10 monthly Uber or Uber Eats credit (use it or lose it each month – must select Amex card as payment method to redeem) ✦ Up to $7 monthly Dunkin’ credit – enrollment required ✦ Up to $50 twice-annual Resy credit ✦ $100 hotel credit on qualifying charges on stays of 2 nights or longer, plus a room upgrade upon arrival, if available with The Hotel Collection at americanexpress.com/hc ✦ Complimentary Hertz Five Star® Status ✦ Enrollment required for select benefits.
FM Mini Review: 2X rewards for all eligible purchases (up to $50K per year) with no annual fee makes this card a winner. Click here for our complete card review
No Annual Fee
Earning rate: 2X Membership Rewards points on all eligible purchases, up to $50K spend per calendar year (then 1X thereafter). Terms apply. (Rates & Fees)
Card Info: Amex Credit Card issued by Amex. This card imposes foreign transaction fees.
Combo details: Amex automatically pools all your Membership Rewards points, even if you earned them with different cards. While you can’t move points from one person to another, you can transfer points to a friend’s airline or hotel program account if they are an authorized user (or employee) on one of your accounts.
Why it’s great: This combination delivers terrific earning potential (2X to 4X everywhere in the US!) and lets you transfer points to Amex’s valuable transfer Partners. Traditionally, Amex has offered more transfer bonuses than other issuers, though that has changed over the last year or so. For those who can use the Gold card’s $10/month dining, 2x$50 Resy credits, and $10/month Uber/Uber Eats credits, the $325 annual fee becomes easier to justify.
Shortcomings: Yearly limits and foreign travel. The Gold card’s 4X grocery bonus is capped at $25K in annual spend and is limited to stores in the US, while the 4X at restaurants is worldwide but capped at $50K/year. The Blue Business Plus card charges foreign transaction fees and limits the 2X bonus to $50K per year, making this a less desirable combo for those who spend big or for those looking for great rewards on spending outside of the United States…and since Amex often isn’t accepted outside of the United States, you’ll want a backup Visa or Mastercard when traveling anyway. This combo also requires a business card to earn 2x everywhere.
Add-on: There are several worthwhile cards to consider adding to this combo:
The Platinum Card® offers a compelling lineup of perks and boosts flight earnings to 5X. Unfortunately, it also adds an $895 annual fee.
Also worth looking at is the Schwab Platinum Card, which has many similar perks to the Business Platinum and lets you cash out points at 1.1 cents each (1 million points/year max).
+1X on up to $50K in purchases using accelerators ($25K on each card)
Double rewards on the first of the month (1,000 bonus points max)
Perks include: earn rewards on housing payments, earn 4% Bilt Cash per dollar, which you can redeem toward housing payments or credits, 2 x $200 hotel credit per year *this will change for cards approved 1/1/27 or later – read more here*
Earning rate: 4% Bilt Cash on everyday purchases if you choose Bilt Cash rather than housing-only rewards + 3X points on dining or grocery (Limit $25K per year for grocery) ✦ 2X points on travel ✦ 1X points on everyday purchases ✦ 0.5X-1.25X points on rent & mortgage payments (if Housing-Only Earnings selected) ✦ 1X points on rent & mortgage payments when redeeming Bilt Cash (if Bilt Cash earning option selected)
Card Info: Mastercard World Elite issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ Up to $100 in Bilt Travel hotel credits ($50 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments
Card Info: Mastercard World Legend issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $200 Bilt Cash annually ✦ Up to $400 in Bilt Travel hotel credits ($200 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments ✦ Priority Pass (excludes restaurants)
Combo details: First off, Bilt only lets you have one Bilt card, so this combo is only possible if you have a 2nd player in the household that can add you as an authorized user (AU) to the second card. Bilt is unique in that it lets AU cards earn points and Bilt Cash to the AU’s account, so you can capture the earning categories (and accelerators) on both, but it also adds an additional fee of $50 for the Obsidian or $95 for the Palladium.
Why it’s great: This is another combo that offers excellent earning potential (2X to 4X everywhere), and Bilt has what most folks consider the best portfolio of transfer partners. It offers several 50%-100% Rent Day transfer bonuses per year that can deliver incredible value when transferring points. Using accelerators turns the Palladium card into a 3X everywhere earner, or even more if you’re also earning points on housing payments.
Shortcomings: First, you need two people to do it. Bilt doesn’t allow one person to be the primary cardholder on two cards. In addition, unlike many premium cards, there aren’t many included coupons, outside of 2 X $200 hotel credits on the Palladium and a $50 credit on the Obsidian, all of which require a two-night minimum and booking through Bilt’s travel portal. The earnings are great, but don’t forget that you’re still paying $600+ per year for them without the clear offsets of other cards. Starting 1/1/27, Bilt will lose 1:1 access to Hyatt, even with the Palladium card, which will be a big blow to the partner portfolio. Lastly, a third version of Bilt will take effect on January 1st, which represents a significant hit to earning power for folks who don’t earn points on housing payments.
Variation: Instead of incorporating the Obsidian card, you could use one Palladium card with an authorized user card that earns to the primary account. That setup would cost $590/year, but give you a total of $50K worth of 3X everywhere via accelerators. A downside is that AU card spend wouldn’t count toward elite status for the primary cardholder.
FM Mini Review: This card offers annual rebates that easily mitigate the fee for those who travel often. The card earns 2 miles per dollar on most purchases just like the Capital One Venture Rewards card, which are worth exactly 1 cent each toward travel. This makes the return on most spend similar to a 2% cash back card (though in this case you must redeem your miles to offset travel in order to get 1 cent per mile). One huge advantage over cash back: Capital One allows transfering their miles to airline miles & hotel points. Click here for our complete card review
$395 Annual Fee
Earning rate: 10X miles on hotels and rental cars booked via Capital One Travel ✦ 5X miles on flights and vacation rentals booked via Capital One travel ✦ 5X miles on Capital One Entertainment ✦ 2X miles everywhere else
Card Info: Visa Infinite issued by CapOne. This card has no foreign currency conversion fees.
Noteworthy perks: $300 annual credit for bookings made through Capital One Travel ✦ 10,000 bonus miles each year starting at first anniversary ✦ Up to $120 application fee credit for Global Entry or TSA PreCheck® ✦ Access to Capital One Lounge and Landing locations ✦ Priority Pass membership (participating lounges only) after enrollment ✦ Cell phone insurance ✦ Trip insurance ✦ Primary CDW coverage ✦ Redeem miles for travel at value of 1 cent per mile ✦ Transfer Miles to airline miles & hotel points
Earning rate: 8% cash back on Capital One Entertainment purchases ✦ 5% on hotels, vacation rentals, and rental cars booked via Capital One Travel (terms apply) ✦ 3% on dining, entertainment, select streaming services, and purchases at grocery stores (excluding superstores like Walmart® and Target®) ✦ 1% everywhere else
Base: 1%
Portal Hotels: 5%
Grocery: 3%
Dine: 3%
Card Info: Mastercard issued by CapOne. This card has no foreign currency conversion fees.
Combo details: Even though the Venture X has a $395 annual fee, you could consider this combo “almost free” after rebates, since it offers $300 in yearly Capital One Travel rebates plus 10K points each card anniversary, which together more than offset the annual fee. The fee-free Savor Cash Rewards adds 3x grocery, dining, and entertainment to the already strong 2x everywhere earnings offered by Venture X. Capital One lets you move cash back rewards to a “miles” card so that they then become transferable to partners. This allows you to earn 3% cash back with the Savor card and then convert that to “miles” by moving it to the Venture X card, unlocking better value by transferring to partners for high-value awards. You can also freely move points to anyone, so you don’t need more than one Venture X card in the family to make this combo work.
Why it’s great: Outstanding earnings with a “free after rebate” annual fee; this is the only combo that offers the same great earnings internationally with no foreign transaction fees. The Venture X provides excellent features such as cell phone protection, airport lounge access, and more. Capital One also offers arguably the best collection of card-linked offers. Additionally, Capital One is the only bank that has largely eschewed the stratospheric annual-fee coupon book for an ultra-premium card. It offers solid value without the mental load.
Shortcomings: The only way to get better than 1 cent per “Mile” value is by transferring to airline and hotel partners. Fewer opportunities for multiple, blingy welcome offers than Chase or Amex. Transfer partner portfolio lags behind Amex, Bilt, Citi, and Chase.
Variations:
Swap Venture X for Venture Rewards: Lower the annual fee to $95 per year with the Venture Rewards card instead of Venture X. Both offer 2x everywhere earnings, no foreign transaction fees, and the ability to transfer to airline and hotel partners. However, the Venture Rewards card doesn’t offer annual rebates that offset the annual fee and doesn’t offer lounge access.
Make it fee-free: You can cobble together a decent combo with no annual fees (and still have no foreign transaction fees). Start with the Savor for 3x grocery, dining, and entertainment, and then add the fee-free Quicksilver card to get 1.5x everywhere else, and then move all that cash back to the fee-free VentureOne Rewards card in order to transfer “Miles” to airline and hotel partners.
4X flights and hotels booked directly (Sapphire Reserve)
3X dining (Sapphire Reserve)
3X drug store (Freedom Unlimited)
2X gas stations (Ink Cash)
1.5X everywhere else (Freedom Unlimited)
Perks include 1:1 transfers to Hyatt, lounge access, up to $300 in annual travel rebates, up to $300 in annual dining credits, up to $300 in annual StubHub credits, up to $500 in annual The Edit credits, no foreign transaction fees, and excellent travel protections.
FM Mini Review: Good all-around card for frequent traveler. Best when paired with no annual fee Chase Freedom Flex, Freedom Unlimited & Chase Ink Cash cards. Click here for our complete card review
$795 Annual Fee
Earning rate: 8X Chase Travel℠ ✦ 4X flights and hotels booked direct ✦ 3X Dining ✦ 5X Lyft (through September 2027)
Card Info: Visa Infinite issued by Chase. This card has no foreign currency conversion fees.
Big spend bonus: After spending $75,000 each calendar year, get the following benefits: IHG One Rewards Diamond Elite Status ✦ World of Hyatt Explorist Status ✦ Southwest Airlines A-List Status ✦ $500 Southwest Airlines credit when booked through Chase Travel ✦ $250 credit to The Shops at Chase
Noteworthy perks: $300 Annual Travel Credit ✦ Transfer points to airline & hotel partners ✦ Up to $500 The Edit credit annually ($250 twice per calendar year) ✦ Up to $300 Dining credit through Sapphire Reserve Exclusive Tables ($150 January to June and again July to December) ✦ Complimentary Apple TV and Apple Music for a minimum of one year when activated by 6/22/27 ✦ Up to $300 in StubHub credits ($150 January to June and again July to December) ✦ Points worth up to 2 cents each towards qualified bookings through Chase Travel ✦ Primary auto rental coverage ✦ Priority Pass Select lounge access ✦ Access Sapphire Lounges for yourself and 2 guests for free ✦ Access select Air Canada Maple Leaf lounges when flying Star Alliance ✦ Up to $120 Global Entry or TSA PreCheck® or NEXUS Application Fee Statement Credit ✦ IHG One Rewards Platinum status through 12/31/27 ✦ Free DoorDash DashPass through 2027 ✦ Two promos of $10 off each month on non-restaurant orders from DoorDash ✦ $15 off restaurant order each month from DoorDash ✦ $10 monthly Lyft credit
FM Mini Review: Great for 3X categories and 1.5X everywhere else. Excellent companion card to Sapphire Reserve®, Sapphire Preferred®, or Ink Business Preferred®. Click here for our complete card review
No Annual Fee
Earning rate: 5X travel booked through Chase Travel℠ ✦ 3X dining ✦ 3X drugstores ✦ 2% cash back total on qualifying Lyft products and services purchased through the Lyft mobile application through 09/30/2027 ✦ 1.5X everywhere else
FM Mini Review: This one should be in everyone’s wallet. Incredible welcome offer for a no-annual-fee card. Great card for 5X categories. Excellent companion card to Sapphire Reserve, Sapphire Preferred, or Ink Business Preferred. Click here for our complete card review
No Annual Fee
Earning rate: 5X office supplies and cellular/landline/cable (on up to $25,000 in total purchases in 5X categories annually) ✦ 2X on the first $25K in combined purchases at gas stations and restaurants each cardmember year ✦ 5x Lyft through September 2027
Card Info: Visa Signature Business issued by Chase. This card imposes foreign transaction fees.
Noteworthy perks: Complimentary Instacart+ for 3 months (must activate by 12/31/27) ✦ $20 monthly Instacart credit ✦ $10 off each month on one non-restaurant order from DoorDash
Combo details: Many of Chase’s no-annual-fee cards are advertised as cashback cards, but they actually earn Ultimate Rewards points. Once you have points in one of these accounts, you can move them to your Sapphire Reserve account to make them transferable. Chase lets you move points to another person in the same household, so it makes sense for a couple to earn points across a variety of Ultimate Rewards cards and then move them all to a single Sapphire Reserve account. The Sapphire Reserve card provides three ways to get good value from your points: 1) transfer to airline and hotel partners for high-value awards; 2) book through Chase Travel℠ using points boosts at a value of up to 2 cents per point; and 3) erase statement charges at 1.25 cents per point value against current Pay Yourself Back categories (see this post for details).
Why it’s great: This is the only combo listed here that offers 1:1 transfers to Hyatt, which can translate into incredible value. Points are also worth up to 2 cents each toward select bookings via Chase Travel℠, but only on bookings with points boosts, which is a limited subset. You can sometimes get even better value by transferring points to Chase’s high-value travel partners. The Sapphire Reserve offers excellent automatic travel protections…provided that you don’t live in New York.
Shortcomings: Requires three cards instead of two. The Sapphire Reserve card costs $795 per year, and the value you get from the array of rebates will vary from person to person. The Freedom Unlimited and Ink Business Cash cards charge foreign exchange fees, so you’ll want to use your Sapphire Reserve card when traveling outside of the US, at which point you’re only earning 1X everywhere. This is also the only combo in this roundup that doesn’t offer a standard grocery bonus and doesn’t have a 2X everywhere option.
Add-on: Consider adding the no-fee Chase Freedom Flex card, which offers rotating 5X categories.
Variation: You can lower annual fees to $95 per year by replacing the Sapphire Reserve with either the Sapphire Preferred® or the Ink Business Preferred®. Both let you transfer points to travel hotel and airline partners and still offer the expansive “travel” category bonus the Sapphire Reserve lost in the 2025 refresh. However, both also have a reduced 4:3 transfer ratio to World of Hyatt
FM Mini Review: Very strong earnings for spend. Excellent bonus categories. Points transferable to select airlines. Recommend pairing this card with Citi Double Cash Click here for our complete card review
$95 Annual Fee
Earning rate: 10X hotels, car rentals, and attractions booked through Citi Travel℠ ✦ 3X grocery ✦ 3X dining ✦ 3X gas stations & EV charging ✦ 3X flights, hotels, travel agencies ✦ 1x everywhere else
Card Info: Mastercard World Elite issued by Citi. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $100 Annual Hotel Savings Benefit ($100 off a $500+ hotel stay, excluding taxes and fees, when booked through Citi Travel) ✦ Travel protections
FM Mini Review: 2X rewards for all spend with no annual fee makes this card a winner. Earn 2X everywhere and redeem for the equivalent of 2% cash back or 2X ThankYou points. Pair with the Premier or Prestige card to make points transferrable to airlines. Click here for our complete card review
No Annual Fee
Earning rate: 2% cash back everywhere ✦ Earn 3% total cash back on hotel, car rentals, and attractions booked on Citi Travel℠ Portal
Combo details: Citi lets you pool ThankYou points across your cards to get the best possible redemption value. You can also transfer points to anyone, but once you do, you must use them within 90 days, or they’ll expire.
Why it’s great: Excellent point earnings, especially for a combo with a total $95 annual fee (the Strata Premier card costs $95 per year, while the other cards are free). Both provide free authorized user cards. Travel partners are an intriguing mix of airlines and hotels, with unique 1:1 options like American AAdvantage, EVA Air, and Japan Airlines.
Shortcomings: Citi no longer allows you to share points with other cardholders. It has also effectively discontinued options for earning more than 1 cent per point, outside of transferring points to partners, and has tanked the transfer ratios of its most valuable lodging partners. Earlier this year, Citi stopped accepting applications for the Custom Cash, removing the only option for 5X earning. Lastly, Citi offers somewhat lackluster travel protections compared with some of the other card combinations listed here.
FM Mini Review: This card offers a competitive flat 2% back on purchases and includes good cell phone insurance for a no annual fee card (up to $600 in protection with just a $25 deductible). Pair with a Wells Fargo Autograph or Autograph Journey card to make the rewards transferable to airline and hotel partners.
Card Info: Visa issued by Wells. This card imposes foreign transaction fees.
Combo details: Like Capital One, Wells Fargo lets you transfer cash rewards to the Autograph Journey card at a 1:1 ratio. This lets you transfer rewards earned on both cards to travel partners. Wells Fargo also lets you transfer as little as one point to a partner program, making it easy to avoid leaving orphaned rewards in a partner account.
Why it’s great: These cards offer excellent points earnings for a total $95 annual fee, not including the $50 yearly airfare credit that comes with the Autograph Journey. 5x at hotels is another unique feature of this combo. The cards offer decent travel and purchase protections, plus very good cell phone insurance.
Shortcomings: A big downside is that this combo has no grocery bonus, so the best that you can do is 2x with the Active Cash. While the Autograph Journey doesn’t have foreign transaction fees, the other two cards do, making it a one-card system when traveling (with a 1X floor). Wells Fargo’s collection of transfer partners is undoubtedly the weakest of all the programs we’re comparing. Currently, there are only eight, including the different Avios programs that effectively function as one. The only domestic airline is JetBlue, and the only hotel partners are Choice Privileges and Wyndham Rewards (both with an excellent 1:2 transfer ratio). If Wells Fargo can beef up its partner list to rival the other issuers listed here, this will become a much more delectable combo. Like Amex and Citibank, Wells Fargo no longer allows you to transfer points to other users.
Which is the best credit card combo?
So, which combo is best? It’s difficult to answer that question without understanding the needs of the person who’s asking. Any of these combos may be best for you, depending on your tolerance for annual fees, your spending patterns, and how you’re likely to use your rewards. Picking one “best” is harder than it’s ever been.
Bilt offers excellent value and earning potential, but you need a second participant to use multiple cards, and the high annual fees will be increasingly intrusive for those who sign up after 1/1/27 and don’t have a housing payment. Because one person can’t have more than one card, it’s hard to call this the best combo, and you can get plenty of value from the Palladium or Obsidian card on their own, especially if you have a monthly housing payment.
Getting 1:1 transfers to Hyatt is getting increasingly difficult…and expensive. With Bilt moving to a 4:3 ratio to Hyatt, the Chase combo becomes the only way to retain 1:1 Hyatt transfers, something that can be extended to additional household players because of Chase’s transfer policy. However, the $795 annual fee is the highest on this list, and it requires you to get significant value from the various coupons. That said, it’s less than $200 more than the Bilt “combo,” which is pretty amazing given how many more credits the Chase version offers.
I love the Citi combo because it offers probably the best all-around card listed here for category bonuses: the Strata Premier, which earns 3x at gas stations, grocery stores, restaurants, AND travel – all on one card. I can give player 2 (my wife) a Double Cash and the Strata Premier and know that she’s earning 2x everywhere and 3x at most of the places that she spends money. Citi has a great mix of airline partners, including American Airlines, EVA Air, and Japan Airlines. However, lodging has taken a big hit: Preferred Hotels is now 1:2, Choice is 1:1.5, and Leading Hotels of the World offers 25% more value through Amex (4:1 vs 5:1). Additionally, closing the Custom Cash to new applicants removes the ability to earn 5X in the category of your choice on $500/month in purchases.
For many folks, the Capital One Venture X + Savor combo will be best, because it only requires holding two cards and offers substantial rewards in popular categories (3x grocery, dining, and entertainment); strong rewards on all other spend (2x); no foreign transaction fees; and ultra-premium card features (airport lounge access and travel protections) all for “free after rebate” (spend $395, but get back $300 in travel credits and 10K points each year).
Final Thoughts
I have and use almost all of the cards listed above, but if I had to pick one “combo,” it would probably be Chase, surprisingly enough. Capital One would come in second by a hair. I’ve had great luck combining points boosts with my Edit credits to get excellent value; add in 1:1 transfers to Hyatt, and there are reasonable paths to get good value for both lodging and flights. I also like the earning potential, travel protections, and lounge access.
That’s a huge change from last year, when I had Citi number one, but after downgrading its lodging transfers, removing the Custom Cash card, and nixing the ability to move points to other cardholders, it’s lost enough appeal to no longer reign supreme. I also love my Bilt Palladium card and plan to keep it as long as I can keep the current earning regime, but as a combo, the need to have a second player, pay over $600 in annual fees, and accept sub-1:1 Hyatt transfers makes it tough to pick.
All of the combos listed here could be best, depending on the individual, and I could make an argument for any of them. In reality, I use a “multi-combo combo,” that combines several of them; that may be the best choice for others as well. If you do expand into multiple currencies, be careful to keep an eye on those annual fees to make sure you’re getting enough value out of your wallet to justify the expense.
Card Info: Amex Pay Over Time Card issued by Amex. This card has no foreign currency conversion fees.
Noteworthy perks: Up to $10 in statement credits monthly with participating dining partners (Grubhub (including Seamless), Buffalo Wild Wings, Five Guys, The Cheesecake Factory, and Wonder) ✦ $10 monthly Uber or Uber Eats credit (use it or lose it each month – must select Amex card as payment method to redeem) ✦ Up to $7 monthly Dunkin’ credit – enrollment required ✦ Up to $50 twice-annual Resy credit ✦ $100 hotel credit on qualifying charges on stays of 2 nights or longer, plus a room upgrade upon arrival, if available with The Hotel Collection at americanexpress.com/hc ✦ Complimentary Hertz Five Star® Status ✦ Enrollment required for select benefits.
FM Mini Review: 2X rewards for all eligible purchases (up to $50K per year) with no annual fee makes this card a winner. Click here for our complete card review
No Annual Fee
Earning rate: 2X Membership Rewards points on all eligible purchases, up to $50K spend per calendar year (then 1X thereafter). Terms apply. (Rates & Fees)
Card Info: Amex Credit Card issued by Amex. This card imposes foreign transaction fees.
Combo details: Amex automatically pools all your Membership Rewards points, even if you earned them with different cards. While you can’t move points from one person to another, you can transfer points to a friend’s airline or hotel program account if they are an authorized user (or employee) on one of your accounts.
Why it’s great: This combination delivers terrific earning potential (2X to 4X everywhere in the US!) and lets you transfer points to Amex’s valuable transfer Partners. Traditionally, Amex has offered more transfer bonuses than other issuers, though that has changed over the last year or so. For those who can use the Gold card’s $10/month dining, 2x$50 Resy credits, and $10/month Uber/Uber Eats credits, the $325 annual fee becomes easier to justify.
Shortcomings: Yearly limits and foreign travel. The Gold card’s 4X grocery bonus is capped at $25K in annual spend and is limited to stores in the US, while the 4X at restaurants is worldwide but capped at $50K/year. The Blue Business Plus card charges foreign transaction fees and limits the 2X bonus to $50K per year, making this a less desirable combo for those who spend big or for those looking for great rewards on spending outside of the United States…and since Amex often isn’t accepted outside of the United States, you’ll want a backup Visa or Mastercard when traveling anyway. This combo also requires a business card to earn 2x everywhere.
Add-on: There are several worthwhile cards to consider adding to this combo:
The Platinum Card® offers a compelling lineup of perks and boosts flight earnings to 5X. Unfortunately, it also adds an $895 annual fee.
Also worth looking at is the Schwab Platinum Card, which has many similar perks to the Business Platinum and lets you cash out points at 1.1 cents each (1 million points/year max).
+1X on up to $50K in purchases using accelerators ($25K on each card)
Double rewards on the first of the month (1,000 bonus points max)
Perks include: earn rewards on housing payments, earn 4% Bilt Cash per dollar, which you can redeem toward housing payments or credits, 2 x $200 hotel credit per year *this will change for cards approved 1/1/27 or later – read more here*
Earning rate: 4% Bilt Cash on everyday purchases if you choose Bilt Cash rather than housing-only rewards + 3X points on dining or grocery (Limit $25K per year for grocery) ✦ 2X points on travel ✦ 1X points on everyday purchases ✦ 0.5X-1.25X points on rent & mortgage payments (if Housing-Only Earnings selected) ✦ 1X points on rent & mortgage payments when redeeming Bilt Cash (if Bilt Cash earning option selected)
Card Info: Mastercard World Elite issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ Up to $100 in Bilt Travel hotel credits ($50 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments
Card Info: Mastercard World Legend issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $200 Bilt Cash annually ✦ Up to $400 in Bilt Travel hotel credits ($200 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments ✦ Priority Pass (excludes restaurants)
Combo details: First off, Bilt only lets you have one Bilt card, so this combo is only possible if you have a 2nd player in the household that can add you as an authorized user (AU) to the second card. Bilt is unique in that it lets AU cards earn points and Bilt Cash to the AU’s account, so you can capture the earning categories (and accelerators) on both, but it also adds an additional fee of $50 for the Obsidian or $95 for the Palladium.
Why it’s great: This is another combo that offers excellent earning potential (2X to 4X everywhere), and Bilt has what most folks consider the best portfolio of transfer partners. It offers several 50%-100% Rent Day transfer bonuses per year that can deliver incredible value when transferring points. Using accelerators turns the Palladium card into a 3X everywhere earner, or even more if you’re also earning points on housing payments.
Shortcomings: First, you need two people to do it. Bilt doesn’t allow one person to be the primary cardholder on two cards. In addition, unlike many premium cards, there aren’t many included coupons, outside of 2 X $200 hotel credits on the Palladium and a $50 credit on the Obsidian, all of which require a two-night minimum and booking through Bilt’s travel portal. The earnings are great, but don’t forget that you’re still paying $600+ per year for them without the clear offsets of other cards. Starting 1/1/27, Bilt will lose 1:1 access to Hyatt, even with the Palladium card, which will be a big blow to the partner portfolio. Lastly, a third version of Bilt will take effect on January 1st, which represents a significant hit to earning power for folks who don’t earn points on housing payments.
Variation: Instead of incorporating the Obsidian card, you could use one Palladium card with an authorized user card that earns to the primary account. That setup would cost $590/year, but give you a total of $50K worth of 3X everywhere via accelerators. A downside is that AU card spend wouldn’t count toward elite status for the primary cardholder.
FM Mini Review: This card offers annual rebates that easily mitigate the fee for those who travel often. The card earns 2 miles per dollar on most purchases just like the Capital One Venture Rewards card, which are worth exactly 1 cent each toward travel. This makes the return on most spend similar to a 2% cash back card (though in this case you must redeem your miles to offset travel in order to get 1 cent per mile). One huge advantage over cash back: Capital One allows transfering their miles to airline miles & hotel points. Click here for our complete card review
$395 Annual Fee
Earning rate: 10X miles on hotels and rental cars booked via Capital One Travel ✦ 5X miles on flights and vacation rentals booked via Capital One travel ✦ 5X miles on Capital One Entertainment ✦ 2X miles everywhere else
Card Info: Visa Infinite issued by CapOne. This card has no foreign currency conversion fees.
Noteworthy perks: $300 annual credit for bookings made through Capital One Travel ✦ 10,000 bonus miles each year starting at first anniversary ✦ Up to $120 application fee credit for Global Entry or TSA PreCheck® ✦ Access to Capital One Lounge and Landing locations ✦ Priority Pass membership (participating lounges only) after enrollment ✦ Cell phone insurance ✦ Trip insurance ✦ Primary CDW coverage ✦ Redeem miles for travel at value of 1 cent per mile ✦ Transfer Miles to airline miles & hotel points
Earning rate: 8% cash back on Capital One Entertainment purchases ✦ 5% on hotels, vacation rentals, and rental cars booked via Capital One Travel (terms apply) ✦ 3% on dining, entertainment, select streaming services, and purchases at grocery stores (excluding superstores like Walmart® and Target®) ✦ 1% everywhere else
Base: 1%
Portal Hotels: 5%
Grocery: 3%
Dine: 3%
Card Info: Mastercard issued by CapOne. This card has no foreign currency conversion fees.
Combo details: Even though the Venture X has a $395 annual fee, you could consider this combo “almost free” after rebates, since it offers $300 in yearly Capital One Travel rebates plus 10K points each card anniversary, which together more than offset the annual fee. The fee-free Savor Cash Rewards adds 3x grocery, dining, and entertainment to the already strong 2x everywhere earnings offered by Venture X. Capital One lets you move cash back rewards to a “miles” card so that they then become transferable to partners. This allows you to earn 3% cash back with the Savor card and then convert that to “miles” by moving it to the Venture X card, unlocking better value by transferring to partners for high-value awards. You can also freely move points to anyone, so you don’t need more than one Venture X card in the family to make this combo work.
Why it’s great: Outstanding earnings with a “free after rebate” annual fee; this is the only combo that offers the same great earnings internationally with no foreign transaction fees. The Venture X provides excellent features such as cell phone protection, airport lounge access, and more. Capital One also offers arguably the best collection of card-linked offers. Additionally, Capital One is the only bank that has largely eschewed the stratospheric annual-fee coupon book for an ultra-premium card. It offers solid value without the mental load.
Shortcomings: The only way to get better than 1 cent per “Mile” value is by transferring to airline and hotel partners. Fewer opportunities for multiple, blingy welcome offers than Chase or Amex. Transfer partner portfolio lags behind Amex, Bilt, Citi, and Chase.
Variations:
Swap Venture X for Venture Rewards: Lower the annual fee to $95 per year with the Venture Rewards card instead of Venture X. Both offer 2x everywhere earnings, no foreign transaction fees, and the ability to transfer to airline and hotel partners. However, the Venture Rewards card doesn’t offer annual rebates that offset the annual fee and doesn’t offer lounge access.
Make it fee-free: You can cobble together a decent combo with no annual fees (and still have no foreign transaction fees). Start with the Savor for 3x grocery, dining, and entertainment, and then add the fee-free Quicksilver card to get 1.5x everywhere else, and then move all that cash back to the fee-free VentureOne Rewards card in order to transfer “Miles” to airline and hotel partners.
4X flights and hotels booked directly (Sapphire Reserve)
3X dining (Sapphire Reserve)
3X drug store (Freedom Unlimited)
2X gas stations (Ink Cash)
1.5X everywhere else (Freedom Unlimited)
Perks include 1:1 transfers to Hyatt, lounge access, up to $300 in annual travel rebates, up to $300 in annual dining credits, up to $300 in annual StubHub credits, up to $500 in annual The Edit credits, no foreign transaction fees, and excellent travel protections.
FM Mini Review: Good all-around card for frequent traveler. Best when paired with no annual fee Chase Freedom Flex, Freedom Unlimited & Chase Ink Cash cards. Click here for our complete card review
$795 Annual Fee
Earning rate: 8X Chase Travel℠ ✦ 4X flights and hotels booked direct ✦ 3X Dining ✦ 5X Lyft (through September 2027)
Card Info: Visa Infinite issued by Chase. This card has no foreign currency conversion fees.
Big spend bonus: After spending $75,000 each calendar year, get the following benefits: IHG One Rewards Diamond Elite Status ✦ World of Hyatt Explorist Status ✦ Southwest Airlines A-List Status ✦ $500 Southwest Airlines credit when booked through Chase Travel ✦ $250 credit to The Shops at Chase
Noteworthy perks: $300 Annual Travel Credit ✦ Transfer points to airline & hotel partners ✦ Up to $500 The Edit credit annually ($250 twice per calendar year) ✦ Up to $300 Dining credit through Sapphire Reserve Exclusive Tables ($150 January to June and again July to December) ✦ Complimentary Apple TV and Apple Music for a minimum of one year when activated by 6/22/27 ✦ Up to $300 in StubHub credits ($150 January to June and again July to December) ✦ Points worth up to 2 cents each towards qualified bookings through Chase Travel ✦ Primary auto rental coverage ✦ Priority Pass Select lounge access ✦ Access Sapphire Lounges for yourself and 2 guests for free ✦ Access select Air Canada Maple Leaf lounges when flying Star Alliance ✦ Up to $120 Global Entry or TSA PreCheck® or NEXUS Application Fee Statement Credit ✦ IHG One Rewards Platinum status through 12/31/27 ✦ Free DoorDash DashPass through 2027 ✦ Two promos of $10 off each month on non-restaurant orders from DoorDash ✦ $15 off restaurant order each month from DoorDash ✦ $10 monthly Lyft credit
FM Mini Review: Great for 3X categories and 1.5X everywhere else. Excellent companion card to Sapphire Reserve®, Sapphire Preferred®, or Ink Business Preferred®. Click here for our complete card review
No Annual Fee
Earning rate: 5X travel booked through Chase Travel℠ ✦ 3X dining ✦ 3X drugstores ✦ 2% cash back total on qualifying Lyft products and services purchased through the Lyft mobile application through 09/30/2027 ✦ 1.5X everywhere else
FM Mini Review: This one should be in everyone’s wallet. Incredible welcome offer for a no-annual-fee card. Great card for 5X categories. Excellent companion card to Sapphire Reserve, Sapphire Preferred, or Ink Business Preferred. Click here for our complete card review
No Annual Fee
Earning rate: 5X office supplies and cellular/landline/cable (on up to $25,000 in total purchases in 5X categories annually) ✦ 2X on the first $25K in combined purchases at gas stations and restaurants each cardmember year ✦ 5x Lyft through September 2027
Card Info: Visa Signature Business issued by Chase. This card imposes foreign transaction fees.
Noteworthy perks: Complimentary Instacart+ for 3 months (must activate by 12/31/27) ✦ $20 monthly Instacart credit ✦ $10 off each month on one non-restaurant order from DoorDash
Combo details: Many of Chase’s no-annual-fee cards are advertised as cashback cards, but they actually earn Ultimate Rewards points. Once you have points in one of these accounts, you can move them to your Sapphire Reserve account to make them transferable. Chase lets you move points to another person in the same household, so it makes sense for a couple to earn points across a variety of Ultimate Rewards cards and then move them all to a single Sapphire Reserve account. The Sapphire Reserve card provides three ways to get good value from your points: 1) transfer to airline and hotel partners for high-value awards; 2) book through Chase Travel℠ using points boosts at a value of up to 2 cents per point; and 3) erase statement charges at 1.25 cents per point value against current Pay Yourself Back categories (see this post for details).
Why it’s great: This is the only combo listed here that offers 1:1 transfers to Hyatt, which can translate into incredible value. Points are also worth up to 2 cents each toward select bookings via Chase Travel℠, but only on bookings with points boosts, which is a limited subset. You can sometimes get even better value by transferring points to Chase’s high-value travel partners. The Sapphire Reserve offers excellent automatic travel protections…provided that you don’t live in New York.
Shortcomings: Requires three cards instead of two. The Sapphire Reserve card costs $795 per year, and the value you get from the array of rebates will vary from person to person. The Freedom Unlimited and Ink Business Cash cards charge foreign exchange fees, so you’ll want to use your Sapphire Reserve card when traveling outside of the US, at which point you’re only earning 1X everywhere. This is also the only combo in this roundup that doesn’t offer a standard grocery bonus and doesn’t have a 2X everywhere option.
Add-on: Consider adding the no-fee Chase Freedom Flex card, which offers rotating 5X categories.
Variation: You can lower annual fees to $95 per year by replacing the Sapphire Reserve with either the Sapphire Preferred® or the Ink Business Preferred®. Both let you transfer points to travel hotel and airline partners and still offer the expansive “travel” category bonus the Sapphire Reserve lost in the 2025 refresh. However, both also have a reduced 4:3 transfer ratio to World of Hyatt
FM Mini Review: Very strong earnings for spend. Excellent bonus categories. Points transferable to select airlines. Recommend pairing this card with Citi Double Cash Click here for our complete card review
$95 Annual Fee
Earning rate: 10X hotels, car rentals, and attractions booked through Citi Travel℠ ✦ 3X grocery ✦ 3X dining ✦ 3X gas stations & EV charging ✦ 3X flights, hotels, travel agencies ✦ 1x everywhere else
Card Info: Mastercard World Elite issued by Citi. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $100 Annual Hotel Savings Benefit ($100 off a $500+ hotel stay, excluding taxes and fees, when booked through Citi Travel) ✦ Travel protections
FM Mini Review: 2X rewards for all spend with no annual fee makes this card a winner. Earn 2X everywhere and redeem for the equivalent of 2% cash back or 2X ThankYou points. Pair with the Premier or Prestige card to make points transferrable to airlines. Click here for our complete card review
No Annual Fee
Earning rate: 2% cash back everywhere ✦ Earn 3% total cash back on hotel, car rentals, and attractions booked on Citi Travel℠ Portal
Combo details: Citi lets you pool ThankYou points across your cards to get the best possible redemption value. You can also transfer points to anyone, but once you do, you must use them within 90 days, or they’ll expire.
Why it’s great: Excellent point earnings, especially for a combo with a total $95 annual fee (the Strata Premier card costs $95 per year, while the other cards are free). Both provide free authorized user cards. Travel partners are an intriguing mix of airlines and hotels, with unique 1:1 options like American AAdvantage, EVA Air, and Japan Airlines.
Shortcomings: Citi no longer allows you to share points with other cardholders. It has also effectively discontinued options for earning more than 1 cent per point, outside of transferring points to partners, and has tanked the transfer ratios of its most valuable lodging partners. Earlier this year, Citi stopped accepting applications for the Custom Cash, removing the only option for 5X earning. Lastly, Citi offers somewhat lackluster travel protections compared with some of the other card combinations listed here.
FM Mini Review: This card offers a competitive flat 2% back on purchases and includes good cell phone insurance for a no annual fee card (up to $600 in protection with just a $25 deductible). Pair with a Wells Fargo Autograph or Autograph Journey card to make the rewards transferable to airline and hotel partners.
Card Info: Visa issued by Wells. This card imposes foreign transaction fees.
Combo details: Like Capital One, Wells Fargo lets you transfer cash rewards to the Autograph Journey card at a 1:1 ratio. This lets you transfer rewards earned on both cards to travel partners. Wells Fargo also lets you transfer as little as one point to a partner program, making it easy to avoid leaving orphaned rewards in a partner account.
Why it’s great: These cards offer excellent points earnings for a total $95 annual fee, not including the $50 yearly airfare credit that comes with the Autograph Journey. 5x at hotels is another unique feature of this combo. The cards offer decent travel and purchase protections, plus very good cell phone insurance.
Shortcomings: A big downside is that this combo has no grocery bonus, so the best that you can do is 2x with the Active Cash. While the Autograph Journey doesn’t have foreign transaction fees, the other two cards do, making it a one-card system when traveling (with a 1X floor). Wells Fargo’s collection of transfer partners is undoubtedly the weakest of all the programs we’re comparing. Currently, there are only eight, including the different Avios programs that effectively function as one. The only domestic airline is JetBlue, and the only hotel partners are Choice Privileges and Wyndham Rewards (both with an excellent 1:2 transfer ratio). If Wells Fargo can beef up its partner list to rival the other issuers listed here, this will become a much more delectable combo. Like Amex and Citibank, Wells Fargo no longer allows you to transfer points to other users.
Which is the best credit card combo?
So, which combo is best? It’s difficult to answer that question without understanding the needs of the person who’s asking. Any of these combos may be best for you, depending on your tolerance for annual fees, your spending patterns, and how you’re likely to use your rewards. Picking one “best” is harder than it’s ever been.
Bilt offers excellent value and earning potential, but you need a second participant to use multiple cards, and the high annual fees will be increasingly intrusive for those who sign up after 1/1/27 and don’t have a housing payment. Because one person can’t have more than one card, it’s hard to call this the best combo, and you can get plenty of value from the Palladium or Obsidian card on their own, especially if you have a monthly housing payment.
Getting 1:1 transfers to Hyatt is getting increasingly difficult…and expensive. With Bilt moving to a 4:3 ratio to Hyatt, the Chase combo becomes the only way to retain 1:1 Hyatt transfers, something that can be extended to additional household players because of Chase’s transfer policy. However, the $795 annual fee is the highest on this list, and it requires you to get significant value from the various coupons. That said, it’s less than $200 more than the Bilt “combo,” which is pretty amazing given how many more credits the Chase version offers.
I love the Citi combo because it offers probably the best all-around card listed here for category bonuses: the Strata Premier, which earns 3x at gas stations, grocery stores, restaurants, AND travel – all on one card. I can give player 2 (my wife) a Double Cash and the Strata Premier and know that she’s earning 2x everywhere and 3x at most of the places that she spends money. Citi has a great mix of airline partners, including American Airlines, EVA Air, and Japan Airlines. However, lodging has taken a big hit: Preferred Hotels is now 1:2, Choice is 1:1.5, and Leading Hotels of the World offers 25% more value through Amex (4:1 vs 5:1). Additionally, closing the Custom Cash to new applicants removes the ability to earn 5X in the category of your choice on $500/month in purchases.
For many folks, the Capital One Venture X + Savor combo will be best, because it only requires holding two cards and offers substantial rewards in popular categories (3x grocery, dining, and entertainment); strong rewards on all other spend (2x); no foreign transaction fees; and ultra-premium card features (airport lounge access and travel protections) all for “free after rebate” (spend $395, but get back $300 in travel credits and 10K points each year).
Final Thoughts
I have and use almost all of the cards listed above, but if I had to pick one “combo,” it would probably be Chase, surprisingly enough. Capital One would come in second by a hair. I’ve had great luck combining points boosts with my Edit credits to get excellent value; add in 1:1 transfers to Hyatt, and there are reasonable paths to get good value for both lodging and flights. I also like the earning potential, travel protections, and lounge access.
That’s a huge change from last year, when I had Citi number one, but after downgrading its lodging transfers, removing the Custom Cash card, and nixing the ability to move points to other cardholders, it’s lost enough appeal to no longer reign supreme. I also love my Bilt Palladium card and plan to keep it as long as I can keep the current earning regime, but as a combo, the need to have a second player, pay over $600 in annual fees, and accept sub-1:1 Hyatt transfers makes it tough to pick.
All of the combos listed here could be best, depending on the individual, and I could make an argument for any of them. In reality, I use a “multi-combo combo,” that combines several of them; that may be the best choice for others as well. If you do expand into multiple currencies, be careful to keep an eye on those annual fees to make sure you’re getting enough value out of your wallet to justify the expense.
Card Info: Amex Pay Over Time Card issued by Amex. This card has no foreign currency conversion fees.
Noteworthy perks: Up to $10 in statement credits monthly with participating dining partners (Grubhub (including Seamless), Buffalo Wild Wings, Five Guys, The Cheesecake Factory, and Wonder) ✦ $10 monthly Uber or Uber Eats credit (use it or lose it each month – must select Amex card as payment method to redeem) ✦ Up to $7 monthly Dunkin’ credit – enrollment required ✦ Up to $50 twice-annual Resy credit ✦ $100 hotel credit on qualifying charges on stays of 2 nights or longer, plus a room upgrade upon arrival, if available with The Hotel Collection at americanexpress.com/hc ✦ Complimentary Hertz Five Star® Status ✦ Enrollment required for select benefits.
FM Mini Review: 2X rewards for all eligible purchases (up to $50K per year) with no annual fee makes this card a winner. Click here for our complete card review
No Annual Fee
Earning rate: 2X Membership Rewards points on all eligible purchases, up to $50K spend per calendar year (then 1X thereafter). Terms apply. (Rates & Fees)
Card Info: Amex Credit Card issued by Amex. This card imposes foreign transaction fees.
Combo details: Amex automatically pools all your Membership Rewards points, even if you earned them with different cards. While you can’t move points from one person to another, you can transfer points to a friend’s airline or hotel program account if they are an authorized user (or employee) on one of your accounts.
Why it’s great: This combination delivers terrific earning potential (2X to 4X everywhere in the US!) and lets you transfer points to Amex’s valuable transfer Partners. Traditionally, Amex has offered more transfer bonuses than other issuers, though that has changed over the last year or so. For those who can use the Gold card’s $10/month dining, 2x$50 Resy credits, and $10/month Uber/Uber Eats credits, the $325 annual fee becomes easier to justify.
Shortcomings: Yearly limits and foreign travel. The Gold card’s 4X grocery bonus is capped at $25K in annual spend and is limited to stores in the US, while the 4X at restaurants is worldwide but capped at $50K/year. The Blue Business Plus card charges foreign transaction fees and limits the 2X bonus to $50K per year, making this a less desirable combo for those who spend big or for those looking for great rewards on spending outside of the United States…and since Amex often isn’t accepted outside of the United States, you’ll want a backup Visa or Mastercard when traveling anyway. This combo also requires a business card to earn 2x everywhere.
Add-on: There are several worthwhile cards to consider adding to this combo:
The Platinum Card® offers a compelling lineup of perks and boosts flight earnings to 5X. Unfortunately, it also adds an $895 annual fee.
Also worth looking at is the Schwab Platinum Card, which has many similar perks to the Business Platinum and lets you cash out points at 1.1 cents each (1 million points/year max).
+1X on up to $50K in purchases using accelerators ($25K on each card)
Double rewards on the first of the month (1,000 bonus points max)
Perks include: earn rewards on housing payments, earn 4% Bilt Cash per dollar, which you can redeem toward housing payments or credits, 2 x $200 hotel credit per year *this will change for cards approved 1/1/27 or later – read more here*
Earning rate: 4% Bilt Cash on everyday purchases if you choose Bilt Cash rather than housing-only rewards + 3X points on dining or grocery (Limit $25K per year for grocery) ✦ 2X points on travel ✦ 1X points on everyday purchases ✦ 0.5X-1.25X points on rent & mortgage payments (if Housing-Only Earnings selected) ✦ 1X points on rent & mortgage payments when redeeming Bilt Cash (if Bilt Cash earning option selected)
Card Info: Mastercard World Elite issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ Up to $100 in Bilt Travel hotel credits ($50 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments
Card Info: Mastercard World Legend issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $200 Bilt Cash annually ✦ Up to $400 in Bilt Travel hotel credits ($200 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments ✦ Priority Pass (excludes restaurants)
Combo details: First off, Bilt only lets you have one Bilt card, so this combo is only possible if you have a 2nd player in the household that can add you as an authorized user (AU) to the second card. Bilt is unique in that it lets AU cards earn points and Bilt Cash to the AU’s account, so you can capture the earning categories (and accelerators) on both, but it also adds an additional fee of $50 for the Obsidian or $95 for the Palladium.
Why it’s great: This is another combo that offers excellent earning potential (2X to 4X everywhere), and Bilt has what most folks consider the best portfolio of transfer partners. It offers several 50%-100% Rent Day transfer bonuses per year that can deliver incredible value when transferring points. Using accelerators turns the Palladium card into a 3X everywhere earner, or even more if you’re also earning points on housing payments.
Shortcomings: First, you need two people to do it. Bilt doesn’t allow one person to be the primary cardholder on two cards. In addition, unlike many premium cards, there aren’t many included coupons, outside of 2 X $200 hotel credits on the Palladium and a $50 credit on the Obsidian, all of which require a two-night minimum and booking through Bilt’s travel portal. The earnings are great, but don’t forget that you’re still paying $600+ per year for them without the clear offsets of other cards. Starting 1/1/27, Bilt will lose 1:1 access to Hyatt, even with the Palladium card, which will be a big blow to the partner portfolio. Lastly, a third version of Bilt will take effect on January 1st, which represents a significant hit to earning power for folks who don’t earn points on housing payments.
Variation: Instead of incorporating the Obsidian card, you could use one Palladium card with an authorized user card that earns to the primary account. That setup would cost $590/year, but give you a total of $50K worth of 3X everywhere via accelerators. A downside is that AU card spend wouldn’t count toward elite status for the primary cardholder.
FM Mini Review: This card offers annual rebates that easily mitigate the fee for those who travel often. The card earns 2 miles per dollar on most purchases just like the Capital One Venture Rewards card, which are worth exactly 1 cent each toward travel. This makes the return on most spend similar to a 2% cash back card (though in this case you must redeem your miles to offset travel in order to get 1 cent per mile). One huge advantage over cash back: Capital One allows transfering their miles to airline miles & hotel points. Click here for our complete card review
$395 Annual Fee
Earning rate: 10X miles on hotels and rental cars booked via Capital One Travel ✦ 5X miles on flights and vacation rentals booked via Capital One travel ✦ 5X miles on Capital One Entertainment ✦ 2X miles everywhere else
Card Info: Visa Infinite issued by CapOne. This card has no foreign currency conversion fees.
Noteworthy perks: $300 annual credit for bookings made through Capital One Travel ✦ 10,000 bonus miles each year starting at first anniversary ✦ Up to $120 application fee credit for Global Entry or TSA PreCheck® ✦ Access to Capital One Lounge and Landing locations ✦ Priority Pass membership (participating lounges only) after enrollment ✦ Cell phone insurance ✦ Trip insurance ✦ Primary CDW coverage ✦ Redeem miles for travel at value of 1 cent per mile ✦ Transfer Miles to airline miles & hotel points
Earning rate: 8% cash back on Capital One Entertainment purchases ✦ 5% on hotels, vacation rentals, and rental cars booked via Capital One Travel (terms apply) ✦ 3% on dining, entertainment, select streaming services, and purchases at grocery stores (excluding superstores like Walmart® and Target®) ✦ 1% everywhere else
Base: 1%
Portal Hotels: 5%
Grocery: 3%
Dine: 3%
Card Info: Mastercard issued by CapOne. This card has no foreign currency conversion fees.
Combo details: Even though the Venture X has a $395 annual fee, you could consider this combo “almost free” after rebates, since it offers $300 in yearly Capital One Travel rebates plus 10K points each card anniversary, which together more than offset the annual fee. The fee-free Savor Cash Rewards adds 3x grocery, dining, and entertainment to the already strong 2x everywhere earnings offered by Venture X. Capital One lets you move cash back rewards to a “miles” card so that they then become transferable to partners. This allows you to earn 3% cash back with the Savor card and then convert that to “miles” by moving it to the Venture X card, unlocking better value by transferring to partners for high-value awards. You can also freely move points to anyone, so you don’t need more than one Venture X card in the family to make this combo work.
Why it’s great: Outstanding earnings with a “free after rebate” annual fee; this is the only combo that offers the same great earnings internationally with no foreign transaction fees. The Venture X provides excellent features such as cell phone protection, airport lounge access, and more. Capital One also offers arguably the best collection of card-linked offers. Additionally, Capital One is the only bank that has largely eschewed the stratospheric annual-fee coupon book for an ultra-premium card. It offers solid value without the mental load.
Shortcomings: The only way to get better than 1 cent per “Mile” value is by transferring to airline and hotel partners. Fewer opportunities for multiple, blingy welcome offers than Chase or Amex. Transfer partner portfolio lags behind Amex, Bilt, Citi, and Chase.
Variations:
Swap Venture X for Venture Rewards: Lower the annual fee to $95 per year with the Venture Rewards card instead of Venture X. Both offer 2x everywhere earnings, no foreign transaction fees, and the ability to transfer to airline and hotel partners. However, the Venture Rewards card doesn’t offer annual rebates that offset the annual fee and doesn’t offer lounge access.
Make it fee-free: You can cobble together a decent combo with no annual fees (and still have no foreign transaction fees). Start with the Savor for 3x grocery, dining, and entertainment, and then add the fee-free Quicksilver card to get 1.5x everywhere else, and then move all that cash back to the fee-free VentureOne Rewards card in order to transfer “Miles” to airline and hotel partners.
4X flights and hotels booked directly (Sapphire Reserve)
3X dining (Sapphire Reserve)
3X drug store (Freedom Unlimited)
2X gas stations (Ink Cash)
1.5X everywhere else (Freedom Unlimited)
Perks include 1:1 transfers to Hyatt, lounge access, up to $300 in annual travel rebates, up to $300 in annual dining credits, up to $300 in annual StubHub credits, up to $500 in annual The Edit credits, no foreign transaction fees, and excellent travel protections.
FM Mini Review: Good all-around card for frequent traveler. Best when paired with no annual fee Chase Freedom Flex, Freedom Unlimited & Chase Ink Cash cards. Click here for our complete card review
$795 Annual Fee
Earning rate: 8X Chase Travel℠ ✦ 4X flights and hotels booked direct ✦ 3X Dining ✦ 5X Lyft (through September 2027)
Card Info: Visa Infinite issued by Chase. This card has no foreign currency conversion fees.
Big spend bonus: After spending $75,000 each calendar year, get the following benefits: IHG One Rewards Diamond Elite Status ✦ World of Hyatt Explorist Status ✦ Southwest Airlines A-List Status ✦ $500 Southwest Airlines credit when booked through Chase Travel ✦ $250 credit to The Shops at Chase
Noteworthy perks: $300 Annual Travel Credit ✦ Transfer points to airline & hotel partners ✦ Up to $500 The Edit credit annually ($250 twice per calendar year) ✦ Up to $300 Dining credit through Sapphire Reserve Exclusive Tables ($150 January to June and again July to December) ✦ Complimentary Apple TV and Apple Music for a minimum of one year when activated by 6/22/27 ✦ Up to $300 in StubHub credits ($150 January to June and again July to December) ✦ Points worth up to 2 cents each towards qualified bookings through Chase Travel ✦ Primary auto rental coverage ✦ Priority Pass Select lounge access ✦ Access Sapphire Lounges for yourself and 2 guests for free ✦ Access select Air Canada Maple Leaf lounges when flying Star Alliance ✦ Up to $120 Global Entry or TSA PreCheck® or NEXUS Application Fee Statement Credit ✦ IHG One Rewards Platinum status through 12/31/27 ✦ Free DoorDash DashPass through 2027 ✦ Two promos of $10 off each month on non-restaurant orders from DoorDash ✦ $15 off restaurant order each month from DoorDash ✦ $10 monthly Lyft credit
FM Mini Review: Great for 3X categories and 1.5X everywhere else. Excellent companion card to Sapphire Reserve®, Sapphire Preferred®, or Ink Business Preferred®. Click here for our complete card review
No Annual Fee
Earning rate: 5X travel booked through Chase Travel℠ ✦ 3X dining ✦ 3X drugstores ✦ 2% cash back total on qualifying Lyft products and services purchased through the Lyft mobile application through 09/30/2027 ✦ 1.5X everywhere else
FM Mini Review: This one should be in everyone’s wallet. Incredible welcome offer for a no-annual-fee card. Great card for 5X categories. Excellent companion card to Sapphire Reserve, Sapphire Preferred, or Ink Business Preferred. Click here for our complete card review
No Annual Fee
Earning rate: 5X office supplies and cellular/landline/cable (on up to $25,000 in total purchases in 5X categories annually) ✦ 2X on the first $25K in combined purchases at gas stations and restaurants each cardmember year ✦ 5x Lyft through September 2027
Card Info: Visa Signature Business issued by Chase. This card imposes foreign transaction fees.
Noteworthy perks: Complimentary Instacart+ for 3 months (must activate by 12/31/27) ✦ $20 monthly Instacart credit ✦ $10 off each month on one non-restaurant order from DoorDash
Combo details: Many of Chase’s no-annual-fee cards are advertised as cashback cards, but they actually earn Ultimate Rewards points. Once you have points in one of these accounts, you can move them to your Sapphire Reserve account to make them transferable. Chase lets you move points to another person in the same household, so it makes sense for a couple to earn points across a variety of Ultimate Rewards cards and then move them all to a single Sapphire Reserve account. The Sapphire Reserve card provides three ways to get good value from your points: 1) transfer to airline and hotel partners for high-value awards; 2) book through Chase Travel℠ using points boosts at a value of up to 2 cents per point; and 3) erase statement charges at 1.25 cents per point value against current Pay Yourself Back categories (see this post for details).
Why it’s great: This is the only combo listed here that offers 1:1 transfers to Hyatt, which can translate into incredible value. Points are also worth up to 2 cents each toward select bookings via Chase Travel℠, but only on bookings with points boosts, which is a limited subset. You can sometimes get even better value by transferring points to Chase’s high-value travel partners. The Sapphire Reserve offers excellent automatic travel protections…provided that you don’t live in New York.
Shortcomings: Requires three cards instead of two. The Sapphire Reserve card costs $795 per year, and the value you get from the array of rebates will vary from person to person. The Freedom Unlimited and Ink Business Cash cards charge foreign exchange fees, so you’ll want to use your Sapphire Reserve card when traveling outside of the US, at which point you’re only earning 1X everywhere. This is also the only combo in this roundup that doesn’t offer a standard grocery bonus and doesn’t have a 2X everywhere option.
Add-on: Consider adding the no-fee Chase Freedom Flex card, which offers rotating 5X categories.
Variation: You can lower annual fees to $95 per year by replacing the Sapphire Reserve with either the Sapphire Preferred® or the Ink Business Preferred®. Both let you transfer points to travel hotel and airline partners and still offer the expansive “travel” category bonus the Sapphire Reserve lost in the 2025 refresh. However, both also have a reduced 4:3 transfer ratio to World of Hyatt
FM Mini Review: Very strong earnings for spend. Excellent bonus categories. Points transferable to select airlines. Recommend pairing this card with Citi Double Cash Click here for our complete card review
$95 Annual Fee
Earning rate: 10X hotels, car rentals, and attractions booked through Citi Travel℠ ✦ 3X grocery ✦ 3X dining ✦ 3X gas stations & EV charging ✦ 3X flights, hotels, travel agencies ✦ 1x everywhere else
Card Info: Mastercard World Elite issued by Citi. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $100 Annual Hotel Savings Benefit ($100 off a $500+ hotel stay, excluding taxes and fees, when booked through Citi Travel) ✦ Travel protections
FM Mini Review: 2X rewards for all spend with no annual fee makes this card a winner. Earn 2X everywhere and redeem for the equivalent of 2% cash back or 2X ThankYou points. Pair with the Premier or Prestige card to make points transferrable to airlines. Click here for our complete card review
No Annual Fee
Earning rate: 2% cash back everywhere ✦ Earn 3% total cash back on hotel, car rentals, and attractions booked on Citi Travel℠ Portal
Combo details: Citi lets you pool ThankYou points across your cards to get the best possible redemption value. You can also transfer points to anyone, but once you do, you must use them within 90 days, or they’ll expire.
Why it’s great: Excellent point earnings, especially for a combo with a total $95 annual fee (the Strata Premier card costs $95 per year, while the other cards are free). Both provide free authorized user cards. Travel partners are an intriguing mix of airlines and hotels, with unique 1:1 options like American AAdvantage, EVA Air, and Japan Airlines.
Shortcomings: Citi no longer allows you to share points with other cardholders. It has also effectively discontinued options for earning more than 1 cent per point, outside of transferring points to partners, and has tanked the transfer ratios of its most valuable lodging partners. Earlier this year, Citi stopped accepting applications for the Custom Cash, removing the only option for 5X earning. Lastly, Citi offers somewhat lackluster travel protections compared with some of the other card combinations listed here.
FM Mini Review: This card offers a competitive flat 2% back on purchases and includes good cell phone insurance for a no annual fee card (up to $600 in protection with just a $25 deductible). Pair with a Wells Fargo Autograph or Autograph Journey card to make the rewards transferable to airline and hotel partners.
Card Info: Visa issued by Wells. This card imposes foreign transaction fees.
Combo details: Like Capital One, Wells Fargo lets you transfer cash rewards to the Autograph Journey card at a 1:1 ratio. This lets you transfer rewards earned on both cards to travel partners. Wells Fargo also lets you transfer as little as one point to a partner program, making it easy to avoid leaving orphaned rewards in a partner account.
Why it’s great: These cards offer excellent points earnings for a total $95 annual fee, not including the $50 yearly airfare credit that comes with the Autograph Journey. 5x at hotels is another unique feature of this combo. The cards offer decent travel and purchase protections, plus very good cell phone insurance.
Shortcomings: A big downside is that this combo has no grocery bonus, so the best that you can do is 2x with the Active Cash. While the Autograph Journey doesn’t have foreign transaction fees, the other two cards do, making it a one-card system when traveling (with a 1X floor). Wells Fargo’s collection of transfer partners is undoubtedly the weakest of all the programs we’re comparing. Currently, there are only eight, including the different Avios programs that effectively function as one. The only domestic airline is JetBlue, and the only hotel partners are Choice Privileges and Wyndham Rewards (both with an excellent 1:2 transfer ratio). If Wells Fargo can beef up its partner list to rival the other issuers listed here, this will become a much more delectable combo. Like Amex and Citibank, Wells Fargo no longer allows you to transfer points to other users.
Which is the best credit card combo?
So, which combo is best? It’s difficult to answer that question without understanding the needs of the person who’s asking. Any of these combos may be best for you, depending on your tolerance for annual fees, your spending patterns, and how you’re likely to use your rewards. Picking one “best” is harder than it’s ever been.
Bilt offers excellent value and earning potential, but you need a second participant to use multiple cards, and the high annual fees will be increasingly intrusive for those who sign up after 1/1/27 and don’t have a housing payment. Because one person can’t have more than one card, it’s hard to call this the best combo, and you can get plenty of value from the Palladium or Obsidian card on their own, especially if you have a monthly housing payment.
Getting 1:1 transfers to Hyatt is getting increasingly difficult…and expensive. With Bilt moving to a 4:3 ratio to Hyatt, the Chase combo becomes the only way to retain 1:1 Hyatt transfers, something that can be extended to additional household players because of Chase’s transfer policy. However, the $795 annual fee is the highest on this list, and it requires you to get significant value from the various coupons. That said, it’s less than $200 more than the Bilt “combo,” which is pretty amazing given how many more credits the Chase version offers.
I love the Citi combo because it offers probably the best all-around card listed here for category bonuses: the Strata Premier, which earns 3x at gas stations, grocery stores, restaurants, AND travel – all on one card. I can give player 2 (my wife) a Double Cash and the Strata Premier and know that she’s earning 2x everywhere and 3x at most of the places that she spends money. Citi has a great mix of airline partners, including American Airlines, EVA Air, and Japan Airlines. However, lodging has taken a big hit: Preferred Hotels is now 1:2, Choice is 1:1.5, and Leading Hotels of the World offers 25% more value through Amex (4:1 vs 5:1). Additionally, closing the Custom Cash to new applicants removes the ability to earn 5X in the category of your choice on $500/month in purchases.
For many folks, the Capital One Venture X + Savor combo will be best, because it only requires holding two cards and offers substantial rewards in popular categories (3x grocery, dining, and entertainment); strong rewards on all other spend (2x); no foreign transaction fees; and ultra-premium card features (airport lounge access and travel protections) all for “free after rebate” (spend $395, but get back $300 in travel credits and 10K points each year).
Final Thoughts
I have and use almost all of the cards listed above, but if I had to pick one “combo,” it would probably be Chase, surprisingly enough. Capital One would come in second by a hair. I’ve had great luck combining points boosts with my Edit credits to get excellent value; add in 1:1 transfers to Hyatt, and there are reasonable paths to get good value for both lodging and flights. I also like the earning potential, travel protections, and lounge access.
That’s a huge change from last year, when I had Citi number one, but after downgrading its lodging transfers, removing the Custom Cash card, and nixing the ability to move points to other cardholders, it’s lost enough appeal to no longer reign supreme. I also love my Bilt Palladium card and plan to keep it as long as I can keep the current earning regime, but as a combo, the need to have a second player, pay over $600 in annual fees, and accept sub-1:1 Hyatt transfers makes it tough to pick.
All of the combos listed here could be best, depending on the individual, and I could make an argument for any of them. In reality, I use a “multi-combo combo,” that combines several of them; that may be the best choice for others as well. If you do expand into multiple currencies, be careful to keep an eye on those annual fees to make sure you’re getting enough value out of your wallet to justify the expense.
Card Info: Amex Pay Over Time Card issued by Amex. This card has no foreign currency conversion fees.
Noteworthy perks: Up to $10 in statement credits monthly with participating dining partners (Grubhub (including Seamless), Buffalo Wild Wings, Five Guys, The Cheesecake Factory, and Wonder) ✦ $10 monthly Uber or Uber Eats credit (use it or lose it each month – must select Amex card as payment method to redeem) ✦ Up to $7 monthly Dunkin’ credit – enrollment required ✦ Up to $50 twice-annual Resy credit ✦ $100 hotel credit on qualifying charges on stays of 2 nights or longer, plus a room upgrade upon arrival, if available with The Hotel Collection at americanexpress.com/hc ✦ Complimentary Hertz Five Star® Status ✦ Enrollment required for select benefits.
FM Mini Review: 2X rewards for all eligible purchases (up to $50K per year) with no annual fee makes this card a winner. Click here for our complete card review
No Annual Fee
Earning rate: 2X Membership Rewards points on all eligible purchases, up to $50K spend per calendar year (then 1X thereafter). Terms apply. (Rates & Fees)
Card Info: Amex Credit Card issued by Amex. This card imposes foreign transaction fees.
Combo details: Amex automatically pools all your Membership Rewards points, even if you earned them with different cards. While you can’t move points from one person to another, you can transfer points to a friend’s airline or hotel program account if they are an authorized user (or employee) on one of your accounts.
Why it’s great: This combination delivers terrific earning potential (2X to 4X everywhere in the US!) and lets you transfer points to Amex’s valuable transfer Partners. Traditionally, Amex has offered more transfer bonuses than other issuers, though that has changed over the last year or so. For those who can use the Gold card’s $10/month dining, 2x$50 Resy credits, and $10/month Uber/Uber Eats credits, the $325 annual fee becomes easier to justify.
Shortcomings: Yearly limits and foreign travel. The Gold card’s 4X grocery bonus is capped at $25K in annual spend and is limited to stores in the US, while the 4X at restaurants is worldwide but capped at $50K/year. The Blue Business Plus card charges foreign transaction fees and limits the 2X bonus to $50K per year, making this a less desirable combo for those who spend big or for those looking for great rewards on spending outside of the United States…and since Amex often isn’t accepted outside of the United States, you’ll want a backup Visa or Mastercard when traveling anyway. This combo also requires a business card to earn 2x everywhere.
Add-on: There are several worthwhile cards to consider adding to this combo:
The Platinum Card® offers a compelling lineup of perks and boosts flight earnings to 5X. Unfortunately, it also adds an $895 annual fee.
Also worth looking at is the Schwab Platinum Card, which has many similar perks to the Business Platinum and lets you cash out points at 1.1 cents each (1 million points/year max).
+1X on up to $50K in purchases using accelerators ($25K on each card)
Double rewards on the first of the month (1,000 bonus points max)
Perks include: earn rewards on housing payments, earn 4% Bilt Cash per dollar, which you can redeem toward housing payments or credits, 2 x $200 hotel credit per year *this will change for cards approved 1/1/27 or later – read more here*
Earning rate: 4% Bilt Cash on everyday purchases if you choose Bilt Cash rather than housing-only rewards + 3X points on dining or grocery (Limit $25K per year for grocery) ✦ 2X points on travel ✦ 1X points on everyday purchases ✦ 0.5X-1.25X points on rent & mortgage payments (if Housing-Only Earnings selected) ✦ 1X points on rent & mortgage payments when redeeming Bilt Cash (if Bilt Cash earning option selected)
Card Info: Mastercard World Elite issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ Up to $100 in Bilt Travel hotel credits ($50 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments
Card Info: Mastercard World Legend issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $200 Bilt Cash annually ✦ Up to $400 in Bilt Travel hotel credits ($200 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments ✦ Priority Pass (excludes restaurants)
Combo details: First off, Bilt only lets you have one Bilt card, so this combo is only possible if you have a 2nd player in the household that can add you as an authorized user (AU) to the second card. Bilt is unique in that it lets AU cards earn points and Bilt Cash to the AU’s account, so you can capture the earning categories (and accelerators) on both, but it also adds an additional fee of $50 for the Obsidian or $95 for the Palladium.
Why it’s great: This is another combo that offers excellent earning potential (2X to 4X everywhere), and Bilt has what most folks consider the best portfolio of transfer partners. It offers several 50%-100% Rent Day transfer bonuses per year that can deliver incredible value when transferring points. Using accelerators turns the Palladium card into a 3X everywhere earner, or even more if you’re also earning points on housing payments.
Shortcomings: First, you need two people to do it. Bilt doesn’t allow one person to be the primary cardholder on two cards. In addition, unlike many premium cards, there aren’t many included coupons, outside of 2 X $200 hotel credits on the Palladium and a $50 credit on the Obsidian, all of which require a two-night minimum and booking through Bilt’s travel portal. The earnings are great, but don’t forget that you’re still paying $600+ per year for them without the clear offsets of other cards. Starting 1/1/27, Bilt will lose 1:1 access to Hyatt, even with the Palladium card, which will be a big blow to the partner portfolio. Lastly, a third version of Bilt will take effect on January 1st, which represents a significant hit to earning power for folks who don’t earn points on housing payments.
Variation: Instead of incorporating the Obsidian card, you could use one Palladium card with an authorized user card that earns to the primary account. That setup would cost $590/year, but give you a total of $50K worth of 3X everywhere via accelerators. A downside is that AU card spend wouldn’t count toward elite status for the primary cardholder.
FM Mini Review: This card offers annual rebates that easily mitigate the fee for those who travel often. The card earns 2 miles per dollar on most purchases just like the Capital One Venture Rewards card, which are worth exactly 1 cent each toward travel. This makes the return on most spend similar to a 2% cash back card (though in this case you must redeem your miles to offset travel in order to get 1 cent per mile). One huge advantage over cash back: Capital One allows transfering their miles to airline miles & hotel points. Click here for our complete card review
$395 Annual Fee
Earning rate: 10X miles on hotels and rental cars booked via Capital One Travel ✦ 5X miles on flights and vacation rentals booked via Capital One travel ✦ 5X miles on Capital One Entertainment ✦ 2X miles everywhere else
Card Info: Visa Infinite issued by CapOne. This card has no foreign currency conversion fees.
Noteworthy perks: $300 annual credit for bookings made through Capital One Travel ✦ 10,000 bonus miles each year starting at first anniversary ✦ Up to $120 application fee credit for Global Entry or TSA PreCheck® ✦ Access to Capital One Lounge and Landing locations ✦ Priority Pass membership (participating lounges only) after enrollment ✦ Cell phone insurance ✦ Trip insurance ✦ Primary CDW coverage ✦ Redeem miles for travel at value of 1 cent per mile ✦ Transfer Miles to airline miles & hotel points
Earning rate: 8% cash back on Capital One Entertainment purchases ✦ 5% on hotels, vacation rentals, and rental cars booked via Capital One Travel (terms apply) ✦ 3% on dining, entertainment, select streaming services, and purchases at grocery stores (excluding superstores like Walmart® and Target®) ✦ 1% everywhere else
Base: 1%
Portal Hotels: 5%
Grocery: 3%
Dine: 3%
Card Info: Mastercard issued by CapOne. This card has no foreign currency conversion fees.
Combo details: Even though the Venture X has a $395 annual fee, you could consider this combo “almost free” after rebates, since it offers $300 in yearly Capital One Travel rebates plus 10K points each card anniversary, which together more than offset the annual fee. The fee-free Savor Cash Rewards adds 3x grocery, dining, and entertainment to the already strong 2x everywhere earnings offered by Venture X. Capital One lets you move cash back rewards to a “miles” card so that they then become transferable to partners. This allows you to earn 3% cash back with the Savor card and then convert that to “miles” by moving it to the Venture X card, unlocking better value by transferring to partners for high-value awards. You can also freely move points to anyone, so you don’t need more than one Venture X card in the family to make this combo work.
Why it’s great: Outstanding earnings with a “free after rebate” annual fee; this is the only combo that offers the same great earnings internationally with no foreign transaction fees. The Venture X provides excellent features such as cell phone protection, airport lounge access, and more. Capital One also offers arguably the best collection of card-linked offers. Additionally, Capital One is the only bank that has largely eschewed the stratospheric annual-fee coupon book for an ultra-premium card. It offers solid value without the mental load.
Shortcomings: The only way to get better than 1 cent per “Mile” value is by transferring to airline and hotel partners. Fewer opportunities for multiple, blingy welcome offers than Chase or Amex. Transfer partner portfolio lags behind Amex, Bilt, Citi, and Chase.
Variations:
Swap Venture X for Venture Rewards: Lower the annual fee to $95 per year with the Venture Rewards card instead of Venture X. Both offer 2x everywhere earnings, no foreign transaction fees, and the ability to transfer to airline and hotel partners. However, the Venture Rewards card doesn’t offer annual rebates that offset the annual fee and doesn’t offer lounge access.
Make it fee-free: You can cobble together a decent combo with no annual fees (and still have no foreign transaction fees). Start with the Savor for 3x grocery, dining, and entertainment, and then add the fee-free Quicksilver card to get 1.5x everywhere else, and then move all that cash back to the fee-free VentureOne Rewards card in order to transfer “Miles” to airline and hotel partners.
4X flights and hotels booked directly (Sapphire Reserve)
3X dining (Sapphire Reserve)
3X drug store (Freedom Unlimited)
2X gas stations (Ink Cash)
1.5X everywhere else (Freedom Unlimited)
Perks include 1:1 transfers to Hyatt, lounge access, up to $300 in annual travel rebates, up to $300 in annual dining credits, up to $300 in annual StubHub credits, up to $500 in annual The Edit credits, no foreign transaction fees, and excellent travel protections.
FM Mini Review: Good all-around card for frequent traveler. Best when paired with no annual fee Chase Freedom Flex, Freedom Unlimited & Chase Ink Cash cards. Click here for our complete card review
$795 Annual Fee
Earning rate: 8X Chase Travel℠ ✦ 4X flights and hotels booked direct ✦ 3X Dining ✦ 5X Lyft (through September 2027)
Card Info: Visa Infinite issued by Chase. This card has no foreign currency conversion fees.
Big spend bonus: After spending $75,000 each calendar year, get the following benefits: IHG One Rewards Diamond Elite Status ✦ World of Hyatt Explorist Status ✦ Southwest Airlines A-List Status ✦ $500 Southwest Airlines credit when booked through Chase Travel ✦ $250 credit to The Shops at Chase
Noteworthy perks: $300 Annual Travel Credit ✦ Transfer points to airline & hotel partners ✦ Up to $500 The Edit credit annually ($250 twice per calendar year) ✦ Up to $300 Dining credit through Sapphire Reserve Exclusive Tables ($150 January to June and again July to December) ✦ Complimentary Apple TV and Apple Music for a minimum of one year when activated by 6/22/27 ✦ Up to $300 in StubHub credits ($150 January to June and again July to December) ✦ Points worth up to 2 cents each towards qualified bookings through Chase Travel ✦ Primary auto rental coverage ✦ Priority Pass Select lounge access ✦ Access Sapphire Lounges for yourself and 2 guests for free ✦ Access select Air Canada Maple Leaf lounges when flying Star Alliance ✦ Up to $120 Global Entry or TSA PreCheck® or NEXUS Application Fee Statement Credit ✦ IHG One Rewards Platinum status through 12/31/27 ✦ Free DoorDash DashPass through 2027 ✦ Two promos of $10 off each month on non-restaurant orders from DoorDash ✦ $15 off restaurant order each month from DoorDash ✦ $10 monthly Lyft credit
FM Mini Review: Great for 3X categories and 1.5X everywhere else. Excellent companion card to Sapphire Reserve®, Sapphire Preferred®, or Ink Business Preferred®. Click here for our complete card review
No Annual Fee
Earning rate: 5X travel booked through Chase Travel℠ ✦ 3X dining ✦ 3X drugstores ✦ 2% cash back total on qualifying Lyft products and services purchased through the Lyft mobile application through 09/30/2027 ✦ 1.5X everywhere else
FM Mini Review: This one should be in everyone’s wallet. Incredible welcome offer for a no-annual-fee card. Great card for 5X categories. Excellent companion card to Sapphire Reserve, Sapphire Preferred, or Ink Business Preferred. Click here for our complete card review
No Annual Fee
Earning rate: 5X office supplies and cellular/landline/cable (on up to $25,000 in total purchases in 5X categories annually) ✦ 2X on the first $25K in combined purchases at gas stations and restaurants each cardmember year ✦ 5x Lyft through September 2027
Card Info: Visa Signature Business issued by Chase. This card imposes foreign transaction fees.
Noteworthy perks: Complimentary Instacart+ for 3 months (must activate by 12/31/27) ✦ $20 monthly Instacart credit ✦ $10 off each month on one non-restaurant order from DoorDash
Combo details: Many of Chase’s no-annual-fee cards are advertised as cashback cards, but they actually earn Ultimate Rewards points. Once you have points in one of these accounts, you can move them to your Sapphire Reserve account to make them transferable. Chase lets you move points to another person in the same household, so it makes sense for a couple to earn points across a variety of Ultimate Rewards cards and then move them all to a single Sapphire Reserve account. The Sapphire Reserve card provides three ways to get good value from your points: 1) transfer to airline and hotel partners for high-value awards; 2) book through Chase Travel℠ using points boosts at a value of up to 2 cents per point; and 3) erase statement charges at 1.25 cents per point value against current Pay Yourself Back categories (see this post for details).
Why it’s great: This is the only combo listed here that offers 1:1 transfers to Hyatt, which can translate into incredible value. Points are also worth up to 2 cents each toward select bookings via Chase Travel℠, but only on bookings with points boosts, which is a limited subset. You can sometimes get even better value by transferring points to Chase’s high-value travel partners. The Sapphire Reserve offers excellent automatic travel protections…provided that you don’t live in New York.
Shortcomings: Requires three cards instead of two. The Sapphire Reserve card costs $795 per year, and the value you get from the array of rebates will vary from person to person. The Freedom Unlimited and Ink Business Cash cards charge foreign exchange fees, so you’ll want to use your Sapphire Reserve card when traveling outside of the US, at which point you’re only earning 1X everywhere. This is also the only combo in this roundup that doesn’t offer a standard grocery bonus and doesn’t have a 2X everywhere option.
Add-on: Consider adding the no-fee Chase Freedom Flex card, which offers rotating 5X categories.
Variation: You can lower annual fees to $95 per year by replacing the Sapphire Reserve with either the Sapphire Preferred® or the Ink Business Preferred®. Both let you transfer points to travel hotel and airline partners and still offer the expansive “travel” category bonus the Sapphire Reserve lost in the 2025 refresh. However, both also have a reduced 4:3 transfer ratio to World of Hyatt
FM Mini Review: Very strong earnings for spend. Excellent bonus categories. Points transferable to select airlines. Recommend pairing this card with Citi Double Cash Click here for our complete card review
$95 Annual Fee
Earning rate: 10X hotels, car rentals, and attractions booked through Citi Travel℠ ✦ 3X grocery ✦ 3X dining ✦ 3X gas stations & EV charging ✦ 3X flights, hotels, travel agencies ✦ 1x everywhere else
Card Info: Mastercard World Elite issued by Citi. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $100 Annual Hotel Savings Benefit ($100 off a $500+ hotel stay, excluding taxes and fees, when booked through Citi Travel) ✦ Travel protections
FM Mini Review: 2X rewards for all spend with no annual fee makes this card a winner. Earn 2X everywhere and redeem for the equivalent of 2% cash back or 2X ThankYou points. Pair with the Premier or Prestige card to make points transferrable to airlines. Click here for our complete card review
No Annual Fee
Earning rate: 2% cash back everywhere ✦ Earn 3% total cash back on hotel, car rentals, and attractions booked on Citi Travel℠ Portal
Combo details: Citi lets you pool ThankYou points across your cards to get the best possible redemption value. You can also transfer points to anyone, but once you do, you must use them within 90 days, or they’ll expire.
Why it’s great: Excellent point earnings, especially for a combo with a total $95 annual fee (the Strata Premier card costs $95 per year, while the other cards are free). Both provide free authorized user cards. Travel partners are an intriguing mix of airlines and hotels, with unique 1:1 options like American AAdvantage, EVA Air, and Japan Airlines.
Shortcomings: Citi no longer allows you to share points with other cardholders. It has also effectively discontinued options for earning more than 1 cent per point, outside of transferring points to partners, and has tanked the transfer ratios of its most valuable lodging partners. Earlier this year, Citi stopped accepting applications for the Custom Cash, removing the only option for 5X earning. Lastly, Citi offers somewhat lackluster travel protections compared with some of the other card combinations listed here.
FM Mini Review: This card offers a competitive flat 2% back on purchases and includes good cell phone insurance for a no annual fee card (up to $600 in protection with just a $25 deductible). Pair with a Wells Fargo Autograph or Autograph Journey card to make the rewards transferable to airline and hotel partners.
Card Info: Visa issued by Wells. This card imposes foreign transaction fees.
Combo details: Like Capital One, Wells Fargo lets you transfer cash rewards to the Autograph Journey card at a 1:1 ratio. This lets you transfer rewards earned on both cards to travel partners. Wells Fargo also lets you transfer as little as one point to a partner program, making it easy to avoid leaving orphaned rewards in a partner account.
Why it’s great: These cards offer excellent points earnings for a total $95 annual fee, not including the $50 yearly airfare credit that comes with the Autograph Journey. 5x at hotels is another unique feature of this combo. The cards offer decent travel and purchase protections, plus very good cell phone insurance.
Shortcomings: A big downside is that this combo has no grocery bonus, so the best that you can do is 2x with the Active Cash. While the Autograph Journey doesn’t have foreign transaction fees, the other two cards do, making it a one-card system when traveling (with a 1X floor). Wells Fargo’s collection of transfer partners is undoubtedly the weakest of all the programs we’re comparing. Currently, there are only eight, including the different Avios programs that effectively function as one. The only domestic airline is JetBlue, and the only hotel partners are Choice Privileges and Wyndham Rewards (both with an excellent 1:2 transfer ratio). If Wells Fargo can beef up its partner list to rival the other issuers listed here, this will become a much more delectable combo. Like Amex and Citibank, Wells Fargo no longer allows you to transfer points to other users.
Which is the best credit card combo?
So, which combo is best? It’s difficult to answer that question without understanding the needs of the person who’s asking. Any of these combos may be best for you, depending on your tolerance for annual fees, your spending patterns, and how you’re likely to use your rewards. Picking one “best” is harder than it’s ever been.
Bilt offers excellent value and earning potential, but you need a second participant to use multiple cards, and the high annual fees will be increasingly intrusive for those who sign up after 1/1/27 and don’t have a housing payment. Because one person can’t have more than one card, it’s hard to call this the best combo, and you can get plenty of value from the Palladium or Obsidian card on their own, especially if you have a monthly housing payment.
Getting 1:1 transfers to Hyatt is getting increasingly difficult…and expensive. With Bilt moving to a 4:3 ratio to Hyatt, the Chase combo becomes the only way to retain 1:1 Hyatt transfers, something that can be extended to additional household players because of Chase’s transfer policy. However, the $795 annual fee is the highest on this list, and it requires you to get significant value from the various coupons. That said, it’s less than $200 more than the Bilt “combo,” which is pretty amazing given how many more credits the Chase version offers.
I love the Citi combo because it offers probably the best all-around card listed here for category bonuses: the Strata Premier, which earns 3x at gas stations, grocery stores, restaurants, AND travel – all on one card. I can give player 2 (my wife) a Double Cash and the Strata Premier and know that she’s earning 2x everywhere and 3x at most of the places that she spends money. Citi has a great mix of airline partners, including American Airlines, EVA Air, and Japan Airlines. However, lodging has taken a big hit: Preferred Hotels is now 1:2, Choice is 1:1.5, and Leading Hotels of the World offers 25% more value through Amex (4:1 vs 5:1). Additionally, closing the Custom Cash to new applicants removes the ability to earn 5X in the category of your choice on $500/month in purchases.
For many folks, the Capital One Venture X + Savor combo will be best, because it only requires holding two cards and offers substantial rewards in popular categories (3x grocery, dining, and entertainment); strong rewards on all other spend (2x); no foreign transaction fees; and ultra-premium card features (airport lounge access and travel protections) all for “free after rebate” (spend $395, but get back $300 in travel credits and 10K points each year).
Final Thoughts
I have and use almost all of the cards listed above, but if I had to pick one “combo,” it would probably be Chase, surprisingly enough. Capital One would come in second by a hair. I’ve had great luck combining points boosts with my Edit credits to get excellent value; add in 1:1 transfers to Hyatt, and there are reasonable paths to get good value for both lodging and flights. I also like the earning potential, travel protections, and lounge access.
That’s a huge change from last year, when I had Citi number one, but after downgrading its lodging transfers, removing the Custom Cash card, and nixing the ability to move points to other cardholders, it’s lost enough appeal to no longer reign supreme. I also love my Bilt Palladium card and plan to keep it as long as I can keep the current earning regime, but as a combo, the need to have a second player, pay over $600 in annual fees, and accept sub-1:1 Hyatt transfers makes it tough to pick.
All of the combos listed here could be best, depending on the individual, and I could make an argument for any of them. In reality, I use a “multi-combo combo,” that combines several of them; that may be the best choice for others as well. If you do expand into multiple currencies, be careful to keep an eye on those annual fees to make sure you’re getting enough value out of your wallet to justify the expense.
Card Info: Amex Pay Over Time Card issued by Amex. This card has no foreign currency conversion fees.
Noteworthy perks: Up to $10 in statement credits monthly with participating dining partners (Grubhub (including Seamless), Buffalo Wild Wings, Five Guys, The Cheesecake Factory, and Wonder) ✦ $10 monthly Uber or Uber Eats credit (use it or lose it each month – must select Amex card as payment method to redeem) ✦ Up to $7 monthly Dunkin’ credit – enrollment required ✦ Up to $50 twice-annual Resy credit ✦ $100 hotel credit on qualifying charges on stays of 2 nights or longer, plus a room upgrade upon arrival, if available with The Hotel Collection at americanexpress.com/hc ✦ Complimentary Hertz Five Star® Status ✦ Enrollment required for select benefits.
FM Mini Review: 2X rewards for all eligible purchases (up to $50K per year) with no annual fee makes this card a winner. Click here for our complete card review
No Annual Fee
Earning rate: 2X Membership Rewards points on all eligible purchases, up to $50K spend per calendar year (then 1X thereafter). Terms apply. (Rates & Fees)
Card Info: Amex Credit Card issued by Amex. This card imposes foreign transaction fees.
Combo details: Amex automatically pools all your Membership Rewards points, even if you earned them with different cards. While you can’t move points from one person to another, you can transfer points to a friend’s airline or hotel program account if they are an authorized user (or employee) on one of your accounts.
Why it’s great: This combination delivers terrific earning potential (2X to 4X everywhere in the US!) and lets you transfer points to Amex’s valuable transfer Partners. Traditionally, Amex has offered more transfer bonuses than other issuers, though that has changed over the last year or so. For those who can use the Gold card’s $10/month dining, 2x$50 Resy credits, and $10/month Uber/Uber Eats credits, the $325 annual fee becomes easier to justify.
Shortcomings: Yearly limits and foreign travel. The Gold card’s 4X grocery bonus is capped at $25K in annual spend and is limited to stores in the US, while the 4X at restaurants is worldwide but capped at $50K/year. The Blue Business Plus card charges foreign transaction fees and limits the 2X bonus to $50K per year, making this a less desirable combo for those who spend big or for those looking for great rewards on spending outside of the United States…and since Amex often isn’t accepted outside of the United States, you’ll want a backup Visa or Mastercard when traveling anyway. This combo also requires a business card to earn 2x everywhere.
Add-on: There are several worthwhile cards to consider adding to this combo:
The Platinum Card® offers a compelling lineup of perks and boosts flight earnings to 5X. Unfortunately, it also adds an $895 annual fee.
Also worth looking at is the Schwab Platinum Card, which has many similar perks to the Business Platinum and lets you cash out points at 1.1 cents each (1 million points/year max).
+1X on up to $50K in purchases using accelerators ($25K on each card)
Double rewards on the first of the month (1,000 bonus points max)
Perks include: earn rewards on housing payments, earn 4% Bilt Cash per dollar, which you can redeem toward housing payments or credits, 2 x $200 hotel credit per year *this will change for cards approved 1/1/27 or later – read more here*
Earning rate: 4% Bilt Cash on everyday purchases if you choose Bilt Cash rather than housing-only rewards + 3X points on dining or grocery (Limit $25K per year for grocery) ✦ 2X points on travel ✦ 1X points on everyday purchases ✦ 0.5X-1.25X points on rent & mortgage payments (if Housing-Only Earnings selected) ✦ 1X points on rent & mortgage payments when redeeming Bilt Cash (if Bilt Cash earning option selected)
Card Info: Mastercard World Elite issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ Up to $100 in Bilt Travel hotel credits ($50 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments
Card Info: Mastercard World Legend issued by Column NA. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $200 Bilt Cash annually ✦ Up to $400 in Bilt Travel hotel credits ($200 per six months, two-night stay required) ✦ Earn points on rent or mortgage payments ✦ Priority Pass (excludes restaurants)
Combo details: First off, Bilt only lets you have one Bilt card, so this combo is only possible if you have a 2nd player in the household that can add you as an authorized user (AU) to the second card. Bilt is unique in that it lets AU cards earn points and Bilt Cash to the AU’s account, so you can capture the earning categories (and accelerators) on both, but it also adds an additional fee of $50 for the Obsidian or $95 for the Palladium.
Why it’s great: This is another combo that offers excellent earning potential (2X to 4X everywhere), and Bilt has what most folks consider the best portfolio of transfer partners. It offers several 50%-100% Rent Day transfer bonuses per year that can deliver incredible value when transferring points. Using accelerators turns the Palladium card into a 3X everywhere earner, or even more if you’re also earning points on housing payments.
Shortcomings: First, you need two people to do it. Bilt doesn’t allow one person to be the primary cardholder on two cards. In addition, unlike many premium cards, there aren’t many included coupons, outside of 2 X $200 hotel credits on the Palladium and a $50 credit on the Obsidian, all of which require a two-night minimum and booking through Bilt’s travel portal. The earnings are great, but don’t forget that you’re still paying $600+ per year for them without the clear offsets of other cards. Starting 1/1/27, Bilt will lose 1:1 access to Hyatt, even with the Palladium card, which will be a big blow to the partner portfolio. Lastly, a third version of Bilt will take effect on January 1st, which represents a significant hit to earning power for folks who don’t earn points on housing payments.
Variation: Instead of incorporating the Obsidian card, you could use one Palladium card with an authorized user card that earns to the primary account. That setup would cost $590/year, but give you a total of $50K worth of 3X everywhere via accelerators. A downside is that AU card spend wouldn’t count toward elite status for the primary cardholder.
FM Mini Review: This card offers annual rebates that easily mitigate the fee for those who travel often. The card earns 2 miles per dollar on most purchases just like the Capital One Venture Rewards card, which are worth exactly 1 cent each toward travel. This makes the return on most spend similar to a 2% cash back card (though in this case you must redeem your miles to offset travel in order to get 1 cent per mile). One huge advantage over cash back: Capital One allows transfering their miles to airline miles & hotel points. Click here for our complete card review
$395 Annual Fee
Earning rate: 10X miles on hotels and rental cars booked via Capital One Travel ✦ 5X miles on flights and vacation rentals booked via Capital One travel ✦ 5X miles on Capital One Entertainment ✦ 2X miles everywhere else
Card Info: Visa Infinite issued by CapOne. This card has no foreign currency conversion fees.
Noteworthy perks: $300 annual credit for bookings made through Capital One Travel ✦ 10,000 bonus miles each year starting at first anniversary ✦ Up to $120 application fee credit for Global Entry or TSA PreCheck® ✦ Access to Capital One Lounge and Landing locations ✦ Priority Pass membership (participating lounges only) after enrollment ✦ Cell phone insurance ✦ Trip insurance ✦ Primary CDW coverage ✦ Redeem miles for travel at value of 1 cent per mile ✦ Transfer Miles to airline miles & hotel points
Earning rate: 8% cash back on Capital One Entertainment purchases ✦ 5% on hotels, vacation rentals, and rental cars booked via Capital One Travel (terms apply) ✦ 3% on dining, entertainment, select streaming services, and purchases at grocery stores (excluding superstores like Walmart® and Target®) ✦ 1% everywhere else
Base: 1%
Portal Hotels: 5%
Grocery: 3%
Dine: 3%
Card Info: Mastercard issued by CapOne. This card has no foreign currency conversion fees.
Combo details: Even though the Venture X has a $395 annual fee, you could consider this combo “almost free” after rebates, since it offers $300 in yearly Capital One Travel rebates plus 10K points each card anniversary, which together more than offset the annual fee. The fee-free Savor Cash Rewards adds 3x grocery, dining, and entertainment to the already strong 2x everywhere earnings offered by Venture X. Capital One lets you move cash back rewards to a “miles” card so that they then become transferable to partners. This allows you to earn 3% cash back with the Savor card and then convert that to “miles” by moving it to the Venture X card, unlocking better value by transferring to partners for high-value awards. You can also freely move points to anyone, so you don’t need more than one Venture X card in the family to make this combo work.
Why it’s great: Outstanding earnings with a “free after rebate” annual fee; this is the only combo that offers the same great earnings internationally with no foreign transaction fees. The Venture X provides excellent features such as cell phone protection, airport lounge access, and more. Capital One also offers arguably the best collection of card-linked offers. Additionally, Capital One is the only bank that has largely eschewed the stratospheric annual-fee coupon book for an ultra-premium card. It offers solid value without the mental load.
Shortcomings: The only way to get better than 1 cent per “Mile” value is by transferring to airline and hotel partners. Fewer opportunities for multiple, blingy welcome offers than Chase or Amex. Transfer partner portfolio lags behind Amex, Bilt, Citi, and Chase.
Variations:
Swap Venture X for Venture Rewards: Lower the annual fee to $95 per year with the Venture Rewards card instead of Venture X. Both offer 2x everywhere earnings, no foreign transaction fees, and the ability to transfer to airline and hotel partners. However, the Venture Rewards card doesn’t offer annual rebates that offset the annual fee and doesn’t offer lounge access.
Make it fee-free: You can cobble together a decent combo with no annual fees (and still have no foreign transaction fees). Start with the Savor for 3x grocery, dining, and entertainment, and then add the fee-free Quicksilver card to get 1.5x everywhere else, and then move all that cash back to the fee-free VentureOne Rewards card in order to transfer “Miles” to airline and hotel partners.
4X flights and hotels booked directly (Sapphire Reserve)
3X dining (Sapphire Reserve)
3X drug store (Freedom Unlimited)
2X gas stations (Ink Cash)
1.5X everywhere else (Freedom Unlimited)
Perks include 1:1 transfers to Hyatt, lounge access, up to $300 in annual travel rebates, up to $300 in annual dining credits, up to $300 in annual StubHub credits, up to $500 in annual The Edit credits, no foreign transaction fees, and excellent travel protections.
FM Mini Review: Good all-around card for frequent traveler. Best when paired with no annual fee Chase Freedom Flex, Freedom Unlimited & Chase Ink Cash cards. Click here for our complete card review
$795 Annual Fee
Earning rate: 8X Chase Travel℠ ✦ 4X flights and hotels booked direct ✦ 3X Dining ✦ 5X Lyft (through September 2027)
Card Info: Visa Infinite issued by Chase. This card has no foreign currency conversion fees.
Big spend bonus: After spending $75,000 each calendar year, get the following benefits: IHG One Rewards Diamond Elite Status ✦ World of Hyatt Explorist Status ✦ Southwest Airlines A-List Status ✦ $500 Southwest Airlines credit when booked through Chase Travel ✦ $250 credit to The Shops at Chase
Noteworthy perks: $300 Annual Travel Credit ✦ Transfer points to airline & hotel partners ✦ Up to $500 The Edit credit annually ($250 twice per calendar year) ✦ Up to $300 Dining credit through Sapphire Reserve Exclusive Tables ($150 January to June and again July to December) ✦ Complimentary Apple TV and Apple Music for a minimum of one year when activated by 6/22/27 ✦ Up to $300 in StubHub credits ($150 January to June and again July to December) ✦ Points worth up to 2 cents each towards qualified bookings through Chase Travel ✦ Primary auto rental coverage ✦ Priority Pass Select lounge access ✦ Access Sapphire Lounges for yourself and 2 guests for free ✦ Access select Air Canada Maple Leaf lounges when flying Star Alliance ✦ Up to $120 Global Entry or TSA PreCheck® or NEXUS Application Fee Statement Credit ✦ IHG One Rewards Platinum status through 12/31/27 ✦ Free DoorDash DashPass through 2027 ✦ Two promos of $10 off each month on non-restaurant orders from DoorDash ✦ $15 off restaurant order each month from DoorDash ✦ $10 monthly Lyft credit
FM Mini Review: Great for 3X categories and 1.5X everywhere else. Excellent companion card to Sapphire Reserve®, Sapphire Preferred®, or Ink Business Preferred®. Click here for our complete card review
No Annual Fee
Earning rate: 5X travel booked through Chase Travel℠ ✦ 3X dining ✦ 3X drugstores ✦ 2% cash back total on qualifying Lyft products and services purchased through the Lyft mobile application through 09/30/2027 ✦ 1.5X everywhere else
FM Mini Review: This one should be in everyone’s wallet. Incredible welcome offer for a no-annual-fee card. Great card for 5X categories. Excellent companion card to Sapphire Reserve, Sapphire Preferred, or Ink Business Preferred. Click here for our complete card review
No Annual Fee
Earning rate: 5X office supplies and cellular/landline/cable (on up to $25,000 in total purchases in 5X categories annually) ✦ 2X on the first $25K in combined purchases at gas stations and restaurants each cardmember year ✦ 5x Lyft through September 2027
Card Info: Visa Signature Business issued by Chase. This card imposes foreign transaction fees.
Noteworthy perks: Complimentary Instacart+ for 3 months (must activate by 12/31/27) ✦ $20 monthly Instacart credit ✦ $10 off each month on one non-restaurant order from DoorDash
Combo details: Many of Chase’s no-annual-fee cards are advertised as cashback cards, but they actually earn Ultimate Rewards points. Once you have points in one of these accounts, you can move them to your Sapphire Reserve account to make them transferable. Chase lets you move points to another person in the same household, so it makes sense for a couple to earn points across a variety of Ultimate Rewards cards and then move them all to a single Sapphire Reserve account. The Sapphire Reserve card provides three ways to get good value from your points: 1) transfer to airline and hotel partners for high-value awards; 2) book through Chase Travel℠ using points boosts at a value of up to 2 cents per point; and 3) erase statement charges at 1.25 cents per point value against current Pay Yourself Back categories (see this post for details).
Why it’s great: This is the only combo listed here that offers 1:1 transfers to Hyatt, which can translate into incredible value. Points are also worth up to 2 cents each toward select bookings via Chase Travel℠, but only on bookings with points boosts, which is a limited subset. You can sometimes get even better value by transferring points to Chase’s high-value travel partners. The Sapphire Reserve offers excellent automatic travel protections…provided that you don’t live in New York.
Shortcomings: Requires three cards instead of two. The Sapphire Reserve card costs $795 per year, and the value you get from the array of rebates will vary from person to person. The Freedom Unlimited and Ink Business Cash cards charge foreign exchange fees, so you’ll want to use your Sapphire Reserve card when traveling outside of the US, at which point you’re only earning 1X everywhere. This is also the only combo in this roundup that doesn’t offer a standard grocery bonus and doesn’t have a 2X everywhere option.
Add-on: Consider adding the no-fee Chase Freedom Flex card, which offers rotating 5X categories.
Variation: You can lower annual fees to $95 per year by replacing the Sapphire Reserve with either the Sapphire Preferred® or the Ink Business Preferred®. Both let you transfer points to travel hotel and airline partners and still offer the expansive “travel” category bonus the Sapphire Reserve lost in the 2025 refresh. However, both also have a reduced 4:3 transfer ratio to World of Hyatt
FM Mini Review: Very strong earnings for spend. Excellent bonus categories. Points transferable to select airlines. Recommend pairing this card with Citi Double Cash Click here for our complete card review
$95 Annual Fee
Earning rate: 10X hotels, car rentals, and attractions booked through Citi Travel℠ ✦ 3X grocery ✦ 3X dining ✦ 3X gas stations & EV charging ✦ 3X flights, hotels, travel agencies ✦ 1x everywhere else
Card Info: Mastercard World Elite issued by Citi. This card has no foreign currency conversion fees.
Noteworthy perks: Transfer points to airline and hotel partners ✦ $100 Annual Hotel Savings Benefit ($100 off a $500+ hotel stay, excluding taxes and fees, when booked through Citi Travel) ✦ Travel protections
FM Mini Review: 2X rewards for all spend with no annual fee makes this card a winner. Earn 2X everywhere and redeem for the equivalent of 2% cash back or 2X ThankYou points. Pair with the Premier or Prestige card to make points transferrable to airlines. Click here for our complete card review
No Annual Fee
Earning rate: 2% cash back everywhere ✦ Earn 3% total cash back on hotel, car rentals, and attractions booked on Citi Travel℠ Portal
Combo details: Citi lets you pool ThankYou points across your cards to get the best possible redemption value. You can also transfer points to anyone, but once you do, you must use them within 90 days, or they’ll expire.
Why it’s great: Excellent point earnings, especially for a combo with a total $95 annual fee (the Strata Premier card costs $95 per year, while the other cards are free). Both provide free authorized user cards. Travel partners are an intriguing mix of airlines and hotels, with unique 1:1 options like American AAdvantage, EVA Air, and Japan Airlines.
Shortcomings: Citi no longer allows you to share points with other cardholders. It has also effectively discontinued options for earning more than 1 cent per point, outside of transferring points to partners, and has tanked the transfer ratios of its most valuable lodging partners. Earlier this year, Citi stopped accepting applications for the Custom Cash, removing the only option for 5X earning. Lastly, Citi offers somewhat lackluster travel protections compared with some of the other card combinations listed here.
FM Mini Review: This card offers a competitive flat 2% back on purchases and includes good cell phone insurance for a no annual fee card (up to $600 in protection with just a $25 deductible). Pair with a Wells Fargo Autograph or Autograph Journey card to make the rewards transferable to airline and hotel partners.
Card Info: Visa issued by Wells. This card imposes foreign transaction fees.
Combo details: Like Capital One, Wells Fargo lets you transfer cash rewards to the Autograph Journey card at a 1:1 ratio. This lets you transfer rewards earned on both cards to travel partners. Wells Fargo also lets you transfer as little as one point to a partner program, making it easy to avoid leaving orphaned rewards in a partner account.
Why it’s great: These cards offer excellent points earnings for a total $95 annual fee, not including the $50 yearly airfare credit that comes with the Autograph Journey. 5x at hotels is another unique feature of this combo. The cards offer decent travel and purchase protections, plus very good cell phone insurance.
Shortcomings: A big downside is that this combo has no grocery bonus, so the best that you can do is 2x with the Active Cash. While the Autograph Journey doesn’t have foreign transaction fees, the other two cards do, making it a one-card system when traveling (with a 1X floor). Wells Fargo’s collection of transfer partners is undoubtedly the weakest of all the programs we’re comparing. Currently, there are only eight, including the different Avios programs that effectively function as one. The only domestic airline is JetBlue, and the only hotel partners are Choice Privileges and Wyndham Rewards (both with an excellent 1:2 transfer ratio). If Wells Fargo can beef up its partner list to rival the other issuers listed here, this will become a much more delectable combo. Like Amex and Citibank, Wells Fargo no longer allows you to transfer points to other users.
Which is the best credit card combo?
So, which combo is best? It’s difficult to answer that question without understanding the needs of the person who’s asking. Any of these combos may be best for you, depending on your tolerance for annual fees, your spending patterns, and how you’re likely to use your rewards. Picking one “best” is harder than it’s ever been.
Bilt offers excellent value and earning potential, but you need a second participant to use multiple cards, and the high annual fees will be increasingly intrusive for those who sign up after 1/1/27 and don’t have a housing payment. Because one person can’t have more than one card, it’s hard to call this the best combo, and you can get plenty of value from the Palladium or Obsidian card on their own, especially if you have a monthly housing payment.
Getting 1:1 transfers to Hyatt is getting increasingly difficult…and expensive. With Bilt moving to a 4:3 ratio to Hyatt, the Chase combo becomes the only way to retain 1:1 Hyatt transfers, something that can be extended to additional household players because of Chase’s transfer policy. However, the $795 annual fee is the highest on this list, and it requires you to get significant value from the various coupons. That said, it’s less than $200 more than the Bilt “combo,” which is pretty amazing given how many more credits the Chase version offers.
I love the Citi combo because it offers probably the best all-around card listed here for category bonuses: the Strata Premier, which earns 3x at gas stations, grocery stores, restaurants, AND travel – all on one card. I can give player 2 (my wife) a Double Cash and the Strata Premier and know that she’s earning 2x everywhere and 3x at most of the places that she spends money. Citi has a great mix of airline partners, including American Airlines, EVA Air, and Japan Airlines. However, lodging has taken a big hit: Preferred Hotels is now 1:2, Choice is 1:1.5, and Leading Hotels of the World offers 25% more value through Amex (4:1 vs 5:1). Additionally, closing the Custom Cash to new applicants removes the ability to earn 5X in the category of your choice on $500/month in purchases.
For many folks, the Capital One Venture X + Savor combo will be best, because it only requires holding two cards and offers substantial rewards in popular categories (3x grocery, dining, and entertainment); strong rewards on all other spend (2x); no foreign transaction fees; and ultra-premium card features (airport lounge access and travel protections) all for “free after rebate” (spend $395, but get back $300 in travel credits and 10K points each year).
Final Thoughts
I have and use almost all of the cards listed above, but if I had to pick one “combo,” it would probably be Chase, surprisingly enough. Capital One would come in second by a hair. I’ve had great luck combining points boosts with my Edit credits to get excellent value; add in 1:1 transfers to Hyatt, and there are reasonable paths to get good value for both lodging and flights. I also like the earning potential, travel protections, and lounge access.
That’s a huge change from last year, when I had Citi number one, but after downgrading its lodging transfers, removing the Custom Cash card, and nixing the ability to move points to other cardholders, it’s lost enough appeal to no longer reign supreme. I also love my Bilt Palladium card and plan to keep it as long as I can keep the current earning regime, but as a combo, the need to have a second player, pay over $600 in annual fees, and accept sub-1:1 Hyatt transfers makes it tough to pick.
All of the combos listed here could be best, depending on the individual, and I could make an argument for any of them. In reality, I use a “multi-combo combo,” that combines several of them; that may be the best choice for others as well. If you do expand into multiple currencies, be careful to keep an eye on those annual fees to make sure you’re getting enough value out of your wallet to justify the expense.
JSX is bringing its popular semi-private flights to Beantown. The boutique air carrier plans to begin flying from Boston this winter, JSX said this week.…
The Delta SkyMiles® Gold American Express Card is the mid-range personal credit card in the American Express and Delta co-brand card portfolio, which includes seven…

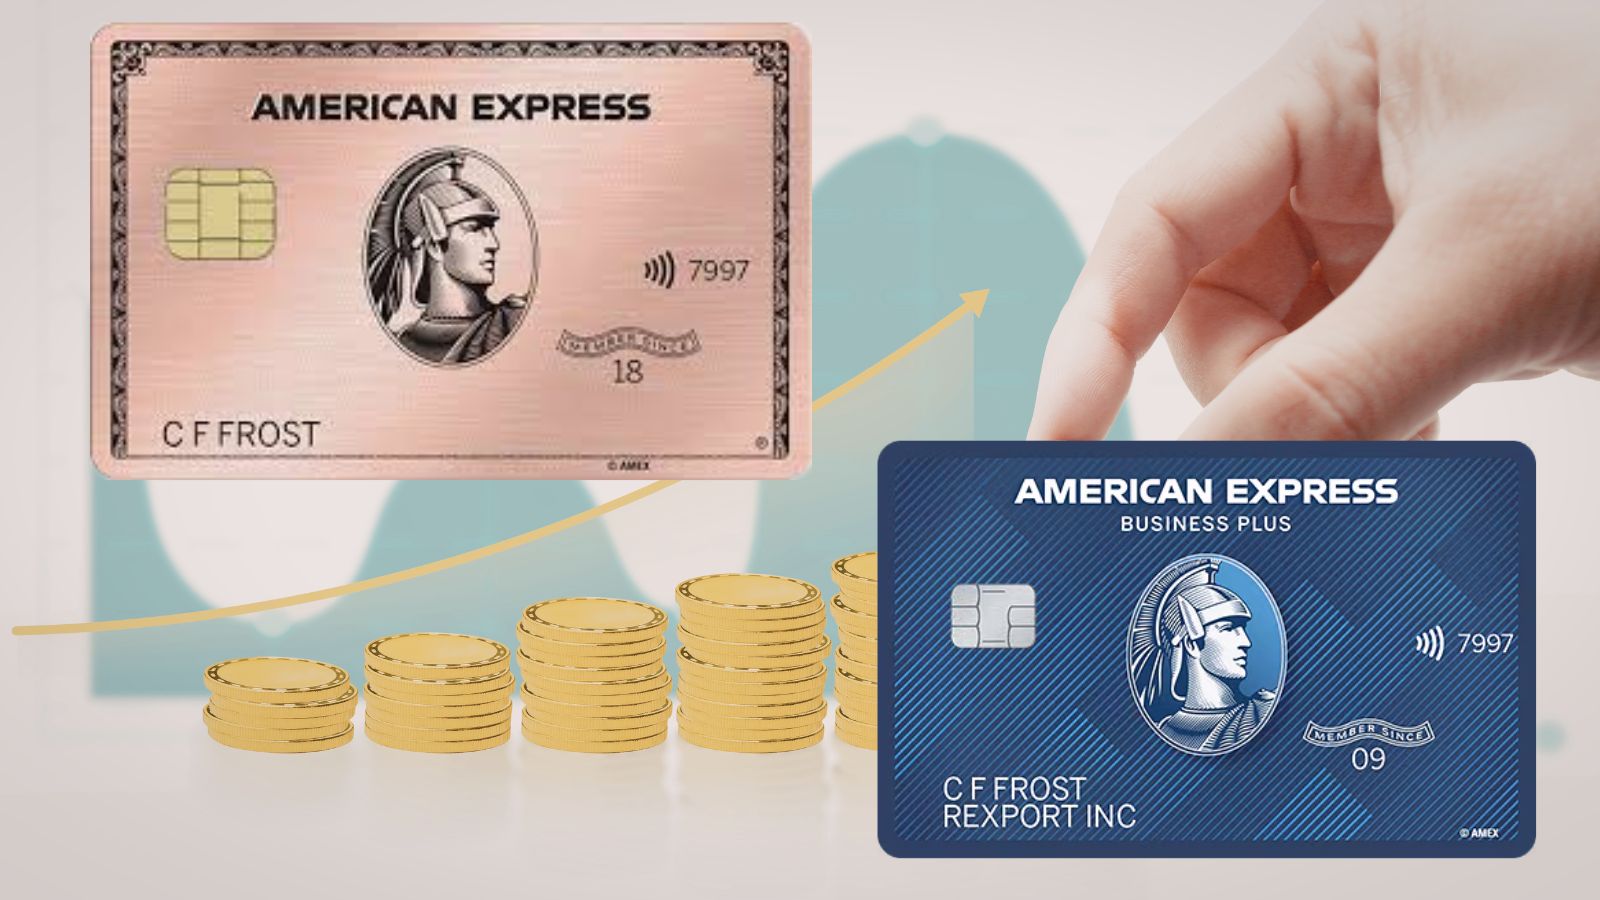

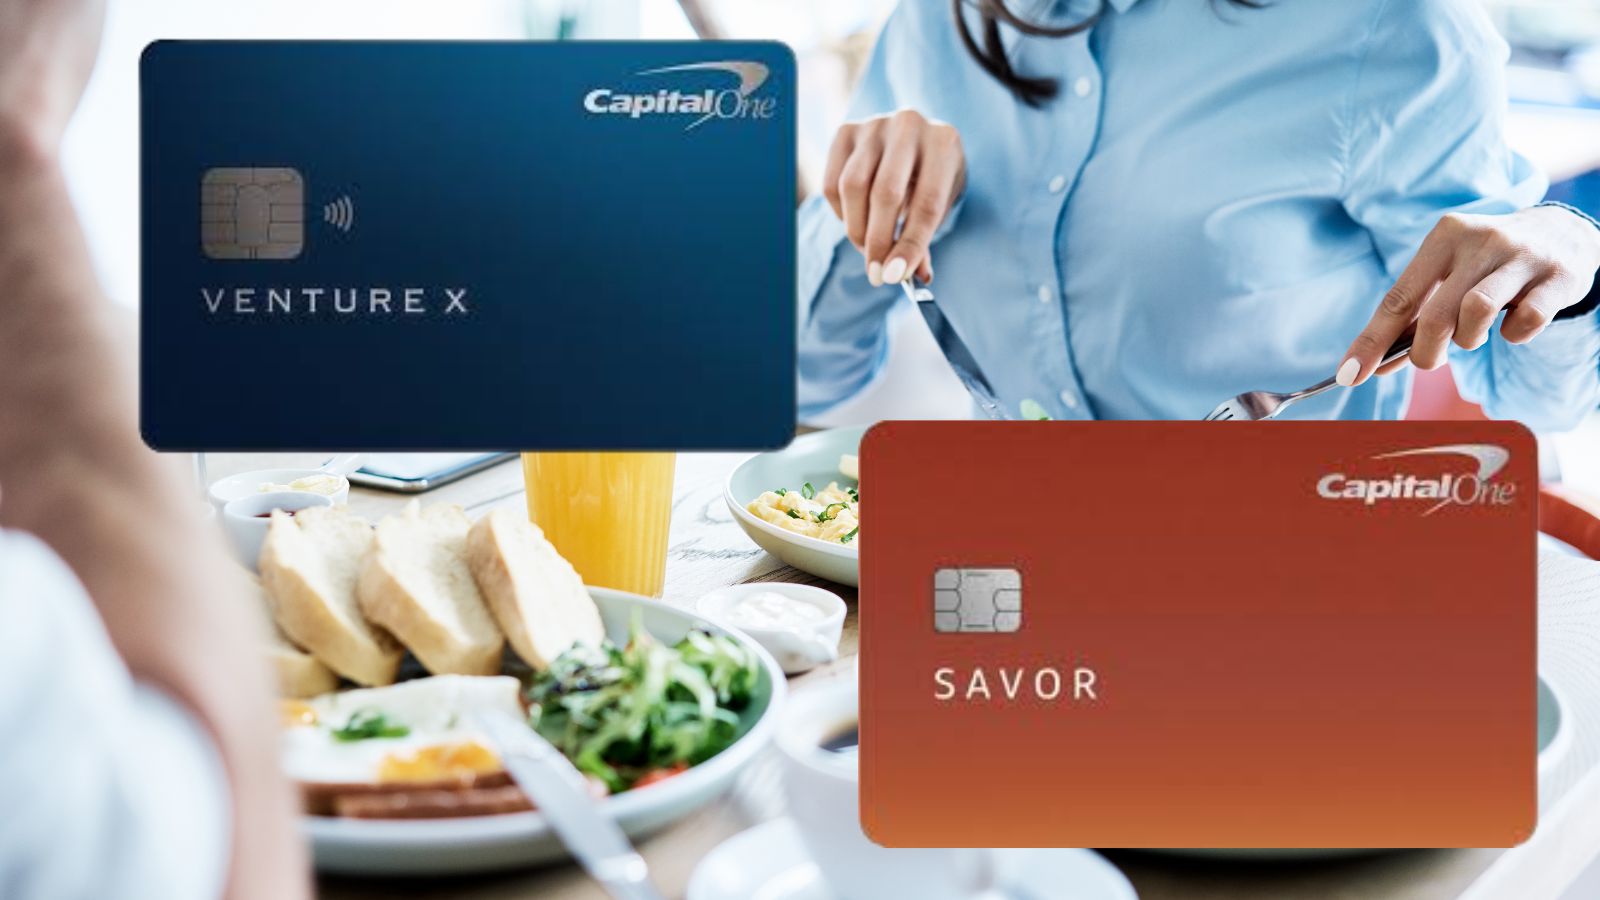
 membership (participating lounges only) after enrollment ✦ Cell phone insurance ✦ Trip insurance ✦ Primary CDW coverage ✦ Redeem miles for travel at value of 1 cent per mile ✦ Transfer Miles to airline miles & hotel points